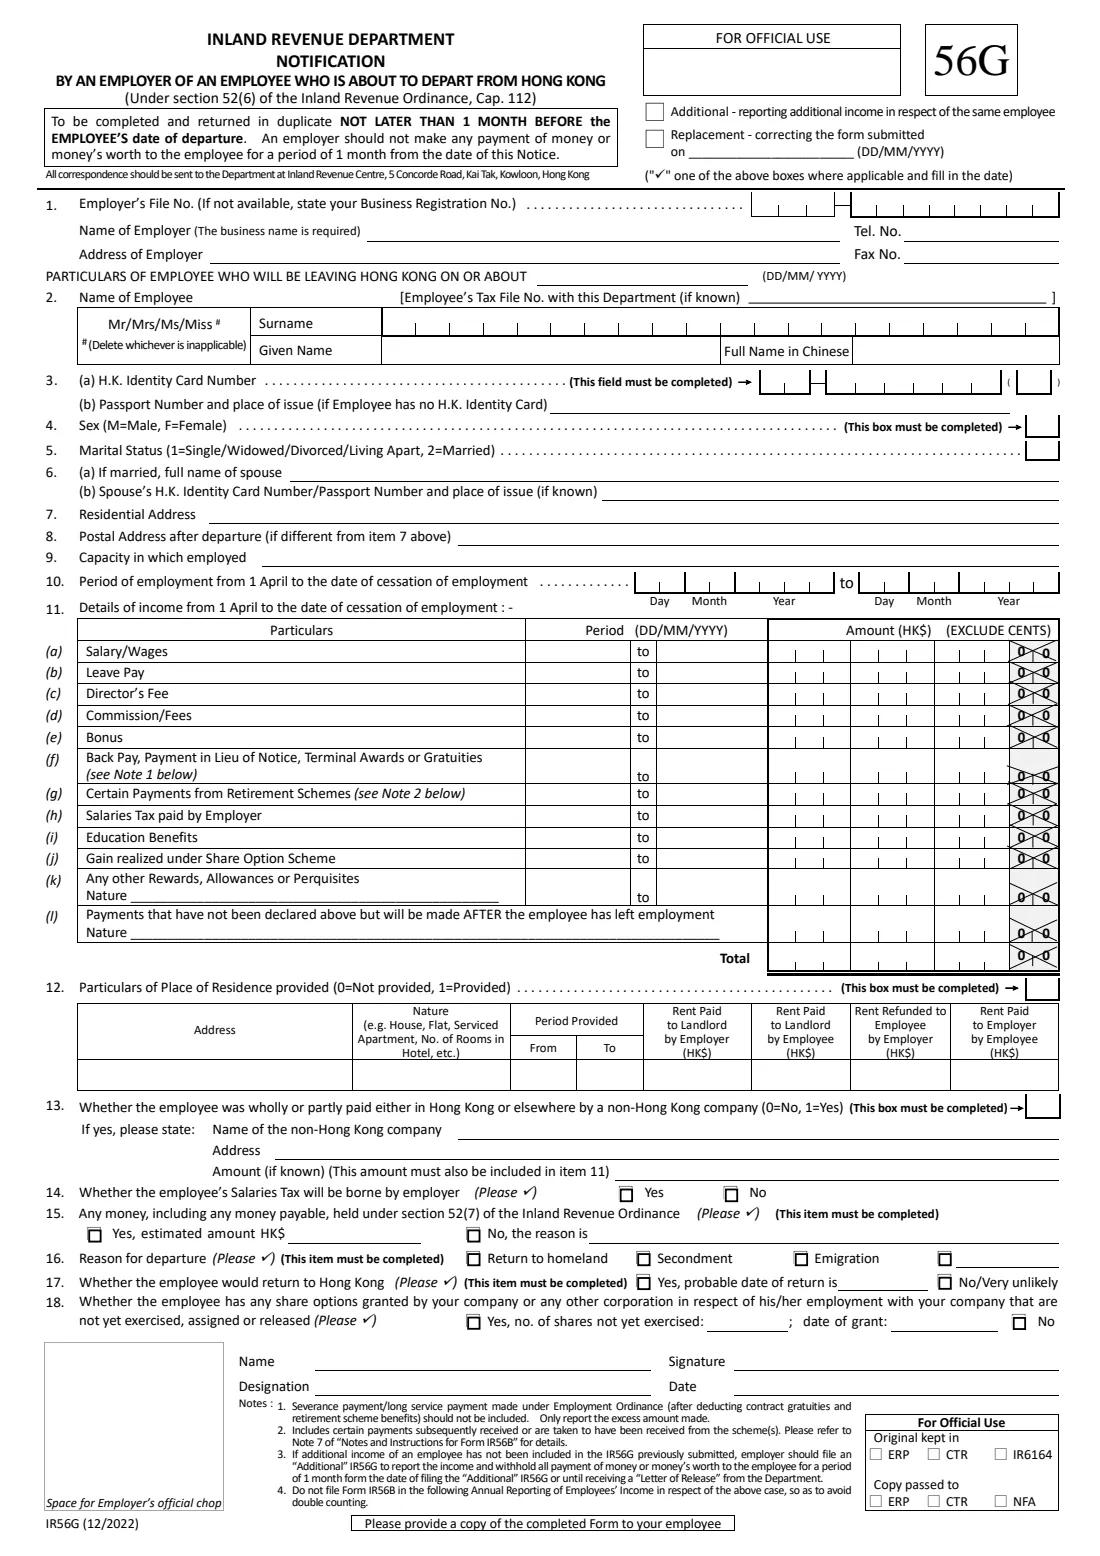
What is Form IR56G?
Form IR56G, 'Notification by an Employer of an Employee who is About to Depart from Hong Kong', is made under section 52(6) of the Inland Revenue Ordinance. It is Hong Kong's tax clearance procedure: the employer reports the employee's departure and their income from 1 April to the date of cessation, so the Inland Revenue Department (IRD) can settle the employee's Salaries Tax before they go. It must be returned in duplicate not later than 1 month before the employee's date of departure.
The form carries a real obligation. An employer should not make any payment of money or money's worth to the employee for a period of 1 month from the date of the notice, or until the IRD issues a Letter of Release, whichever is earlier. Items 15 to 18 ask about the money held, the reason for departure, whether the employee will return and any unexercised share options.
FileIt guides you through Form IR56G and prints your answers into the IRD's own PDF (the 12/2022 edition). It pre-fills the employee's and your business details from your vault, checks the HKID check digit, the income periods and dates, adds up the total income, ticks the right boxes in items 14 to 18 and files the finished form in the employee's folder. You print it twice, sign each copy by hand and send it yourself — FileIt never files anything with the IRD.
- Who fills it
- The employer of an employee who is about to leave Hong Kong
- Given to
- The Inland Revenue Department (the form gives Inland Revenue Centre, 5 Concorde Road, Kai Tak, Kowloon for correspondence) — or through the IRD's e-filing services
- When
- Not later than 1 month before the employee's date of departure
- Copies
- In duplicate, plus a copy for the employee
- Signatures
- An original handwritten signature of a responsible person such as the proprietor, a director or company secretary
- Money withheld
- No payments to the employee for 1 month from the notice, or until the IRD's Letter of Release, whichever is earlier
- Edition
- IR56G (12/2022), 1 page
Who needs to fill out Form IR56G?
- Employers whose employee is leaving Hong Kong for good, for example returning to their homeland or emigrating.
- Employers seconding an employee out of Hong Kong for a substantial period.
- Household employers whose domestic helper is leaving Hong Kong at the end of the contract.
- Employers who need to report additional income paid after an IR56G was filed, using the 'Additional' box.
- Employers correcting a previously filed IR56G with a 'Replacement' form.
When to use Form IR56G
- As soon as you know an employee will leave Hong Kong, and not later than 1 month before the expected departure date.
- From the date of filing, stop paying the employee — for example the last month's salary — for 1 month or until you receive the Letter of Release.
- If more remuneration becomes payable after you filed (a bonus or vested share award, say), file an 'Additional' IR56G and withhold again, as Note 3 on the form explains.
- If the employee is staying in Hong Kong after the job ends, use Form IR56F instead.
What you need before you start
- Your employer's file number (or business registration number), business name, address, telephone and fax numbers.
- The date the employee will leave Hong Kong, and their tax file number with the IRD if known.
- The employee's English name, HKID number with check digit (or passport details), sex, marital status and spouse's details if married.
- Their residential address and a postal address after departure, which can be overseas.
- Payroll records from 1 April to the date of cessation, each item with its period.
- Details of housing provided, and of any amounts paid by a non-Hong Kong company.
- The amount of money you are holding under section 52(7), or the reason you hold none.
- The reason for departure, whether and when the employee may return, and any unexercised share options (number of shares and date of grant).
What’s on Form IR56G
The 2022 edition has 1 page. FileIt asks for it in 7 parts:
- Type of notificationEmployer
- 1. Particulars of the employerEmployer
- 2–9. Particulars of the employeeEmployer
- 10–11. Period of employment and income from 1 AprilEmployer
- 12–13. Housing and payments by a non-Hong Kong companyEmployer
- 14–18. Tax, money withheld, departure and share optionsEmployer
- SignatureEmployer
How to fill out Form IR56G, step by step
1 Additional / Replacement boxes
Leave both blank for a first IR56G. Tick 'Additional' to report extra income for an employee already notified — this triggers another month of withholding. Tick 'Replacement' to correct the details of a previous IR56G and give its submission date.
2 1. Employer's particulars and departure date
Give your employer's file number or business registration number, the business name, address, and telephone and fax numbers; the IRD's specimen asks for a contact phone number and the contact person's name if it isn't the signer. Then fill in the date the employee will leave Hong Kong — the specimen says it must be given.
3 2–9. Particulars of the employee
The surname and given name as on the HKID card or passport (FileIt strikes out the titles that don't apply), the employee's tax file number if known, the HKID number — which must be completed — or passport details, sex (M/F), marital status (1/2), the spouse's details if married, the residential address, the postal address after departure and the capacity in which employed. FileIt can't print Chinese characters, so write the Chinese name in by hand if needed.
4 10–11. Period of employment and income from 1 April
Give the period from 1 April (or the start date if later) to the date of cessation, and the income for that period only, in whole Hong Kong dollars, item by item with the dates each covers: salary, leave pay, director's fee, commission, bonus, back pay or payment in lieu of notice, certain retirement scheme payments, tax paid by the employer, education benefits, share option gains and other benefits. Item (l) covers payments to be made after the employee has left. FileIt totals the figures.
5 12–13. Housing and payment by a non-Hong Kong company
Enter 0 or 1 for a place of residence provided, with its address, nature, period and the rents involved. Then 0 or 1 for payment by a non-Hong Kong company, with its name, address and the amount if known, which must also be included in item 11.
6 14. Salaries Tax borne by the employer
Tick Yes if the employer will bear the employee's Salaries Tax, otherwise No.
7 15. Money held under section 52(7)
This item must be completed. Tick Yes with the estimated amount you are holding, or No with the reason. The employer should withhold all moneys payable to the employee, such as the last month's salary, for 1 month from filing or until the Letter of Release (IR607).
8 16–17. Reason for departure and return
Both must be completed. Tick return to homeland, secondment, emigration, or the last box with a short reason of your own. Then say whether the employee would return to Hong Kong, with a probable date of return, or tick No / very unlikely.
9 18. Unexercised share options
Tick Yes if the employee holds share options, granted by your company or another corporation in respect of the employment with you, that aren't yet exercised, assigned or released — with the number of shares and the date of grant. If they are later exercised, assigned or released, the gain is reported on Form IR56B.
10 Signature
Name, designation, signature and date of the responsible person, with space for the employer's chop.
Common mistakes to avoid
- Filing less than a month before departure — the form asks for at least 1 month's notice.
- Paying the employee's final salary or other money before the month is up or the Letter of Release arrives.
- Sending only one copy — the form is returned in duplicate.
- Leaving the departure date blank, or leaving items 15, 16 or 17 unanswered.
- Reporting income from before 1 April of the current year of assessment.
- Forgetting unexercised share options at item 18.
- Not filing an 'Additional' IR56G when more pay becomes due after the first one.
- Sending a photocopy, fax or scan instead of an originally signed form.
After you fill it out
Print two copies on white plain A4 paper and have the responsible person sign each by hand in blue or black ink. The IRD's completion notes say an originally signed form must be submitted; photocopies, fax copies, scans, name chops and printed signatures aren't accepted. Give the employee a copy too.
Send the forms to the Inland Revenue Department — the form gives Inland Revenue Centre, 5 Concorde Road, Kai Tak, Kowloon, Hong Kong for correspondence — or file through the IRD's e-filing services. Then hold back payments to the employee for 1 month from the date of the notice, or until the IRD's Letter of Release, whichever is earlier. The IRD's guidance also asks the employee to tell the Department of their departure and to file the tax return it issues to them.
FileIt keeps the completed PDF in the employee's vault folder, which helps if you need to file an additional IR56G for later payments, or when you release the money you held. Don't report the same income again on the annual IR56B.
Fill out Form IR56G online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 92 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real Inland Revenue Department (IRD), Hong Kong form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start Form IR56G now — it’s freeForm IR56G: frequently asked questions
What is Form IR56G?
Form IR56G is the Hong Kong Inland Revenue Department's 'Notification by an Employer of an Employee who is About to Depart from Hong Kong'. It is the employer's part of tax clearance for a departing employee, reporting their income from 1 April to the date of cessation.
How early must IR56G be filed?
Not later than 1 month before the employee's date of departure, and in duplicate, as printed on the form.
Do I have to withhold my employee's salary?
Yes. The form says an employer should not make any payment of money or money's worth to the employee for 1 month from the date of the notice. The IRD's guidance says the withholding ends after that month or when the Letter of Release is received, whichever is earlier.
What is a Letter of Release?
It is the IRD's letter (IR607) telling the employer it may release the money held. The IRD's guidance explains it is issued once the employee's tax is settled, and sent to the employer with a copy to the employee.
Can I fill in Form IR56G online with FileIt?
Yes. FileIt guides you through all 18 items, pre-fills from your People records, checks the HKID check digit and the dates, totals the income and produces the IRD's official PDF. Filling forms is available on every FileIt account, including the free plan.
Where do I send IR56G?
The form gives the Department's address as Inland Revenue Centre, 5 Concorde Road, Kai Tak, Kowloon, Hong Kong. You can also file through the IRD's e-filing services. FileIt doesn't send it for you.
Does IR56G apply to a domestic helper leaving Hong Kong?
The form covers any employee who is about to depart from Hong Kong, and a household employer completes it like any other employer. If you're unsure whether you need to file, check with the IRD.
Can IR56G be signed electronically?
Not the paper version: it must bear an original signature, and the IRD says photocopies, faxes and scans aren't acceptable. Print the PDF from FileIt and sign both copies by hand, or use the IRD's e-filing service.
Official sources
- Blank form (PDF), published by Inland Revenue Department (IRD), Hong Kong: https://www.ird.gov.hk/eng/pdf/ir56g.pdf
- Official instructions and guidance: https://www.ird.gov.hk/eng/pdf/ir56g_completion_e.pdf
- Edition shown on this page: IR56G (12/2022) (checked 2026-09-26).
FileIt is not affiliated with or endorsed by Inland Revenue Department (IRD), Hong Kong or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-09-26.