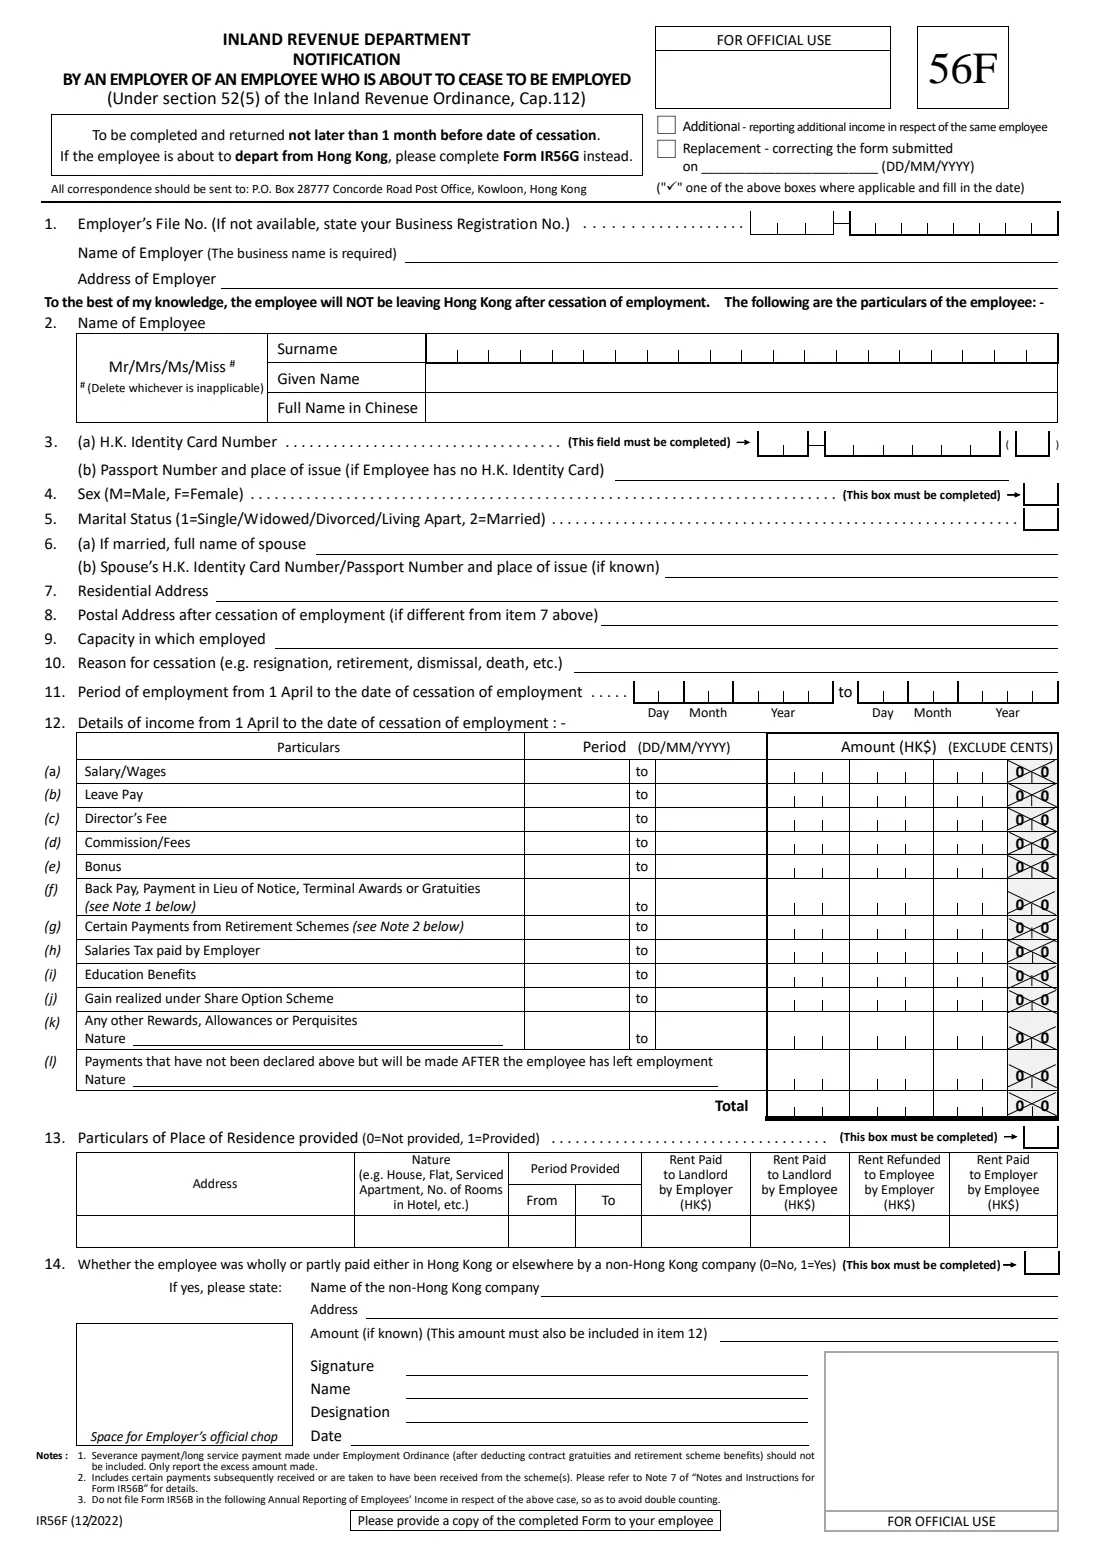
What is Form IR56F?
Form IR56F, 'Notification by an Employer of an Employee who is About to Cease to be Employed', is made under section 52(5) of the Inland Revenue Ordinance. It reports the end of an employment and the employee's income from 1 April of the current year to the date of cessation, so the Inland Revenue Department (IRD) can assess the employee's Salaries Tax. It must be returned not later than 1 month before the date of cessation.
IR56F is for an employee who will remain in Hong Kong. The form itself says that if the employee is about to depart from Hong Kong, you should complete Form IR56G instead, which comes with a duty to withhold money. Because IR56F already reports the year's income, you don't report the same income again on the annual Form IR56B.
FileIt guides you through every item and prints your answers into the IRD's own PDF (the 12/2022 edition). It pre-fills the employee's name and your business details from your vault, checks the HKID check digit and the income periods, right-aligns the amounts in the boxes, adds up the total of items (a) to (l), and files the finished form in the employee's folder. You print it, sign it by hand and post it yourself — FileIt never files anything with the IRD.
- Who fills it
- The employer of an employee whose employment is ending and who is not leaving Hong Kong
- Given to
- The Inland Revenue Department, P.O. Box 28777, Concorde Road Post Office, Kowloon — or through the IRD's Employer's Return e-Filing Services
- When
- Not later than 1 month before the date of cessation
- Signatures
- An original handwritten signature of the proprietor, precedent partner, director, company secretary, manager or other responsible person
- Edition
- IR56F (12/2022), 1 page
- Income period
- From 1 April of the current year to the date of cessation
Who needs to fill out Form IR56F?
- Employers whose employee is resigning, retiring or being dismissed, and who to the best of their knowledge will not be leaving Hong Kong.
- Employers reporting the cessation of employment on the death of an employee.
- Household employers whose domestic staff are moving to another employer in Hong Kong.
- Employers who need to report extra income for someone already covered by an IR56F, using the 'Additional' box.
- Employers correcting an IR56F already submitted, using the 'Replacement' box.
When to use Form IR56F
- As soon as you know the employment will end, and not later than 1 month before the date of cessation.
- If an employee leaves without notice, file as soon as you can. The IRD's FAQ gives the example of an employee who left on 30 April without an IR56B filed for the previous year: you file an IR56B up to 31 March and an IR56F from 1 April to the date of cessation.
- If a payment will be made after the employee has left and the amount can't yet be ascertained, report it once it is made with a revised form.
- If the employee is going to leave Hong Kong after the job ends, use Form IR56G instead of IR56F.
What you need before you start
- Your employer's file number (or business registration number), business name and address.
- The employee's English name as on their HKID card or passport, and their HKID number with check digit — or passport number and place of issue.
- Sex, marital status and, if married, the spouse's name and HKID or passport number (if known).
- The employee's residential address and the postal address they will use after the employment ends.
- Their job title and the reason for cessation, e.g. resignation, retirement, dismissal or death.
- Payroll records from 1 April to the last day: salary, leave pay, director's fees, commission, bonus, back pay or payment in lieu of notice, and other benefits, each with the period it covers.
- Details of any payments still to be made after the employee has left.
- Housing provided and the rents involved, and any amounts paid by a non-Hong Kong company.
What’s on Form IR56F
The 2022 edition has 1 page. FileIt asks for it in 6 parts:
- Type of notificationEmployer
- 1. Particulars of the employerEmployer
- 2–10. Particulars of the employeeEmployer
- 11–12. Period of employment and income from 1 AprilEmployer
- 13–14. Housing and payments by a non-Hong Kong companyEmployer
- SignatureEmployer
How to fill out Form IR56F, step by step
1 Additional / Replacement boxes
Leave both boxes blank for the first notification. Tick 'Additional' only to report extra income left out before for the same employee. Tick 'Replacement' to correct a form already submitted — for any change, including an increase or decrease in the income reported — and give that form's submission date.
2 1. Employer's particulars
Give your employer's file number, or your business registration number if you don't have one, then the employer's name (the business name is required) and address. Just below, the form states that to the best of your knowledge the employee will NOT be leaving Hong Kong after the employment ends.
3 2–5. Name, identity, sex and marital status
Enter the surname in the boxes and the given name on the next line, as on the HKID card or passport, and delete the titles that don't apply (FileIt strikes them out). The Chinese name box is for handwriting — FileIt can't print Chinese characters. Item 3(a), the HKID number, must be completed; give a passport number only if there is no HKID card. Sex is M or F, marital status 1 or 2.
4 6–10. Spouse, addresses, capacity and reason
For a married employee, the spouse's full name and, if known, HKID or passport number. Then the residential address, a postal address after cessation if it is different, the capacity in which the person was employed, and the reason for cessation — resignation, retirement, dismissal, death and so on.
5 11. Period of employment from 1 April
The start date is 1 April of the current year of assessment, or the date the employee joined if later; the end date is the date of cessation. FileIt checks the period stays within one year of assessment, which runs from 1 April to 31 March.
6 12. Details of income
Report each kind of income in whole Hong Kong dollars with the period it relates to: (a) salary or wages, (b) leave pay, (c) director's fee, (d) commission or fees, (e) bonus, (f) back pay, payment in lieu of notice, terminal awards or gratuities, (g) certain payments from retirement schemes, (h) Salaries Tax paid by the employer, (i) education benefits, (j) gains under a share option scheme and (k) any other rewards, allowances or perquisites with their nature. Item (l) is for payments not declared above that will be made after the employee has left.
Report gross income before deductions such as the employee's MPF contributions, and don't include the employer's contributions. Note 1 says a severance or long service payment under the Employment Ordinance (after deducting contract gratuities and retirement scheme benefits) is left out; only any excess is reported. FileIt adds up the total.
7 13. Place of residence provided
Enter 0 if no housing was provided, or 1 with the address, its nature, the period provided and the rent paid to the landlord by the employer or the employee, refunded to the employee, or paid to the employer. If the employer refunds the employee's rent, fill in the rent paid by the employee as well as the refund.
8 14. Payment by a non-Hong Kong company
Answer 0 or 1. If a non-Hong Kong company paid the employee wholly or partly, give its name, address and the amount if known — an amount that must also be included in item 12.
9 Signature
The name, designation and date of the person signing, with space for the employer's chop. The signer must be the proprietor, precedent partner, a company secretary, manager or director, or another responsible person listed in the IRD's completion notes.
Common mistakes to avoid
- Using IR56F for an employee who is leaving Hong Kong — that needs Form IR56G and money must be withheld.
- Filing late: the deadline is 1 month before the date of cessation.
- Reporting income from before 1 April, or for the whole employment, instead of the current year of assessment only.
- Leaving out the period for an amount, or giving a period outside the employment dates.
- Including severance or long service payments that should be left out under Note 1.
- Reporting the same income again on the next annual IR56B.
- Sending a photocopy, fax or scan, or using a name chop — an originally signed form is required.
After you fill it out
Print the form on white plain A4 paper and have the responsible person sign it by hand in blue or black ink. The IRD's completion notes say photocopies, fax copies and scanned copies aren't acceptable, and neither is a name chop, a printed signature or signing on behalf of the named person.
Post it to the Inland Revenue Department at P.O. Box 28777, Concorde Road Post Office, Kowloon, Hong Kong, or report the same information through the IRD's Employer's Return e-Filing Services, and give the employee a copy of the completed form. Note 3 on the form reminds you not to file an IR56B for this case in the next annual return, to avoid double counting.
FileIt keeps the completed PDF in the employee's vault folder. If a payment reported under item (l) is later made, or you find an error, you have the original to hand when you file an additional or replacement form.
Fill out Form IR56F online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 78 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real Inland Revenue Department (IRD), Hong Kong form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start Form IR56F now — it’s freeForm IR56F: frequently asked questions
What is Form IR56F used for?
Form IR56F tells Hong Kong's Inland Revenue Department that an employee is about to cease to be employed, and reports their income from 1 April to the date of cessation. It is for employees who will stay in Hong Kong.
When must IR56F be filed?
Not later than 1 month before the date of cessation, as printed at the top of the form.
What's the difference between IR56F and IR56G?
IR56F is for an employee whose job is ending but who is staying in Hong Kong. IR56G is for an employee who is about to depart from Hong Kong; it also requires the employer to withhold payments to the employee for a period. The IR56F itself says to use IR56G if the employee is leaving Hong Kong.
Do I still need to file IR56B for this employee?
Not for the same income. The form's Note 3 says not to file an IR56B in the following annual return for this case, to avoid double counting.
Can I fill in Form IR56F online with FileIt?
Yes. FileIt guides you through the form, pre-fills details from your People records, checks the HKID check digit and the income periods, adds up the total and produces the IRD's official PDF. Filling forms is available on every FileIt account, including the free plan.
Where do I send IR56F?
Post the signed form to the Inland Revenue Department, P.O. Box 28777, Concorde Road Post Office, Kowloon, Hong Kong, or use the IRD's Employer's Return e-Filing Services. FileIt doesn't send it for you.
Should payment in lieu of notice be reported on IR56F?
Yes. The IRD's FAQ says the employer reports payment in lieu of notice that accrues on or after 1 April 2012 to the employee who is about to cease to be employed. It goes in item 12(f).
Can IR56F be e-signed or faxed?
The paper form must bear an original signature — the IRD doesn't accept photocopies, faxes or scans of IR56 forms. Print the PDF from FileIt and sign it by hand, or use the IRD's e-filing service instead.
Official sources
- Blank form (PDF), published by Inland Revenue Department (IRD), Hong Kong: https://www.ird.gov.hk/eng/pdf/ir56f.pdf
- Official instructions and guidance: https://www.ird.gov.hk/eng/pdf/ir56f_completion_e.pdf
- Edition shown on this page: IR56F (12/2022) (checked 2026-09-26).
FileIt is not affiliated with or endorsed by Inland Revenue Department (IRD), Hong Kong or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-09-26.