What is IHT414 Agricultural Relief?
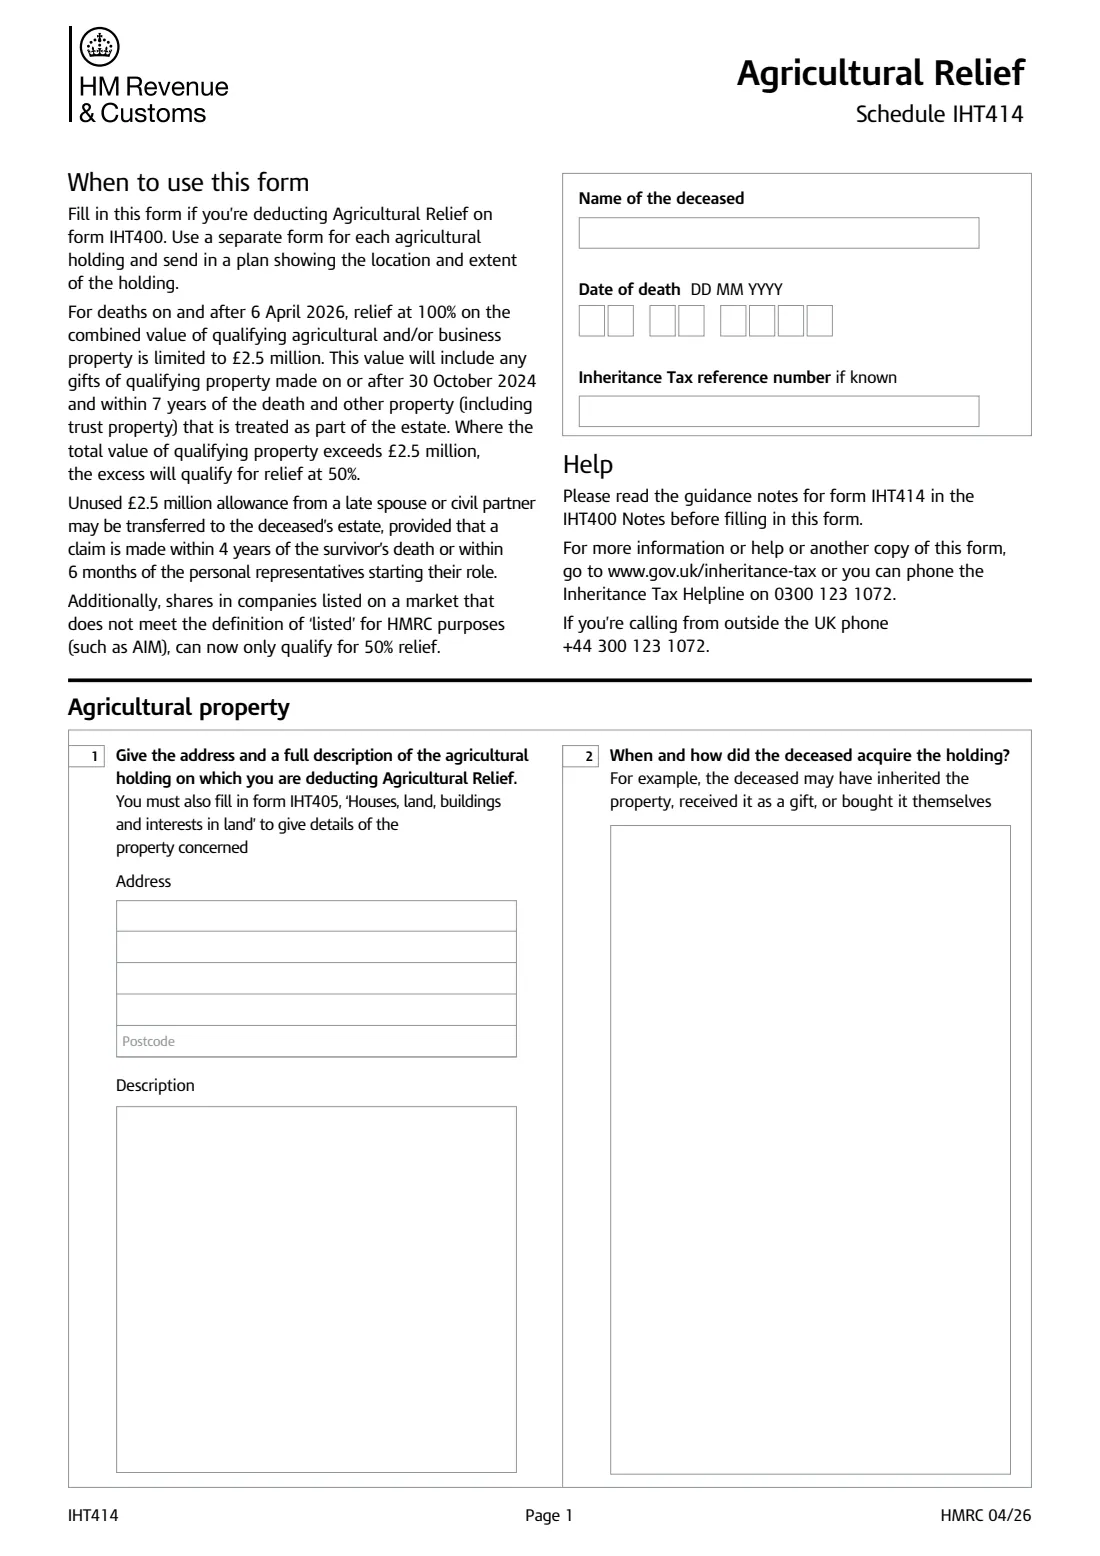
Schedule IHT414 explains to HMRC why a farm or other agricultural property in the estate qualifies for Agricultural Relief. Use a separate form for each agricultural holding, and send a plan showing where it is and how far it extends.
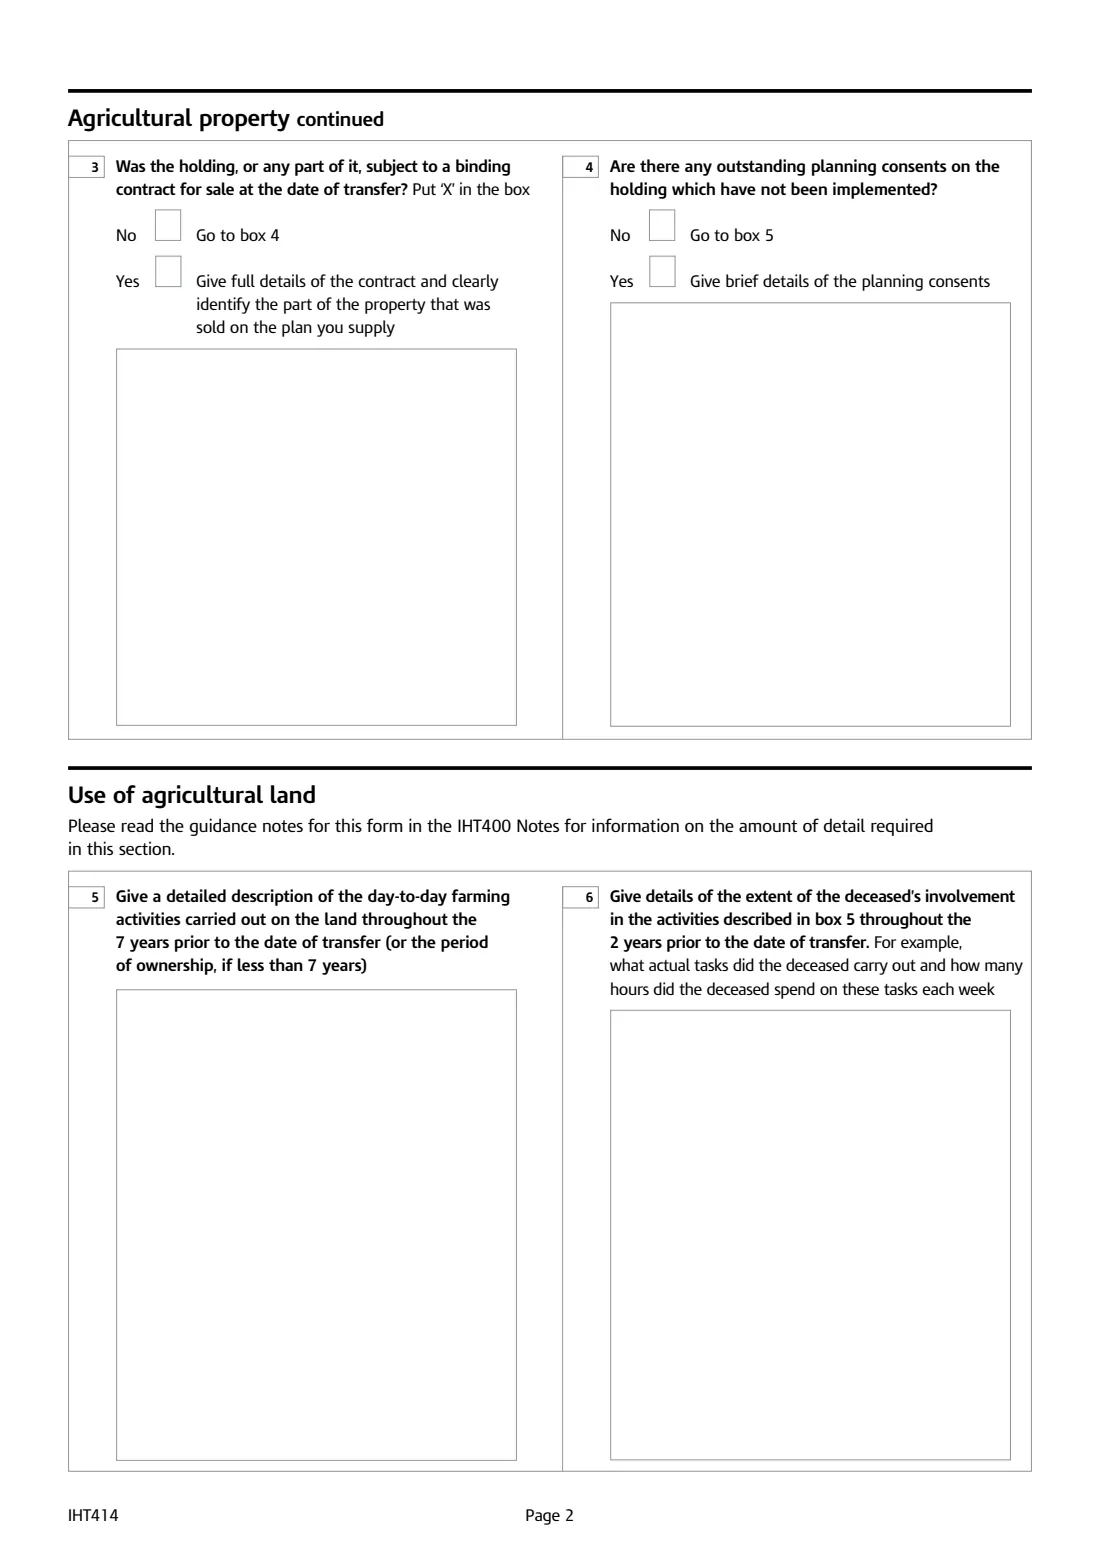
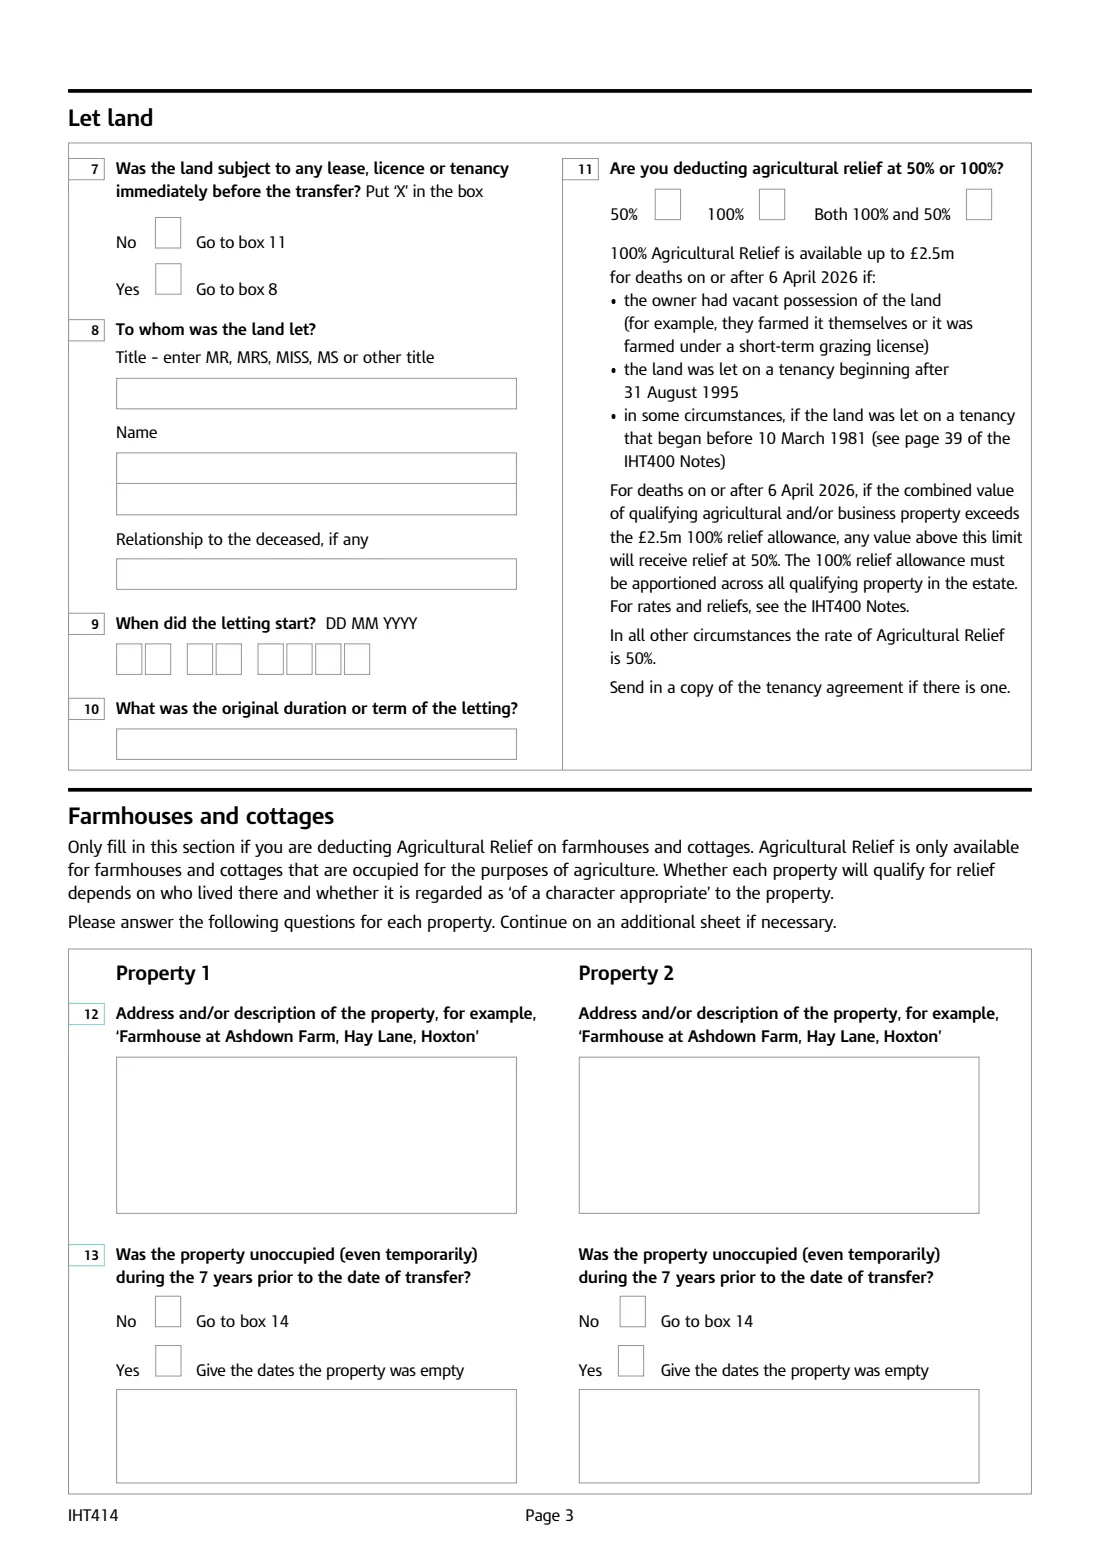
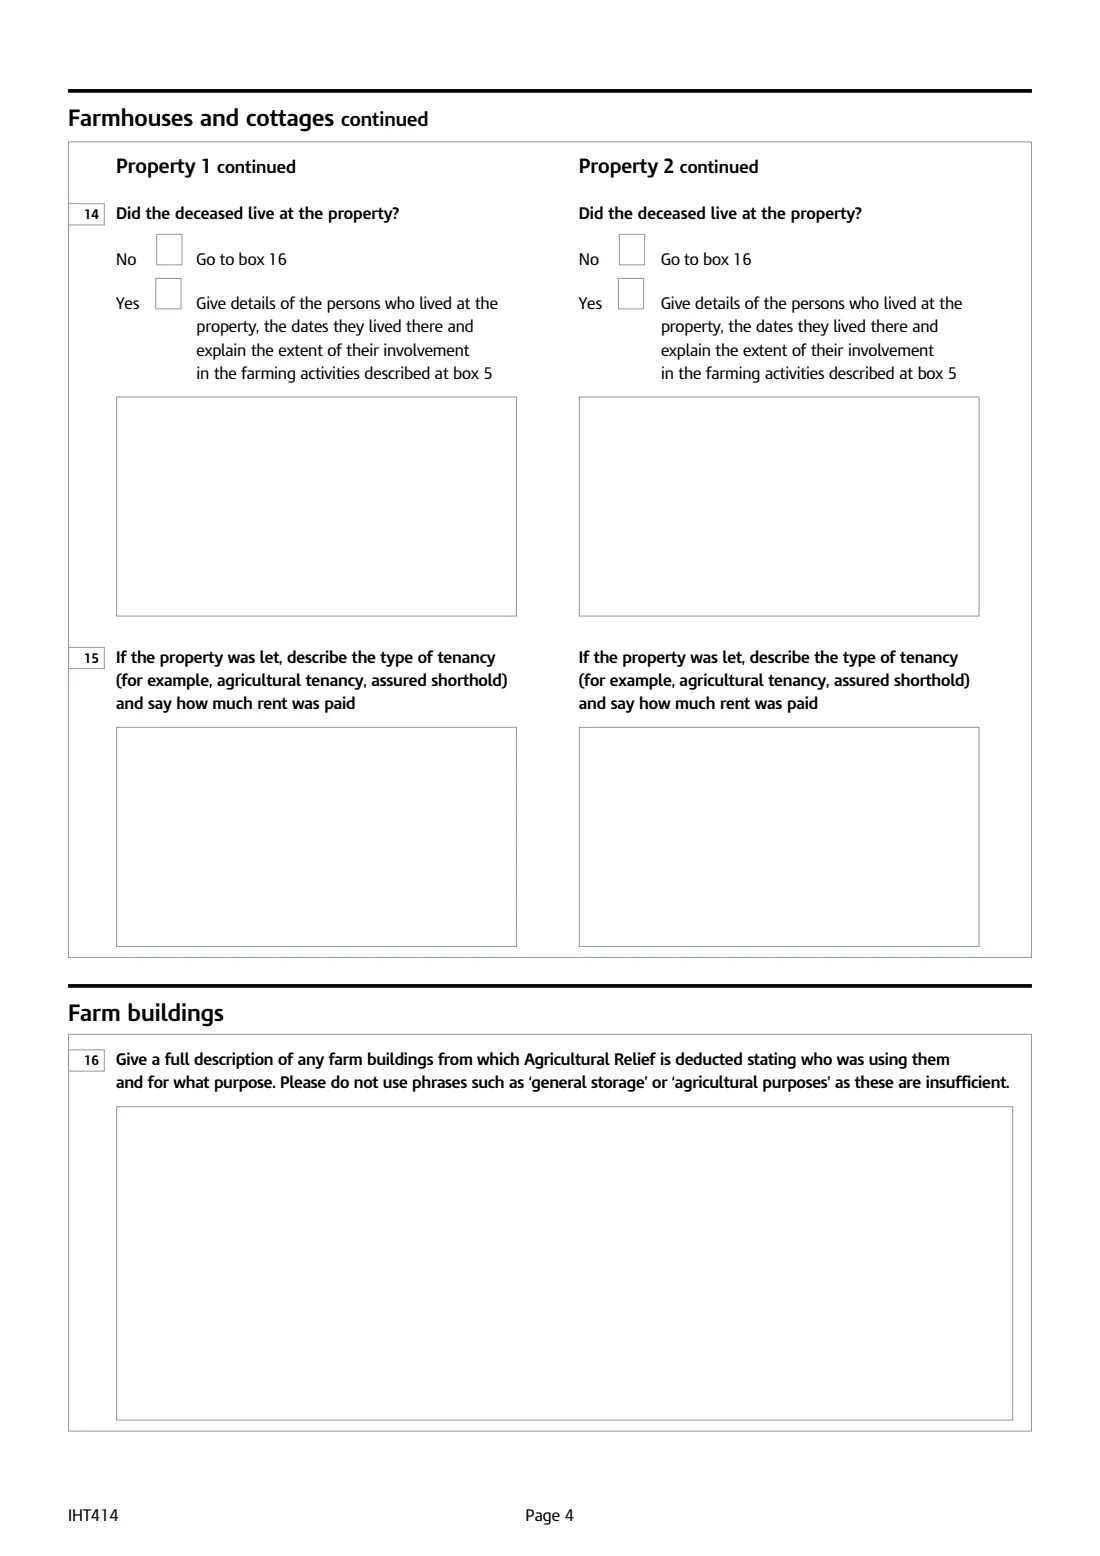
It asks for the holding's address and description and how the deceased acquired it, any contract for sale or unused planning consents, the farming done on the land over 7 years and the deceased's own part in it over 2 years. It also covers any lease, licence or tenancy and the rate of relief, farmhouses and cottages, farm buildings, and the extra conditions for relief on a lifetime gift.
For deaths on and after 6 April 2026, 100% relief on the combined value of qualifying agricultural and business property is limited to £2.5 million, with the excess at 50%. FileIt follows the form's routes and fits your answers into HMRC's boxes on the official IHT414 PDF for you to send with IHT400.
- Who fills it
- The executor or administrator preparing form IHT400
- Part of
- Form IHT400, with IHT405 for the land itself
- One form per
- Agricultural holding
- Send with it
- A plan of the holding, and any tenancy agreement
- Edition
- HMRC 04/26
- Helpline
- Inheritance Tax helpline 0300 123 1072
Who needs to fill out IHT414 Agricultural Relief?
- Executors of farmers and landowners deducting Agricultural Relief on IHT400.
- Estates with let farmland, farm cottages or a farmhouse occupied for agriculture.
- Estates deducting Agricultural Relief on a lifetime gift of agricultural property.
When to use IHT414 Agricultural Relief
- When you're completing the full IHT400 account and deducting Agricultural Relief.
- Alongside IHT405, which gives the details of the houses, land and buildings themselves.
- Fill in a separate IHT414 for each agricultural holding.
What you need before you start
- The deceased's name, date of death and Inheritance Tax reference, if known.
- The holding's address, a full description and a plan, and how and when the deceased acquired it.
- Details of any binding contract for sale and any planning consents not yet implemented.
- A detailed account of the farming over the last 7 years and the deceased's own involvement over the last 2.
- For let land: the tenant, the start date, the term and the tenancy agreement.
- For farmhouses, cottages and farm buildings: who lived in or used them, when, and for what.
What’s on IHT414 Agricultural Relief
The 2026 edition has 5 pages. FileIt asks for it in 9 parts:
- The person who has diedExecutor or administrator
- Agricultural property (1 to 4)Executor or administrator
- Use of agricultural land (5 and 6)Executor or administrator
- Let land (7 to 11)Executor or administrator
- Farmhouses and cottages: property 1 (12 to 15)Executor or administrator
- Farmhouses and cottages: property 2 (12 to 15)Executor or administrator
- Farm buildings (16)Executor or administrator
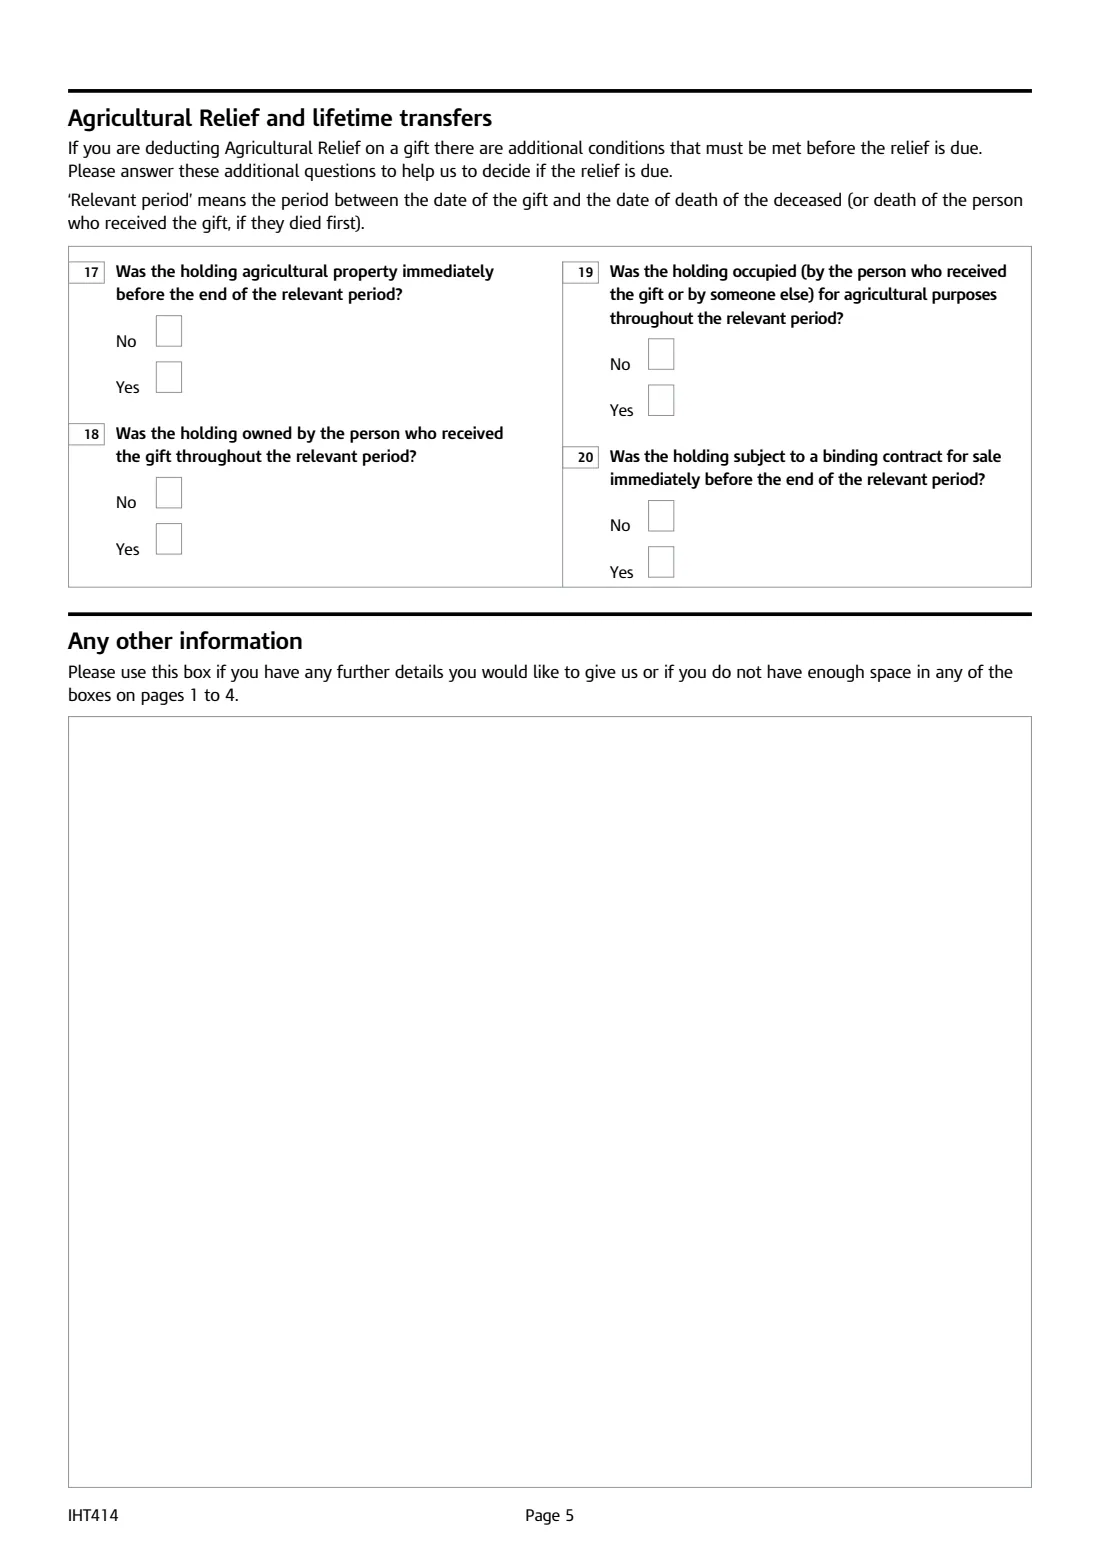
- Agricultural Relief and lifetime transfers (17 to 20)Executor or administrator
- Any other informationExecutor or administrator
How to fill out IHT414 Agricultural Relief, step by step
1 The holding (1 to 4)
Address and description, how the deceased acquired it, any binding contract for sale and any outstanding planning consents.
2 Use of the land (5 and 6)
The day-to-day farming over the 7 years before the transfer, and what the deceased did personally in the last 2 years, such as the tasks and hours each week.
3 Let land (7 to 11)
Any lease, licence or tenancy: to whom, when it started and its term. Then the rate of relief: 50%, 100% or both.
4 Farmhouses and cottages (12 to 15)
For up to two properties: the description, any time it was empty, whether the deceased lived there and who did, and any tenancy and rent.
5 Farm buildings and lifetime gifts (16 to 20)
Who used each farm building and for what. The questions on lifetime gifts are only for relief on a gift.
Common mistakes to avoid
- Describing farm buildings as 'general storage' or 'agricultural purposes': HMRC says these are insufficient.
- Forgetting the plan showing the location and extent of the holding.
- Putting several holdings on one form instead of one form for each.
- Claiming 100% relief on let land where the tenancy doesn't qualify for it.
- Leaving out the deceased's own involvement in the farming in the last 2 years.
After you fill it out
Check the preview, download the PDF and attach the plan and any tenancy agreement.
Send IHT414 with IHT405 and the rest of the IHT400 account. FileIt doesn't send anything to HMRC.
Keep the plan, the tenancy papers and the schedule in the deceased's FileIt folder.
Fill out IHT414 Agricultural Relief online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 43 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real HMRC form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start IHT414 Agricultural Relief now — it’s freeIHT414 Agricultural Relief: frequently asked questions
When is Agricultural Relief at 100%?
The form lists when 100% relief (up to £2.5 million for deaths on or after 6 April 2026) is available: the owner had vacant possession, for example they farmed it themselves or it was farmed under a short-term grazing licence; the land was let on a tenancy beginning after 31 August 1995; or in some circumstances it was let on a tenancy that began before 10 March 1981. Otherwise the rate is 50%.
What is the £2.5 million limit?
For deaths on and after 6 April 2026, relief at 100% on the combined value of qualifying agricultural and business property is limited to £2.5 million, including qualifying gifts made on or after 30 October 2024 and within 7 years of the death. The excess qualifies for 50% relief.
Does a farmhouse qualify?
Only if it is occupied for the purposes of agriculture. The form says whether each property qualifies depends on who lived there and whether it is 'of a character appropriate' to the property.
What does 'relevant period' mean for a gift?
The period between the date of the gift and the date of death of the deceased, or of the person who received the gift if they died first.
Who signs IHT414?
Nobody signs the schedule itself. The declaration on IHT400 covers all the schedules sent with it.
Official sources
- Blank form (PDF), published by HMRC: https://assets.publishing.service.gov.uk/media/69c5114d23fcbcd838a6f71c/IHT414_Fillable.pdf
- Official instructions and guidance: https://www.gov.uk/government/publications/inheritance-tax-agricultural-relief-iht414
- Edition shown on this page: HMRC 04/26 (checked 2026-10-25).
FileIt is not affiliated with or endorsed by HMRC or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-10-25.