What is IHT413 business interests?
If the deceased ran a business, was a partner in a firm, or owned assets used by a company they controlled or a partnership they were in, the IHT400 account needs schedule IHT413, and Business Relief is deducted through it. Control holdings of shares go on IHT412 instead.
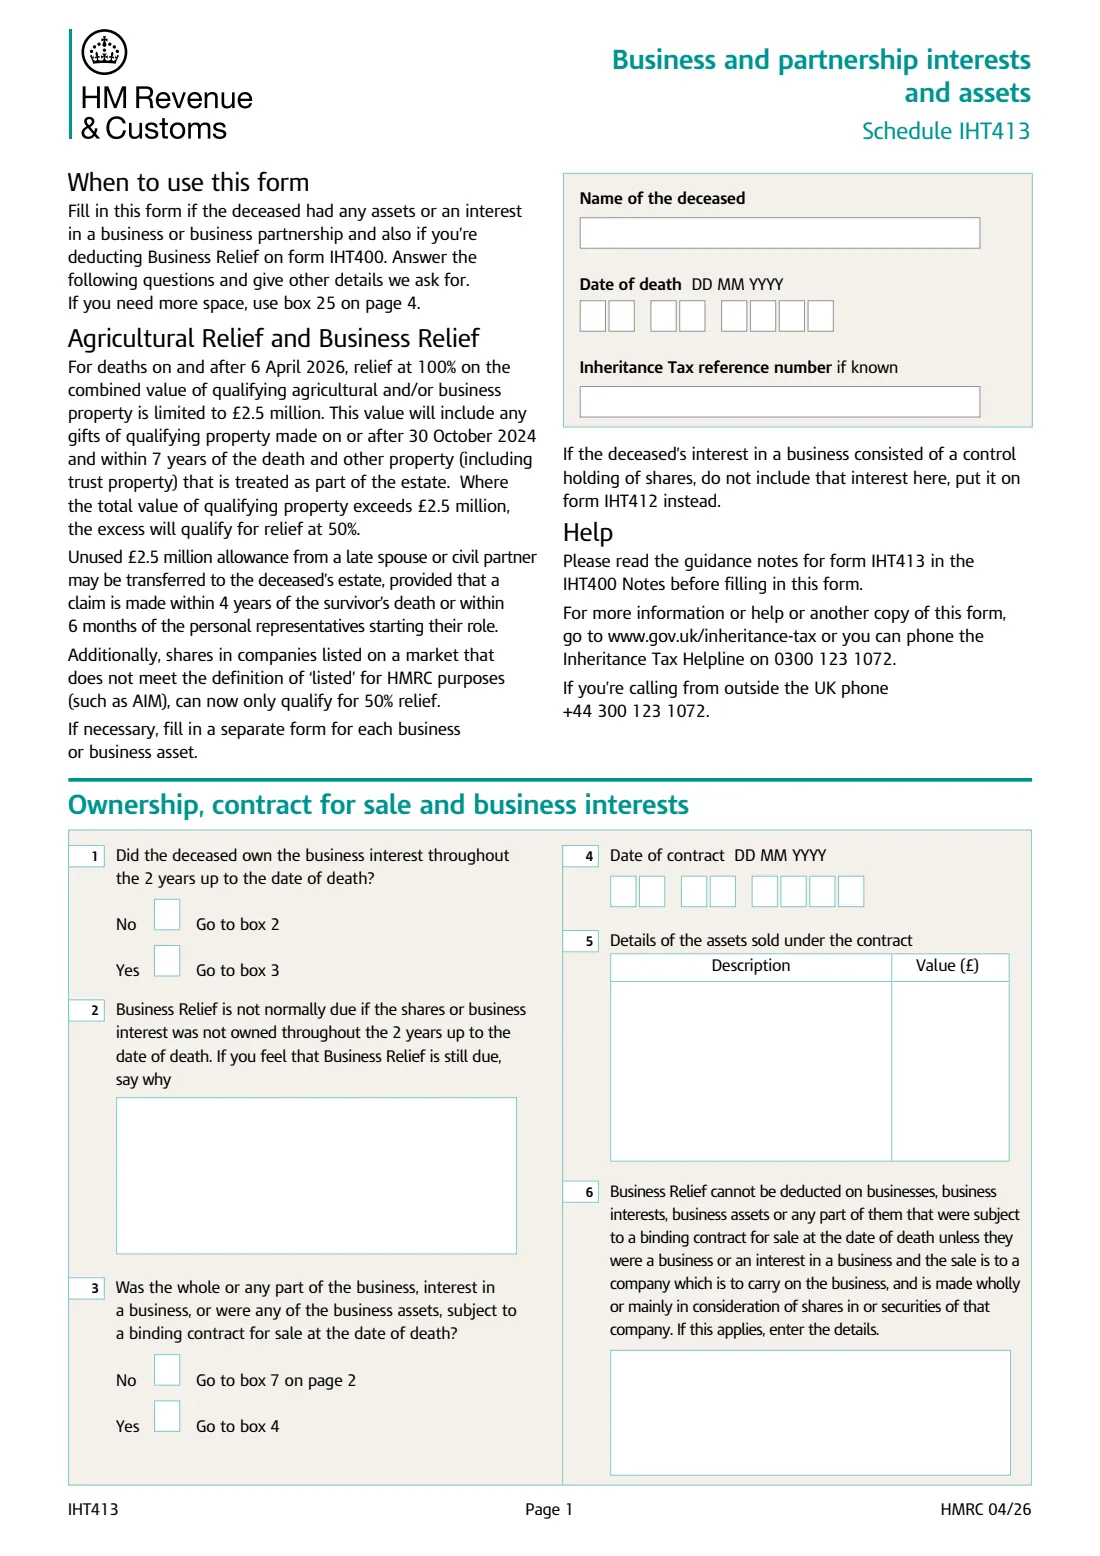
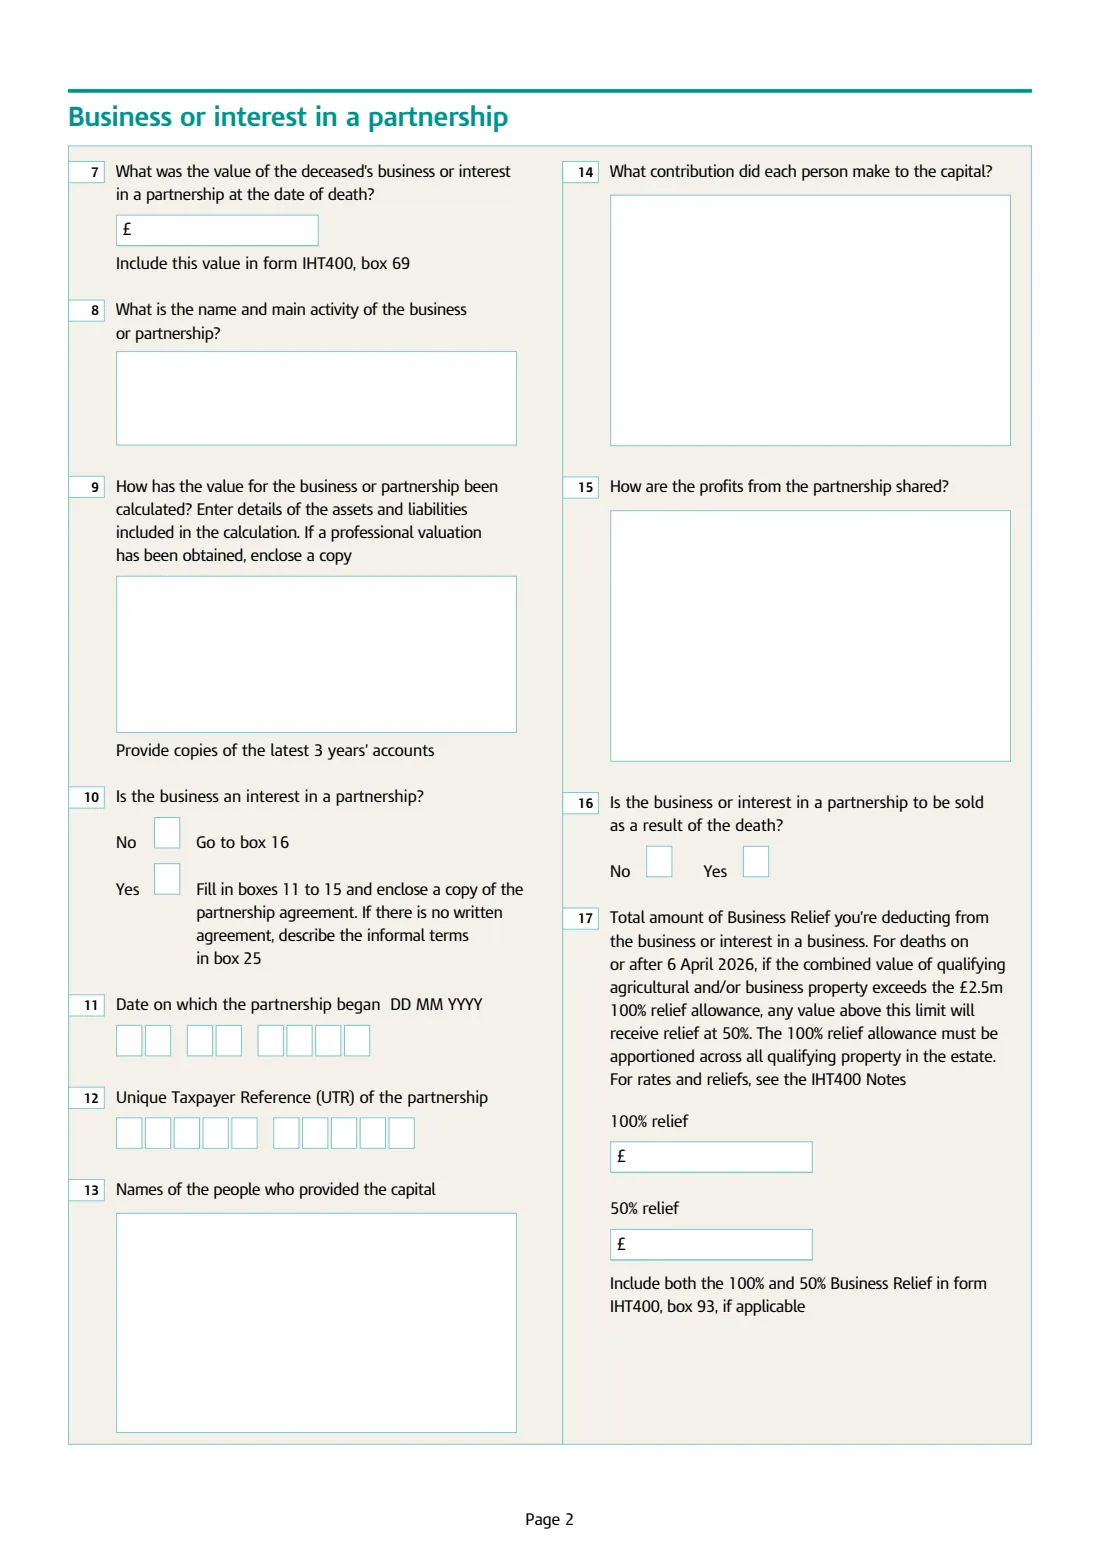
The form asks whether the business was owned for 2 years and whether any of it was under a binding contract for sale. It then asks the value of the business or partnership interest, how it was worked out, the partnership's details, and the Business Relief at 100% and 50%. Further parts cover assets used by a company or partnership, and relief on lifetime gifts.
For deaths on and after 6 April 2026, 100% relief on the combined value of qualifying agricultural and business property is limited to £2.5 million, with the excess at 50%. FileIt follows the form's 'go to box' routes, checks the relief against the values and prints HMRC's official IHT413 PDF for you to send with IHT400.
- Who fills it
- The executor or administrator preparing form IHT400
- Part of
- Form IHT400, the Inheritance Tax account
- Values go to
- IHT400 box 69 (value) and box 93 (Business Relief)
- One form per
- Business or business asset, if necessary
- Edition
- HMRC 04/26
- Helpline
- Inheritance Tax helpline 0300 123 1072
Who needs to fill out IHT413 business interests?
- Executors of a sole trader or a partner in a business partnership.
- Estates with land, buildings or machinery the deceased owned that a company they controlled, or their partnership, used.
- Estates deducting Business Relief on a business interest, or on a lifetime gift of one.
When to use IHT413 business interests
- When you're completing the full IHT400 account and deducting Business Relief on a business or partnership interest.
- Once you have the business accounts and a valuation at the date of death.
- Fill in a separate form for each business or business asset if necessary.
What you need before you start
- The deceased's name, date of death and Inheritance Tax reference, if known.
- When the deceased acquired the business, and details of any contract for sale at the date of death.
- The value of the business or partnership interest and how it was calculated, with the latest 3 years' accounts and any professional valuation.
- For a partnership: the date it began, its UTR, who provided the capital and how profits are shared, with the partnership agreement.
- The Business Relief you're claiming at 100% and 50%.
What’s on IHT413 business interests
The 2026 edition has 4 pages. FileIt asks for it in 6 parts:
- The person who has diedExecutor or administrator
- Ownership, contract for sale and business interests (1 to 6)Executor or administrator
- Business or interest in a partnership (7 to 17)Executor or administrator
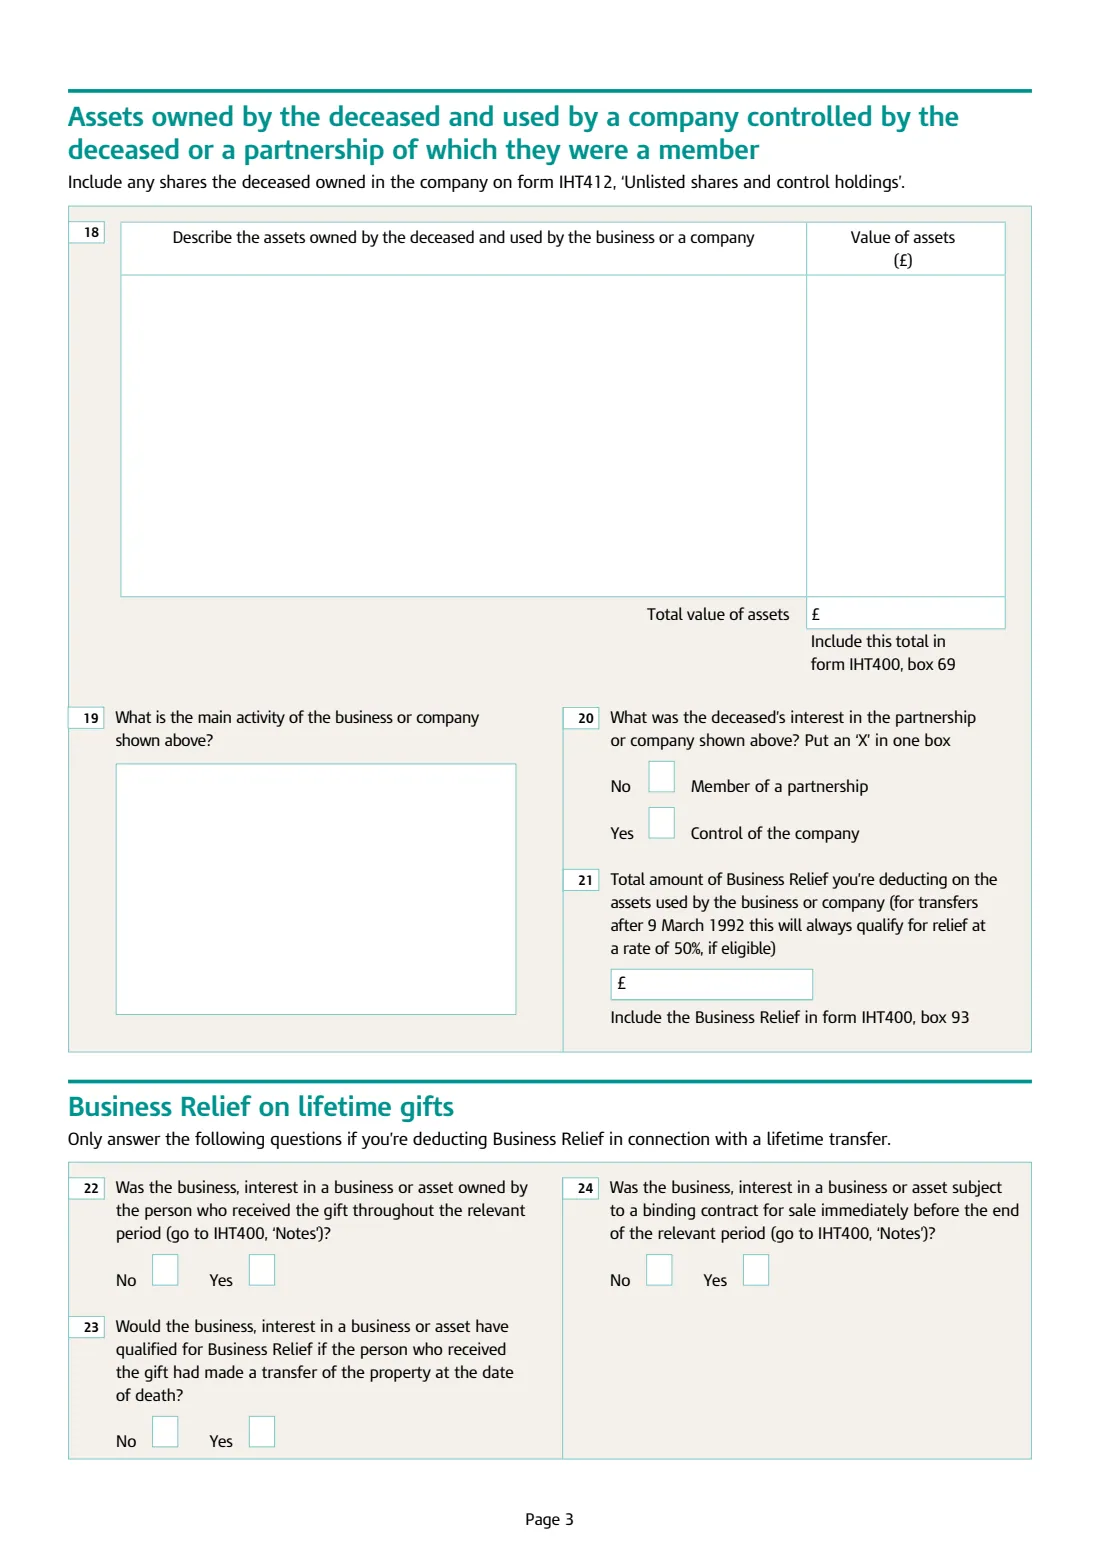
- Assets used by a company the deceased controlled, or a partnership they were a member of (18 to 21)Executor or administrator
- Business Relief on lifetime gifts (22 to 24)Executor or administrator
- Additional information (25)Executor or administrator
How to fill out IHT413 business interests, step by step
1 Ownership and contracts (1 to 6)
Whether the deceased owned the business for 2 years, and if not why relief is still due. Whether any of it was under a binding contract for sale, with the date, the assets and any sale to a company for shares.
2 The business or partnership (7 to 17)
Its value for IHT400 box 69, name and main activity, how the value was worked out, partnership details, whether it's to be sold because of the death, and the Business Relief at 100% and 50% for IHT400 box 93.
3 Assets used by a company or partnership (18 to 21)
Assets the deceased owned that a company they controlled, or their partnership, used. FileIt totals their value. Relief on these is at 50%.
4 Lifetime gifts (22 to 24)
Only if you're deducting Business Relief on a lifetime transfer: ownership by the person who received it, and any contract for sale.
5 Additional information (25)
Anything that didn't fit, such as the informal terms of a partnership with no written agreement.
Common mistakes to avoid
- Putting a control holding of shares on IHT413 instead of IHT412.
- Claiming Business Relief on a business under a binding contract for sale at the date of death, unless it's sold to a company carrying on the business for shares.
- Not sending the latest 3 years' accounts and the partnership agreement.
- Claiming more than 100% relief on the first £2.5 million of combined qualifying property for a death on or after 6 April 2026.
- Claiming 100% relief on assets used by a company or partnership: for transfers after 9 March 1992 the form says that's always 50%.
After you fill it out
Check the preview, download the PDF and attach the accounts, valuation and partnership agreement.
Copy the value to IHT400 box 69 and the Business Relief to box 93, and send IHT413 with the IHT400 account. FileIt doesn't send anything to HMRC.
Keep the business papers and the schedule in the deceased's FileIt folder.
Fill out IHT413 business interests online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 40 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real HMRC form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start IHT413 business interests now — it’s freeIHT413 business interests: frequently asked questions
What is Business Relief?
A relief from Inheritance Tax on qualifying business property, such as a business or an interest in one. For deaths on and after 6 April 2026, relief at 100% on the combined value of qualifying agricultural and business property is limited to £2.5 million, and the excess qualifies at 50%.
What if the deceased hadn't owned the business for 2 years?
The form says Business Relief isn't normally due, but you can explain in box 2 why you think it still is.
Is the £2.5 million allowance per business?
No. It applies to the combined value of qualifying agricultural and business property, and the form says it must be apportioned across all qualifying property in the estate.
Does a partnership need a written agreement?
If there's no written partnership agreement, describe the informal terms in box 25.
Who signs IHT413?
Nobody signs the schedule itself. The declaration on IHT400 covers all the schedules sent with it.
Official sources
- Blank form (PDF), published by HMRC: https://assets.publishing.service.gov.uk/media/69cd1ae4eafd66b876458baa/IHT413_Fillable.pdf
- Official instructions and guidance: https://www.gov.uk/government/publications/inheritance-tax-business-and-partnership-interests-and-assets-iht413
- Edition shown on this page: HMRC 04/26 (checked 2026-10-25).
FileIt is not affiliated with or endorsed by HMRC or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-10-25.