What is Form T1255?
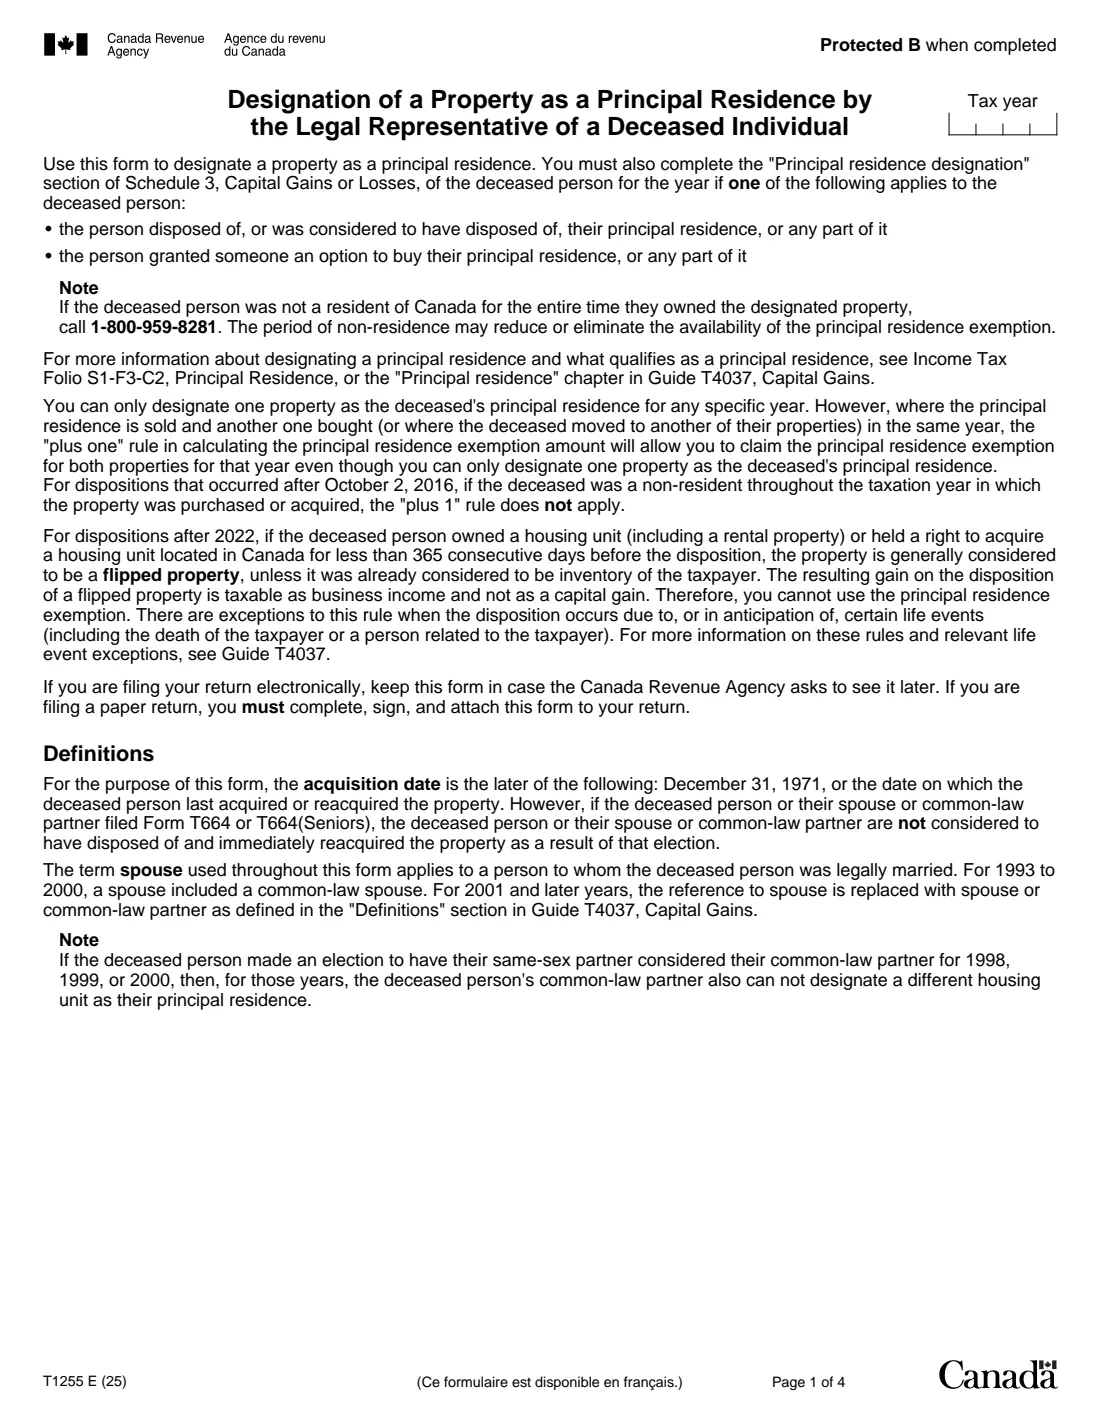
When someone dies, they are generally treated as having disposed of their property, their home included, and any gain belongs on their final return. The principal residence exemption can shelter all or part of the gain on the home, but someone has to designate it. Form T1255 is the legal representative's version of Form T2091(IND): you designate the property as the deceased's principal residence for the years that qualify, and work out what gain, if any, is left.
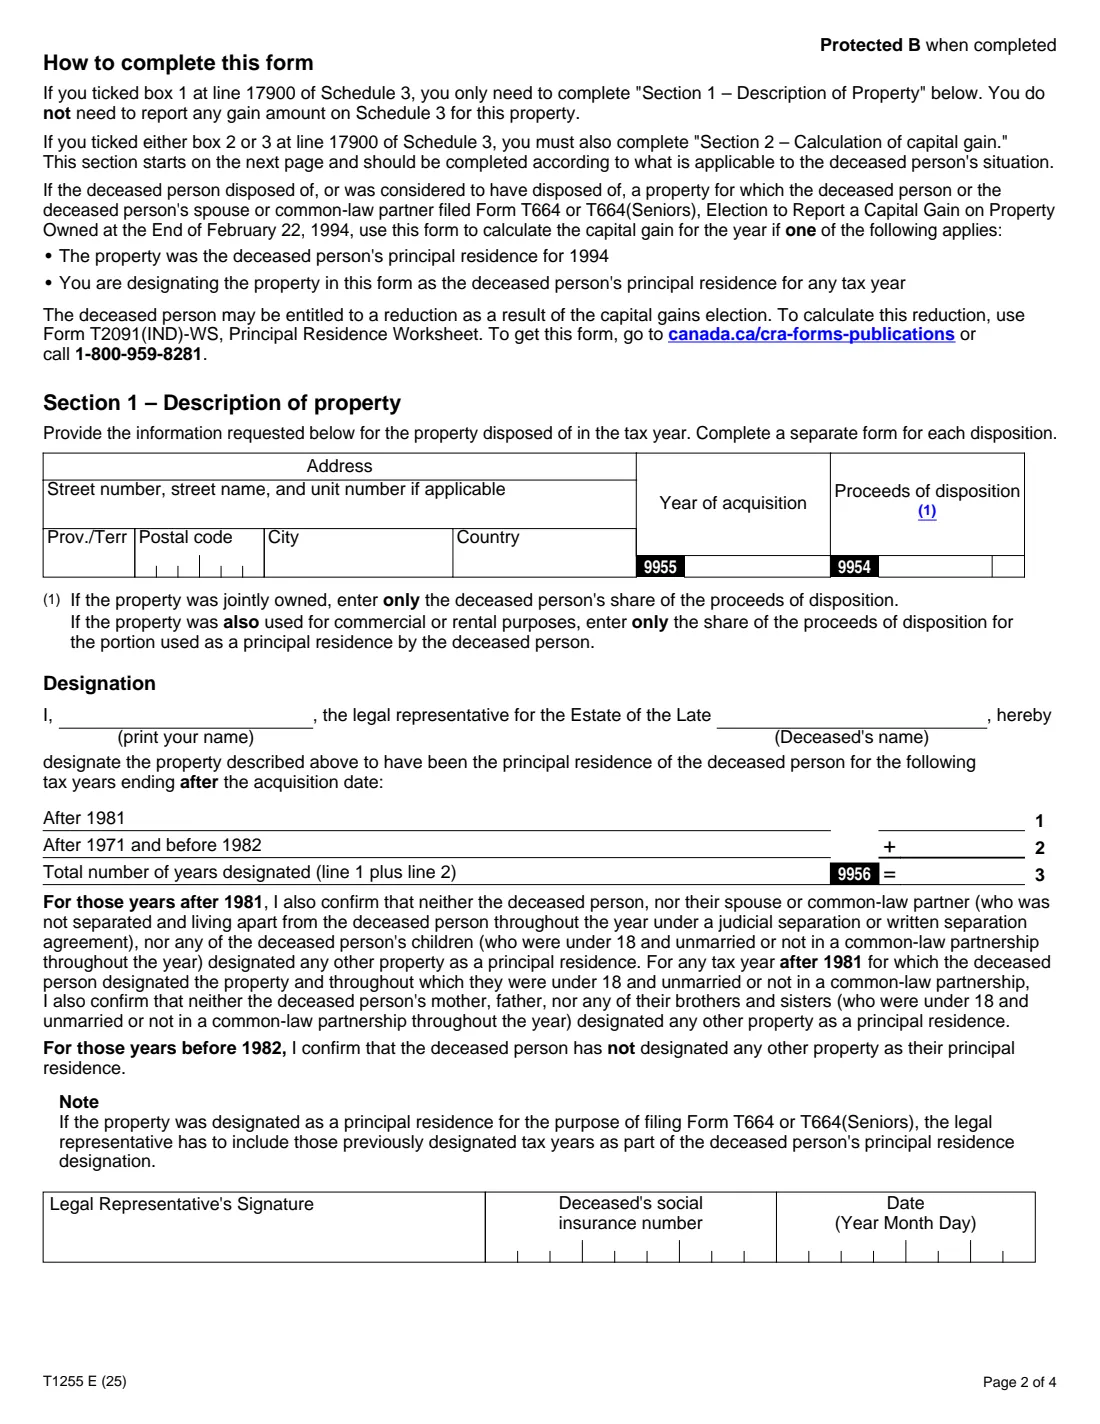
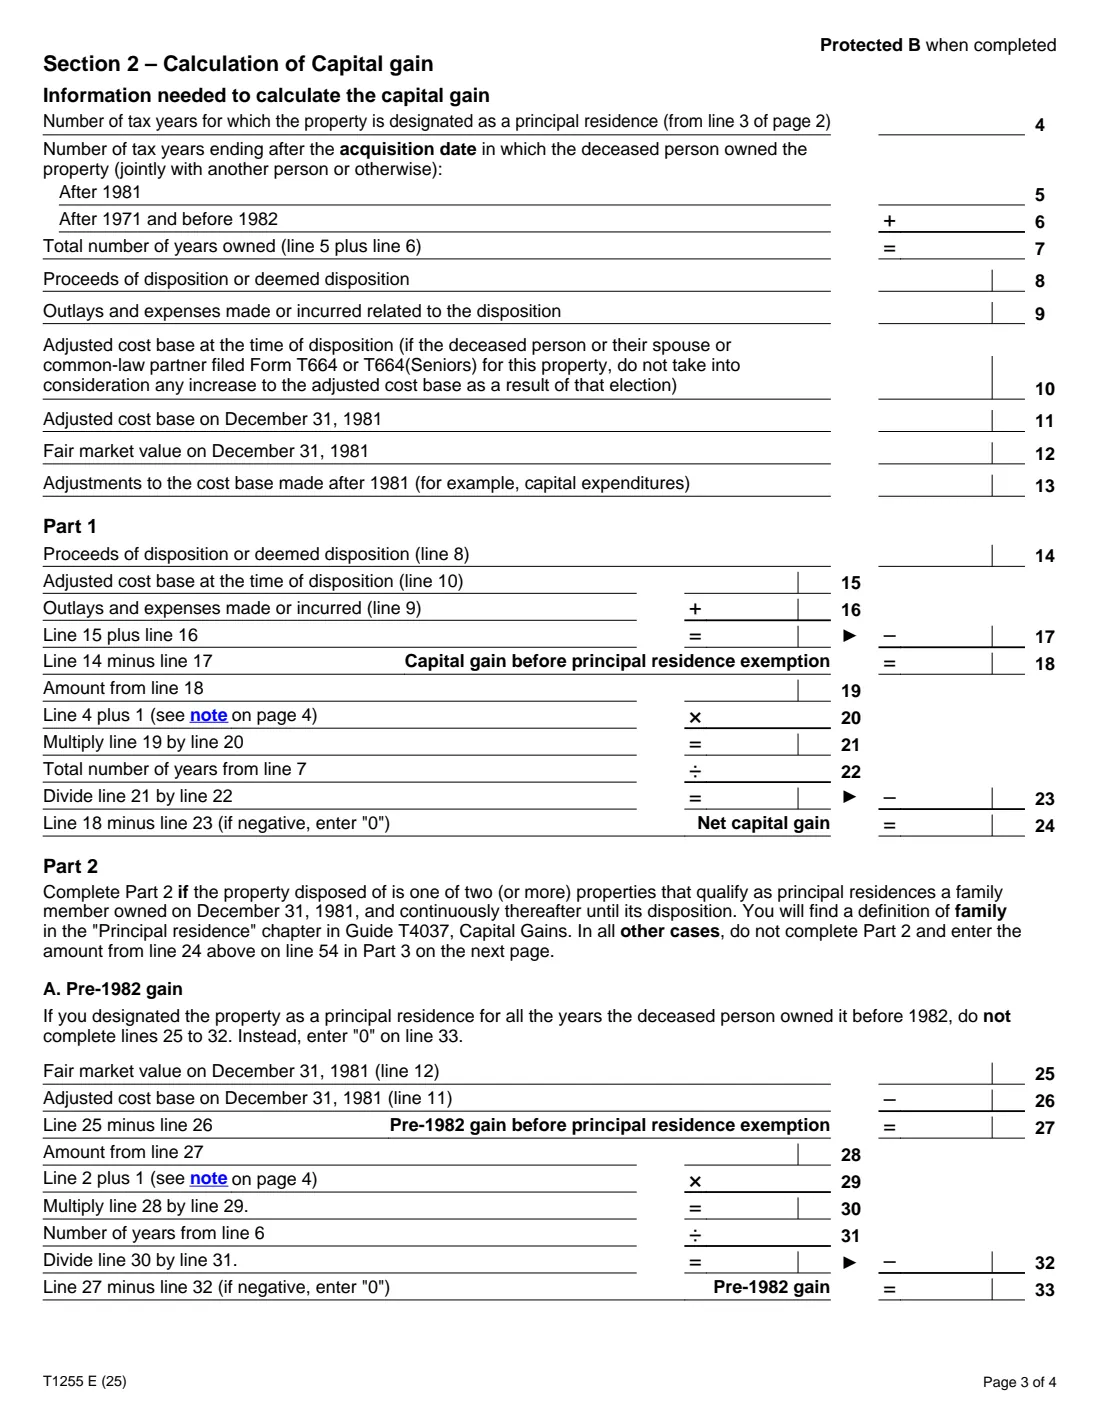
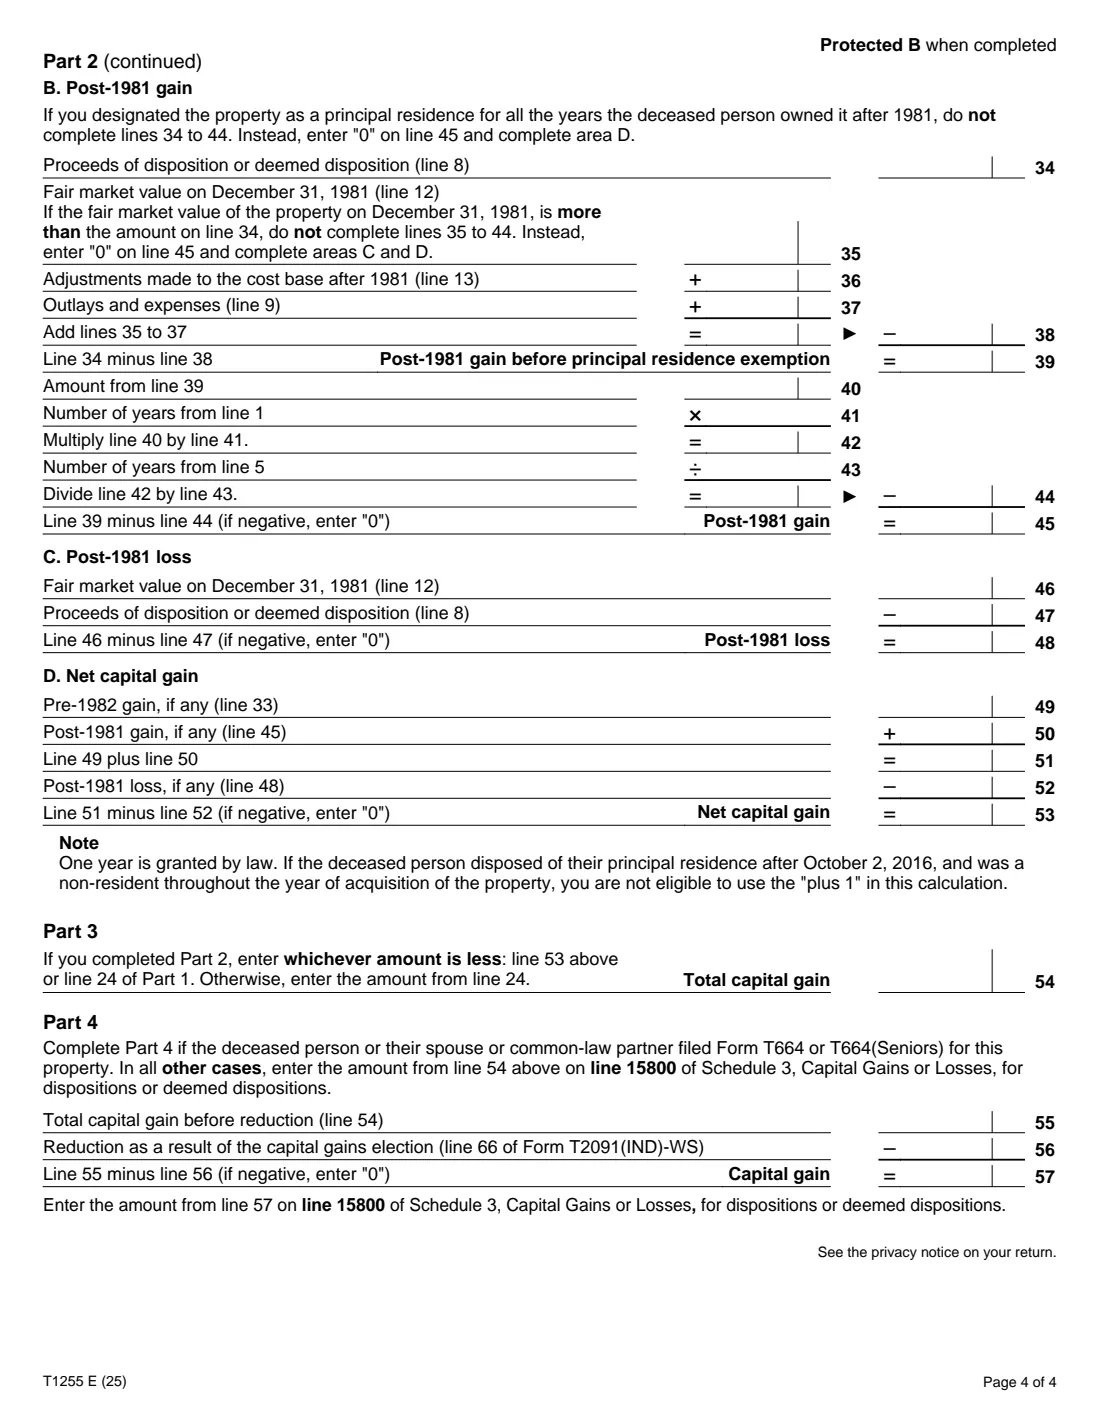
Section 1 describes the property, its year of acquisition and the proceeds, and records the designation: how many tax years after 1981 and from 1972 to 1981 you designate. If you ticked box 1 at line 17900 of the deceased's Schedule 3, that's all. With box 2 or 3, Section 2 calculates the capital gain: the exempt share is the gain times the years designated plus one, divided by the years owned, with extra parts for homes owned at the end of 1981 and for properties covered by a 1994 capital gains election (Form T664).
FileIt asks for the property details, years and amounts, and fills in all 57 lines of the CRA's own PDF (edition T1255 E (25)), with dollars and cents in their columns. The finished form is saved in the deceased person's vault folder. You sign it and attach it to the return, or keep it if you file electronically; FileIt doesn't file it.
- Who fills it
- The legal representative (executor, administrator or liquidator) of the deceased
- Sent to
- Attached to the deceased's paper return; kept on file with an electronic return
- When
- For the tax year of the disposition, usually the final return; one form per disposition
- Signatures
- The legal representative's, by hand, with the date
- Edition
- T1255 E (25)
Who needs to fill out Form T1255?
- Executors and administrators handling a home the deceased owned at death.
- Legal representatives where the deceased sold a home, or granted an option on one, in their final year.
- Estates of people who filed Form T664 or T664(Seniors) for the property in 1994.
When to use Form T1255
- When preparing the deceased's return for the year of the disposition, alongside the principal residence designation on Schedule 3.
- Once for each property disposed of in that year.
- Before deciding which property to designate for overlapping years, since only one can be the principal residence for any year.
What you need before you start
- The property's address, the year the deceased acquired it and the proceeds (the deceased's share, and only the residence part if it was also rented out or used for business).
- The number of years designated after 1981 and from 1972 to 1981, and the years the deceased owned it.
- The deceased's SIN and which box was ticked at line 17900 of Schedule 3.
- For Section 2: selling expenses, the adjusted cost base, and the cost and value on December 31, 1981 if the deceased owned it then.
- Any reduction from Form T2091(IND)-WS if a 1994 capital gains election was made.
What’s on Form T1255
The 2025 edition has 4 pages. FileIt asks for it in 7 parts:
- Section 1 – Description of propertyEmployee
- DesignationEmployee
- Section 2 – Information needed to calculate the capital gainEmployee
- Section 2, Part 1 – Net capital gainEmployee
- Section 2, Part 2 – Property owned on December 31, 1981Employee
- Section 2, Part 3 – Total capital gainEmployee
- Section 2, Part 4 – Capital gains election (Form T664)Employee
How to fill out Form T1255, step by step
1 Section 1 – Description of property
The address, year of acquisition (line 9955) and proceeds of disposition (line 9954). If the home was owned jointly, enter only the deceased's share.
2 Designation
Your name, the deceased's name, and the number of tax years you designate after 1981 and before 1982. Line 3 adds them. Sign as the legal representative and enter the deceased's SIN and the date.
3 Section 2, Part 1 – Net capital gain
With box 2 or 3 at line 17900: the years owned, selling costs and adjusted cost base. FileIt works out the gain, the exempt part using the years designated plus one, and the net gain on line 24. The plus-one year doesn't apply if the deceased was a non-resident throughout the year of acquisition and the sale was after October 2, 2016.
4 Parts 2 to 4
Part 2 (optional) applies when a family member owned two or more qualifying homes on December 31, 1981 and kept them; it splits the gain into pre-1982 and post-1981 parts. Part 3 gives the total gain, and Part 4 subtracts any T664 election reduction. The result goes on line 15800 of Schedule 3.
Common mistakes to avoid
- Designating the same years on two properties: only one home can be the deceased's principal residence for a year.
- Leaving out years already designated for Form T664 or T664(Seniors), which have to be included.
- Reporting the full proceeds of a jointly owned home instead of the deceased's share.
- Missing the flipped-property rule for homes owned less than 365 consecutive days, which has life-event exceptions including death.
- Not calling the CRA when the deceased wasn't resident in Canada for the whole time they owned the home.
After you fill it out
Print the PDF from the deceased's FileIt vault folder and sign it. With a paper return, attach it to the deceased's return; with an electronic return, keep it in case the CRA asks. FileIt doesn't file it for you.
Carry line 54 (or line 57 with Part 4) to line 15800 of the deceased's Schedule 3, and complete the principal residence designation section there. Keep the valuations and the estate papers together in the vault.
Fill out Form T1255 online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 78 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real Canada Revenue Agency (CRA) form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start Form T1255 now — it’s freeForm T1255: frequently asked questions
What's the difference between T1255 and T2091(IND)?
They work the same way. T2091(IND) is for an individual designating their own home; T1255 is for the legal representative designating a deceased person's home.
Do I always need Section 2?
No. If you ticked box 1 at line 17900 of Schedule 3, only Section 1 is needed and no gain is reported for this property.
What is the plus-one rule?
One extra year is added to the years designated when working out the exempt part, so a home sold and replaced in the same year can be fully covered. The form explains when it doesn't apply.
Where do I get T2091(IND)-WS?
The form points to canada.ca/cra-forms-publications or 1-800-959-8281 for the worksheet, which works out the reduction for a capital gains election.
Official sources
- Blank form (PDF), published by Canada Revenue Agency (CRA): https://www.canada.ca/content/dam/cra-arc/formspubs/pbg/t1255/t1255-fill-25e.pdf
- Official instructions and guidance: https://www.canada.ca/en/revenue-agency/services/forms-publications/forms/t1255.html
- Edition shown on this page: T1255 E (25) (checked 2026-10-19).
FileIt is not affiliated with or endorsed by Canada Revenue Agency (CRA) or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-10-19.