What is IHT217 unused nil rate band (excepted estates)?
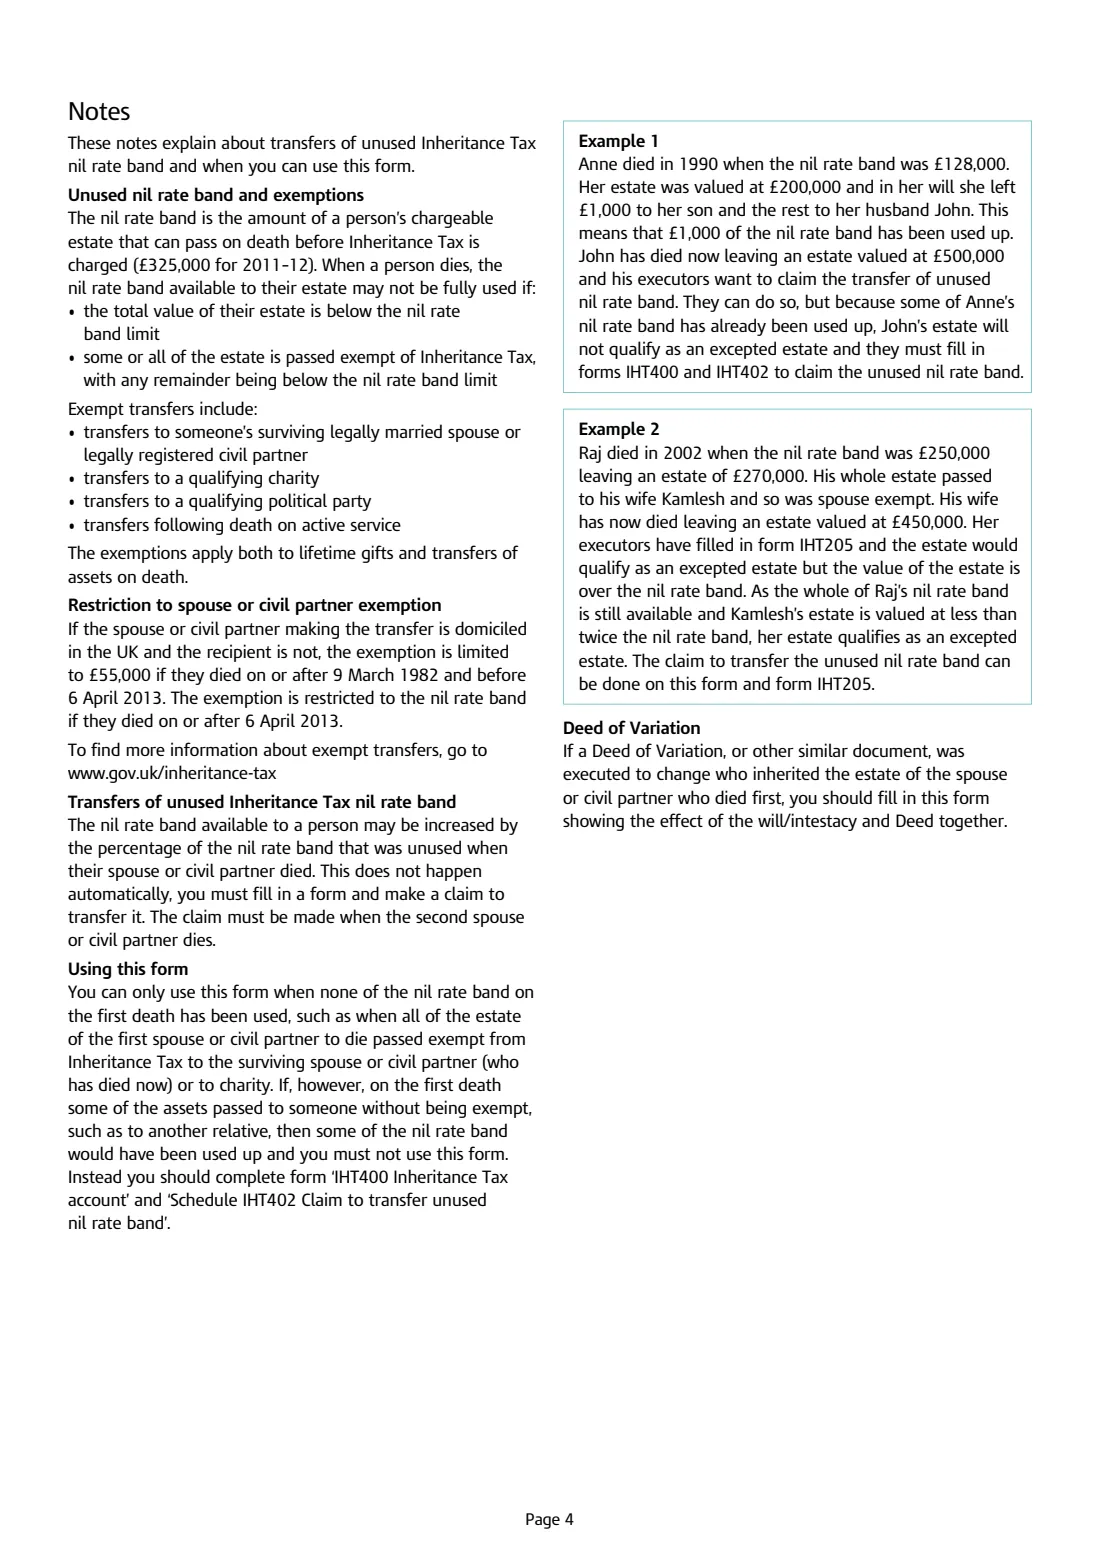
When a husband, wife or civil partner dies and leaves everything to the survivor, their Inheritance Tax nil rate band usually goes unused. On the survivor's death, that unused band can be added to their own. For a straightforward estate reported as an excepted estate on form IHT205 (C5(2006) in Scotland), HMRC's IHT217 is the short way to make that claim, as long as 100% of the first nil rate band is unused.
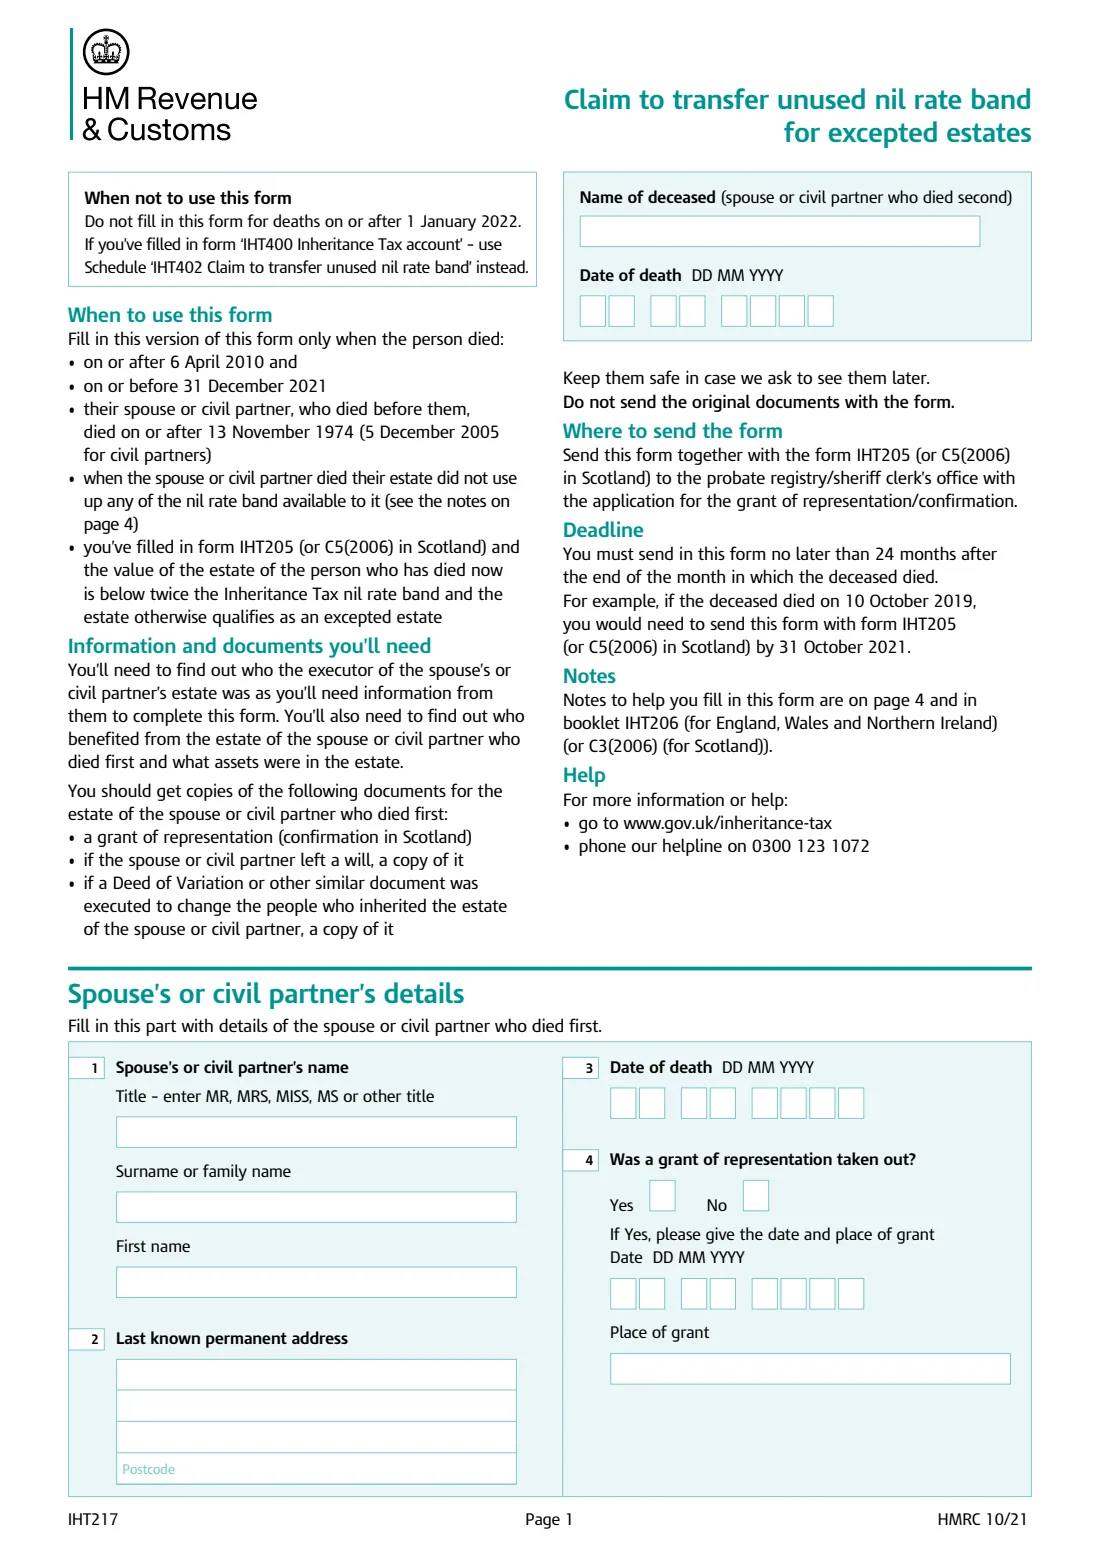
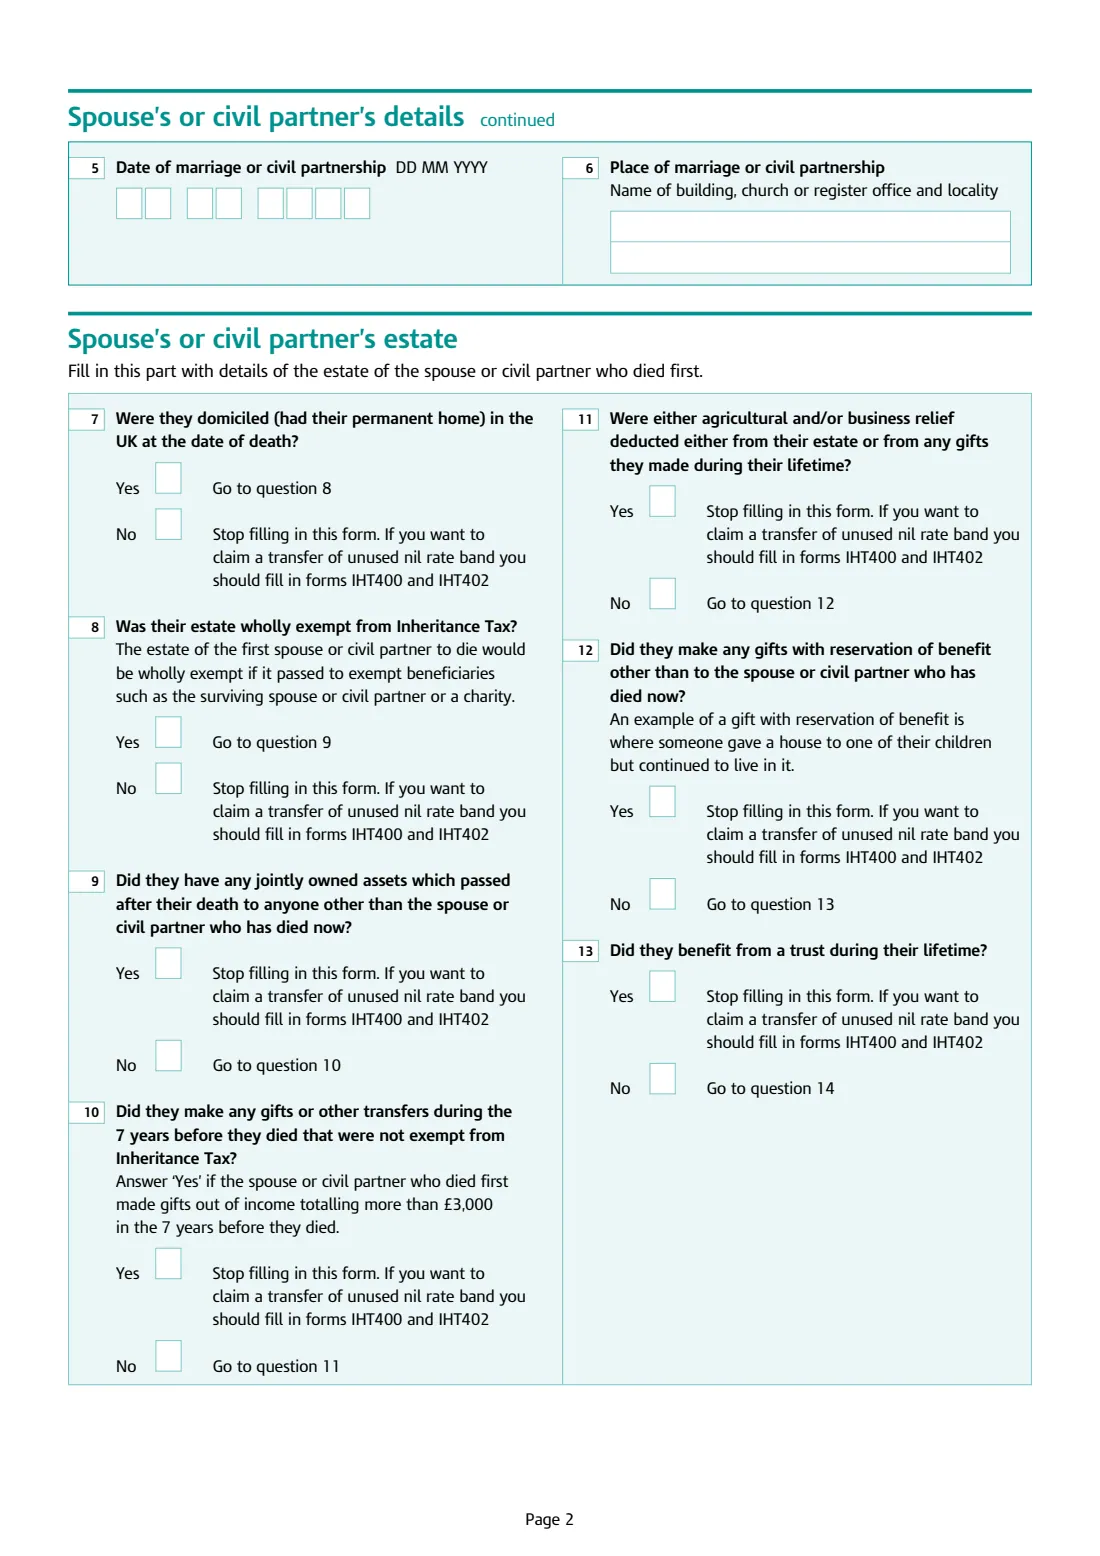
This version is only for deaths between 6 April 2010 and 31 December 2021. The form itself says not to use it for later deaths. A run of yes/no questions checks the first estate qualifies: a UK domicile, a wholly exempt estate, and no jointly owned assets passing to others, chargeable gifts, business or agricultural relief, gifts with reservation or trust interests. Any answer that doesn't fit means the claim needs IHT400 and IHT402 instead.
FileIt asks each question in plain language, tells you straight away if an answer means this form isn't the right one, doubles the nil rate band for box 15, and prints everything into HMRC's own IHT217 PDF, ready to sign and send with the probate application.
- Who fills it
- Everyone applying for the grant of representation (confirmation in Scotland) for the second estate
- Sent with
- Form IHT205 (or C5(2006) in Scotland) and the probate or confirmation application
- Deaths covered
- 6 April 2010 to 31 December 2021
- Deadline
- 24 months after the end of the month of death
- Edition
- HMRC 10/21
- Helpline
- Inheritance Tax helpline 0300 123 1072
Who needs to fill out IHT217 unused nil rate band (excepted estates)?
- Executors and administrators of a widow's, widower's or surviving civil partner's excepted estate, where the death was in the dates above.
- Families who are applying for probate late for an older death and still need to report the estate on IHT205.
- Only where the first spouse's or civil partner's estate used none of its nil rate band, so 100% is claimed.
When to use IHT217 unused nil rate band (excepted estates)
- When you have filled in IHT205 or C5(2006) and the estate is under twice the nil rate band, so the transfer keeps it an excepted estate.
- Send it with the application for the grant to the probate registry or the sheriff clerk's office, not to HMRC.
- Not if you're filling in form IHT400. Use IHT402 instead, and IHT436 as well for the residence nil rate band.
What you need before you start
- The name and date of death of the person who has died now.
- The first spouse's or civil partner's name, last address, date of death, and the date and place of the marriage or civil partnership.
- Copies of their grant of representation, will and any deed of variation (keep them safe, don't send the originals).
- Enough about the first estate to answer questions 7 to 13: domicile, exemptions, joint assets, gifts, reliefs and trusts.
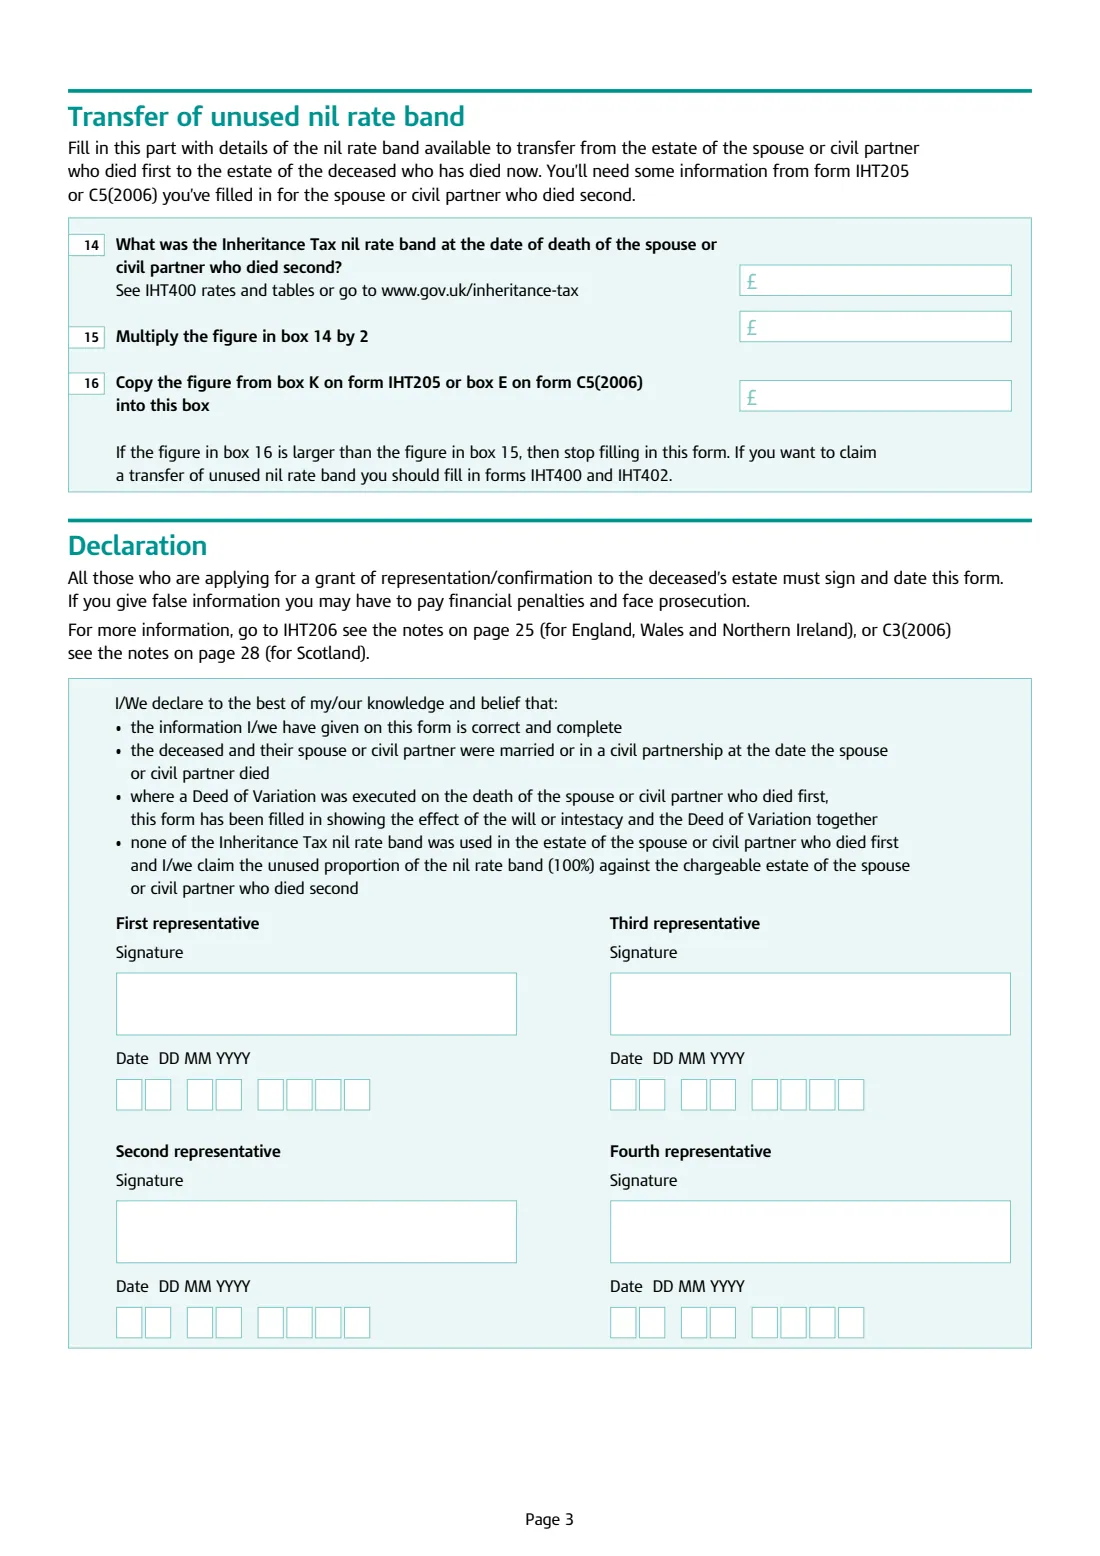
- The nil rate band at the second death, and the figure from box K of IHT205 (or box E of C5(2006)).
What’s on IHT217 unused nil rate band (excepted estates)
The 2021 edition has 4 pages. FileIt asks for it in 5 parts, and it is signed by Representative applying for the grant:
- The person who has died nowRepresentative applying for the grant
- Spouse or civil partner who died first (1 to 6)Representative applying for the grant
- Spouse or civil partner's estate (7 to 13)Representative applying for the grant
- Transfer of unused nil rate band (14 to 16)Representative applying for the grant
- DeclarationRepresentative applying for the grant
How to fill out IHT217 unused nil rate band (excepted estates), step by step
1 The person who has died now
Their name and date of death. FileIt checks the date falls between 6 April 2010 and 31 December 2021, which this version covers.
2 The first spouse or civil partner (1 to 6)
Title, names, last permanent address, date of death, whether a grant was taken out (with its date and place) and the date and place of the marriage or civil partnership.
3 Their estate (7 to 13)
Seven yes/no questions. The form says 'stop filling in this form' for certain answers, and FileIt flags those for you, since they mean the claim belongs on IHT400 and IHT402.
4 Transfer of unused nil rate band (14 to 16)
Enter the nil rate band at the second death (£325,000 for every death in the period). FileIt doubles it for box 15. Copy box K from IHT205 into box 16. If box 16 is more than box 15, this form can't be used.
5 Declaration
Everyone applying for the grant signs and dates it. FileIt prints each person's date in the boxes, and the first signature box can go for e-signature.
Common mistakes to avoid
- Using it for a death on or after 1 January 2022, which the form says not to do.
- Using it when only part of the first nil rate band is unused. IHT217 claims 100%, so a partial claim needs IHT402.
- Carrying on after an answer that says 'stop filling in this form'.
- Sending it to HMRC instead of with the probate application.
- Not every applicant for the grant signing the declaration.
After you fill it out
Check the preview and download the filled PDF.
Have every applicant sign and date it, then send it with IHT205 (or C5(2006)) and the grant application to the probate registry or sheriff clerk. FileIt doesn't send it for you.
Keep the copies of the first spouse's grant, will and any deed of variation safe in case HMRC asks for them. FileIt is a good place for the scans.
Fill out IHT217 unused nil rate band (excepted estates) online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 31 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real HMRC form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault. Sign it, or send it for e-signature.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start IHT217 unused nil rate band (excepted estates) now — it’s freeIHT217 unused nil rate band (excepted estates): frequently asked questions
What's the difference between IHT217 and IHT402?
Both claim a late spouse's or civil partner's unused nil rate band. IHT217 is the short version for an excepted estate reported on IHT205 where 100% of the first band is unused. IHT402 goes with the full IHT400 account and handles a partly used band.
Can I use IHT217 for a death in 2022 or later?
No. The form says not to use it for deaths on or after 1 January 2022. For those, the excepted estate rules changed and the transfer is claimed differently.
What is box 15 for?
Box 15 is twice the nil rate band. The estate must be no more than that (box 16) for the claim to keep it an excepted estate. FileIt works box 15 out for you.
Who has to sign?
Everyone applying for the grant of representation or confirmation. There's room for four people.
Where do I send it?
With form IHT205 (or C5(2006)) to the probate registry or sheriff clerk's office, as part of the application for the grant.
Official sources
- Blank form (PDF), published by HMRC: https://assets.publishing.service.gov.uk/media/61b753cde90e07043e8ff582/IHT217.pdf
- Official instructions and guidance: https://www.gov.uk/government/publications/inheritance-tax-claim-to-transfer-unused-nil-rate-band-for-excepted-estates-iht217
- Edition shown on this page: HMRC 10/21 (checked 2026-10-19).
FileIt is not affiliated with or endorsed by HMRC or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-10-19.