What is L 1i (2025) — foreign and untaxed employment income?
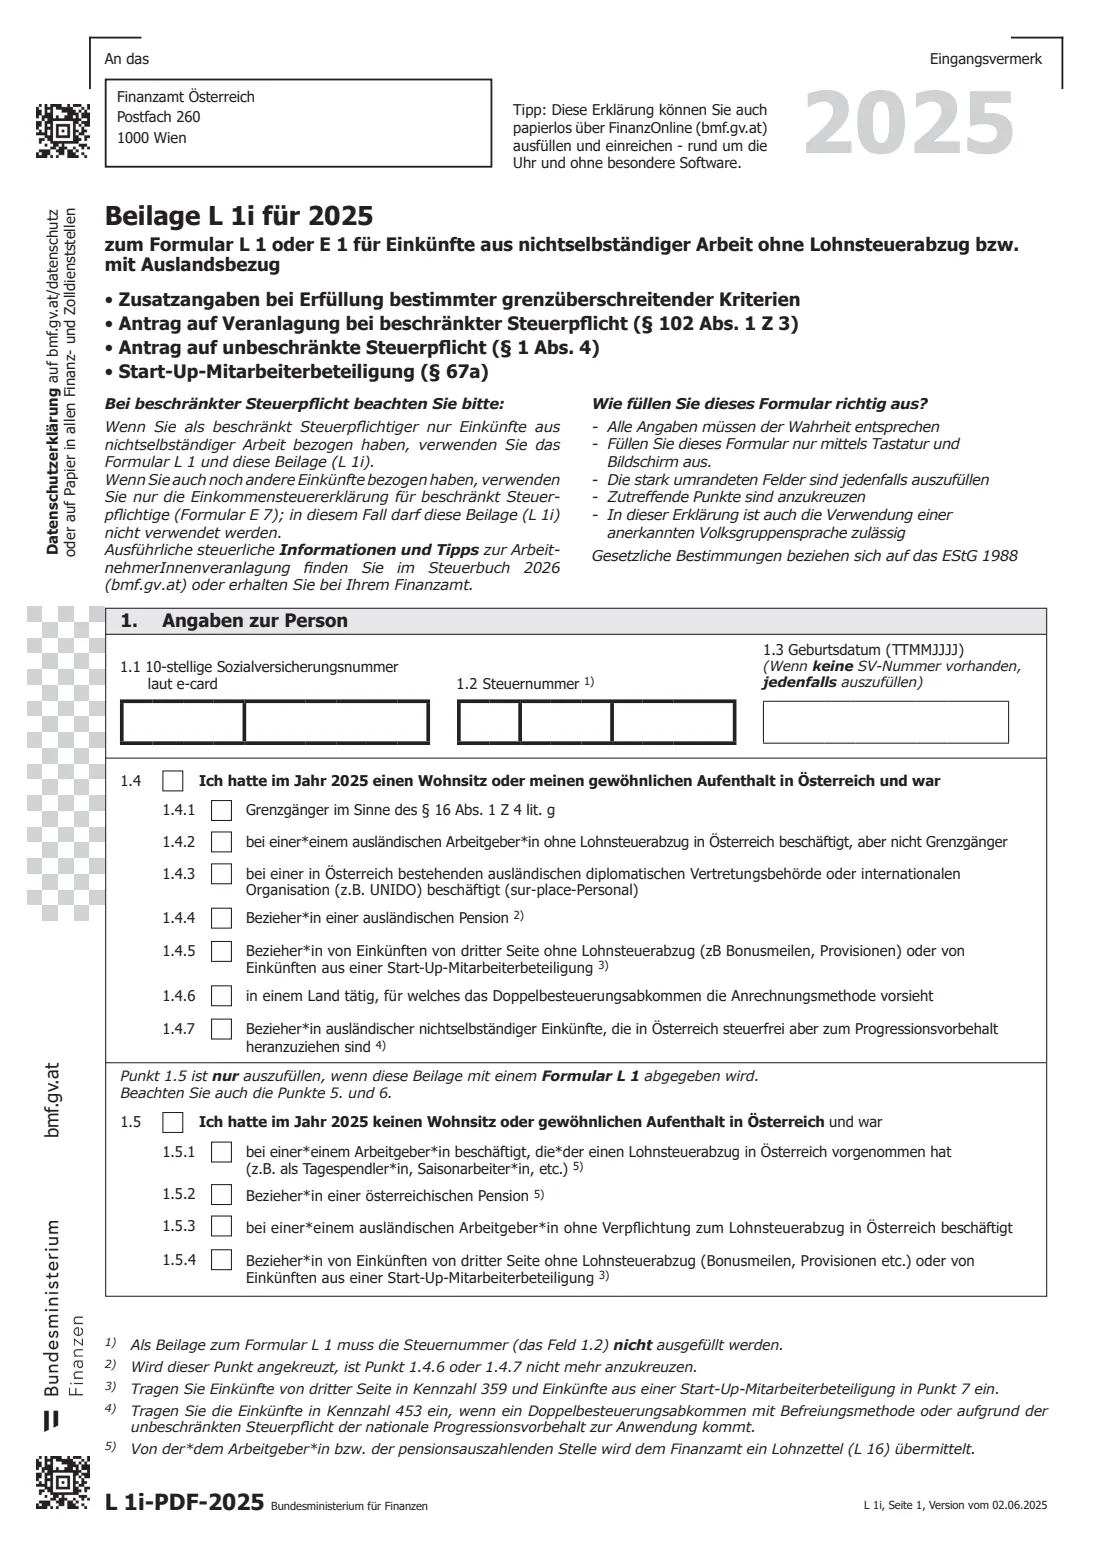
Most employees in Austria never see the L 1i. Their employer deducts wage tax and reports their pay, and the employee tax assessment (L 1) is enough. The Beilage L 1i, published by the Federal Ministry of Finance (Bundesministerium für Finanzen, BMF), is for everything that doesn't fit that pattern: pay from a foreign employer with no Austrian wage tax deducted, work across a border, a foreign pension, salaries from international organisations such as UNIDO, and income that is tax-free in Austria under a double tax treaty but still counts towards the tax rate on your other income (the Progressionsvorbehalt). The edition covered here is L 1i-PDF-2025, Version vom 02.06.2025, for the 2025 tax year.
It is also where people without a home in Austria make two requests: an assessment under limited tax liability for employment income (part 5), or to be treated as fully liable to tax (part 6, which needs a certificate from the country of residence, form E 9). Part 7 covers the taxation of a start-up employee share after the job has ended. The L 1i is always a supplement. It goes with an L 1 or an E 1 and is not filed on its own.
FileIt walks you through all seven parts in English, with the German terms and Kennzahl numbers alongside. It checks your social security number and the form's own cross-references, and prints your answers into the BMF's PDF the way its boxes expect: amounts right-aligned with a decimal comma, and the header on pages 2 and 3 with your tax and social security numbers. The finished PDF is saved in your vault. FileIt does not send anything to the tax office: you sign the L 1i by hand and send it with your L 1 or E 1, or make the same entries in FinanzOnline.
- Who fills it
- Employees and pensioners with untaxed or cross-border employment income for 2025
- Goes with
- Your L 1 (employee tax assessment) or E 1 (income tax return) for 2025
- Sent to
- Finanzamt Österreich, Postfach 260, 1000 Wien, or the same entries in FinanzOnline
- Pages
- 3, in seven parts
- Signatures
- You sign and date it by hand on page 3
- Edition
- L 1i-PDF-2025, Version vom 02.06.2025
Who needs to fill out L 1i (2025) — foreign and untaxed employment income?
- Cross-border commuters (Grenzgänger) who live in Austria and work just across the border.
- People living in Austria who work for a foreign employer that doesn't deduct Austrian wage tax.
- Staff of foreign embassies or international organisations in Austria.
- People receiving a foreign pension, or third-party payments without wage tax such as commissions or bonus miles.
- Anyone with foreign employment income that is exempt in Austria but counts towards the rate (Kennzahl 453).
- People with no home in Austria who want an assessment of their Austrian employment income, or to be treated as fully liable to tax.
- Former employees of a start-up whose employee share has to be taxed after the job ended.
When to use L 1i (2025) — foreign and untaxed employment income
- With your 2025 employee tax assessment (L 1) or income tax return (E 1), whenever one of the situations in parts 1.4 or 1.5 applies to you.
- When foreign income has to be declared for the Progressionsvorbehalt, even though Austria doesn't tax it.
- When you want to apply for an assessment under limited tax liability (part 5). The form notes that if you also had other income, you file form E 7 instead and the L 1i can't be used.
- When you live abroad and earn most of your income in Austria, and want to be treated as fully liable to tax (part 6), with form E 9 from your country of residence.
What you need before you start
- Your 10-digit Austrian social security number, or your date of birth if you don't have one.
- Your tax number, but only if the L 1i goes with an E 1. With an L 1 the form says to leave it empty.
- Your country of residence as a vehicle registration code (A, D, H, I and so on), and a certificate of residence if that country isn't Austria.
- Your income without a pay statement, with the social security contributions and creditable foreign tax.
- The number of pay statements (form L 17), and any foreign health insurance or work expenses for the foreign income.
- Figures from a type 24 pay slip, and the status of any relief from the foreign tax.
- For the Progressionsvorbehalt: the exempt foreign income, the social security contributions and work expenses in it, and any foreign pension.
- For part 6: form E 9 with your income in your country of residence, other foreign income, and your partner's income if needed.
- For part 7: the benefit received from the start-up employee share.
What’s on L 1i (2025) — foreign and untaxed employment income
The 2025 edition has 3 pages. FileIt asks for it in 12 parts, and it is signed by Taxpayer (steuerpflichtige*r):
- 1. About you (Angaben zur Person)Taxpayer (steuerpflichtige*r)
- 1.4–1.5 Residence in Austria in 2025 (Wohnsitz oder gewöhnlicher Aufenthalt)Taxpayer (steuerpflichtige*r)
- 1.6 Country of residence (Ansässigkeitsstaat)Taxpayer (steuerpflichtige*r)
- 2.1 Employment income without a pay statement (Einkünfte OHNE Lohnausweis)Taxpayer (steuerpflichtige*r)
- 2.2 Income with a pay statement (Einkünfte, für die ein Lohnausweis L 17 vorliegt)Taxpayer (steuerpflichtige*r)
- 2.3 Income with a pay slip of type 24 (Einkünfte, für die ein Lohnzettel der Lohnzettelart 24 vorliegt)Taxpayer (steuerpflichtige*r)
- 3. Relief from the foreign tax by the foreign tax authority (Entlastung von der Auslandssteuer)Taxpayer (steuerpflichtige*r)
- 4. Foreign income exempt with progression (Progressionsvorbehalt bei Auslandseinkünften)Taxpayer (steuerpflichtige*r)
- 5. Request for an assessment with limited tax liability (Antrag auf Veranlagung bei beschränkter Steuerpflicht, § 102 (1) no. 3)Taxpayer (steuerpflichtige*r)
- 6. Request to be treated as fully liable to tax (Antrag auf unbeschränkte Steuerpflicht, § 1 (4))Taxpayer (steuerpflichtige*r)
- 7. Start-up employee share scheme (Start-Up-Mitarbeiterbeteiligung, § 67a)Taxpayer (steuerpflichtige*r)
- Declaration and signature (Richtigkeits- und Vollständigkeitserklärung)Taxpayer (steuerpflichtige*r)
How to fill out L 1i (2025) — foreign and untaxed employment income, step by step
1 1. About you
Give your social security number as on the e-card. Your date of birth is required if you don't have one. Give the tax number only if the L 1i goes with an E 1. Then tick either 1.4 (you had a home or habitual abode in Austria in 2025) or 1.5 (you didn't), and every description below it that fits. Part 1.5 is only for an L 1i that goes with an L 1. If you tick 1.4.4 (foreign pension), don't also tick 1.4.6 or 1.4.7.
2 1.6 Country of residence
Always give the country where your centre of vital interests is, as a vehicle registration code. If it isn't Austria, say whether you have a certificate of residence and whether you receive foreign income.
3 2. Income Austria may tax
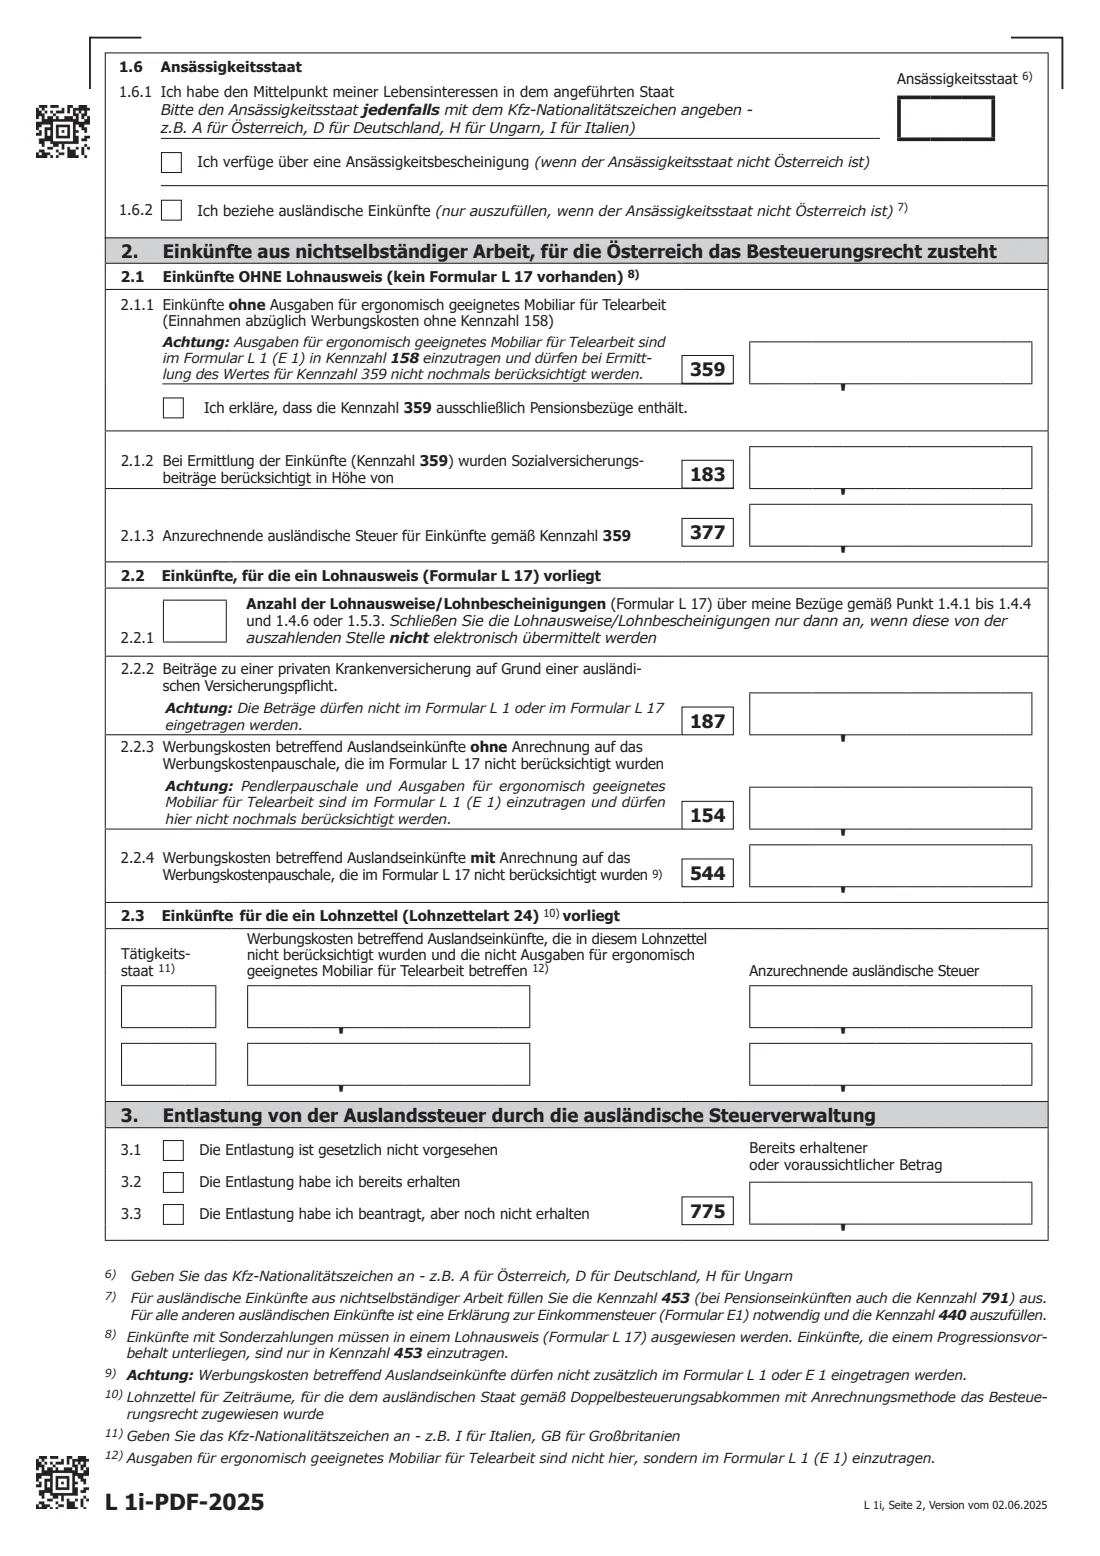
Part 2.1 is for income without a pay statement: Kennzahl 359, with the social security contributions (183) and creditable foreign tax (377) in it. Part 2.2 counts the pay statements (L 17) and adds foreign health insurance (187) and work expenses (154 and 544) not on them. Part 2.3 holds up to two type 24 pay slip rows, one per country.
4 3. Relief from the foreign tax
Say whether the law provides no relief, whether you have already received it, or whether you applied and are still waiting. Give the amount received or expected in Kennzahl 775.
5 4. Progressionsvorbehalt
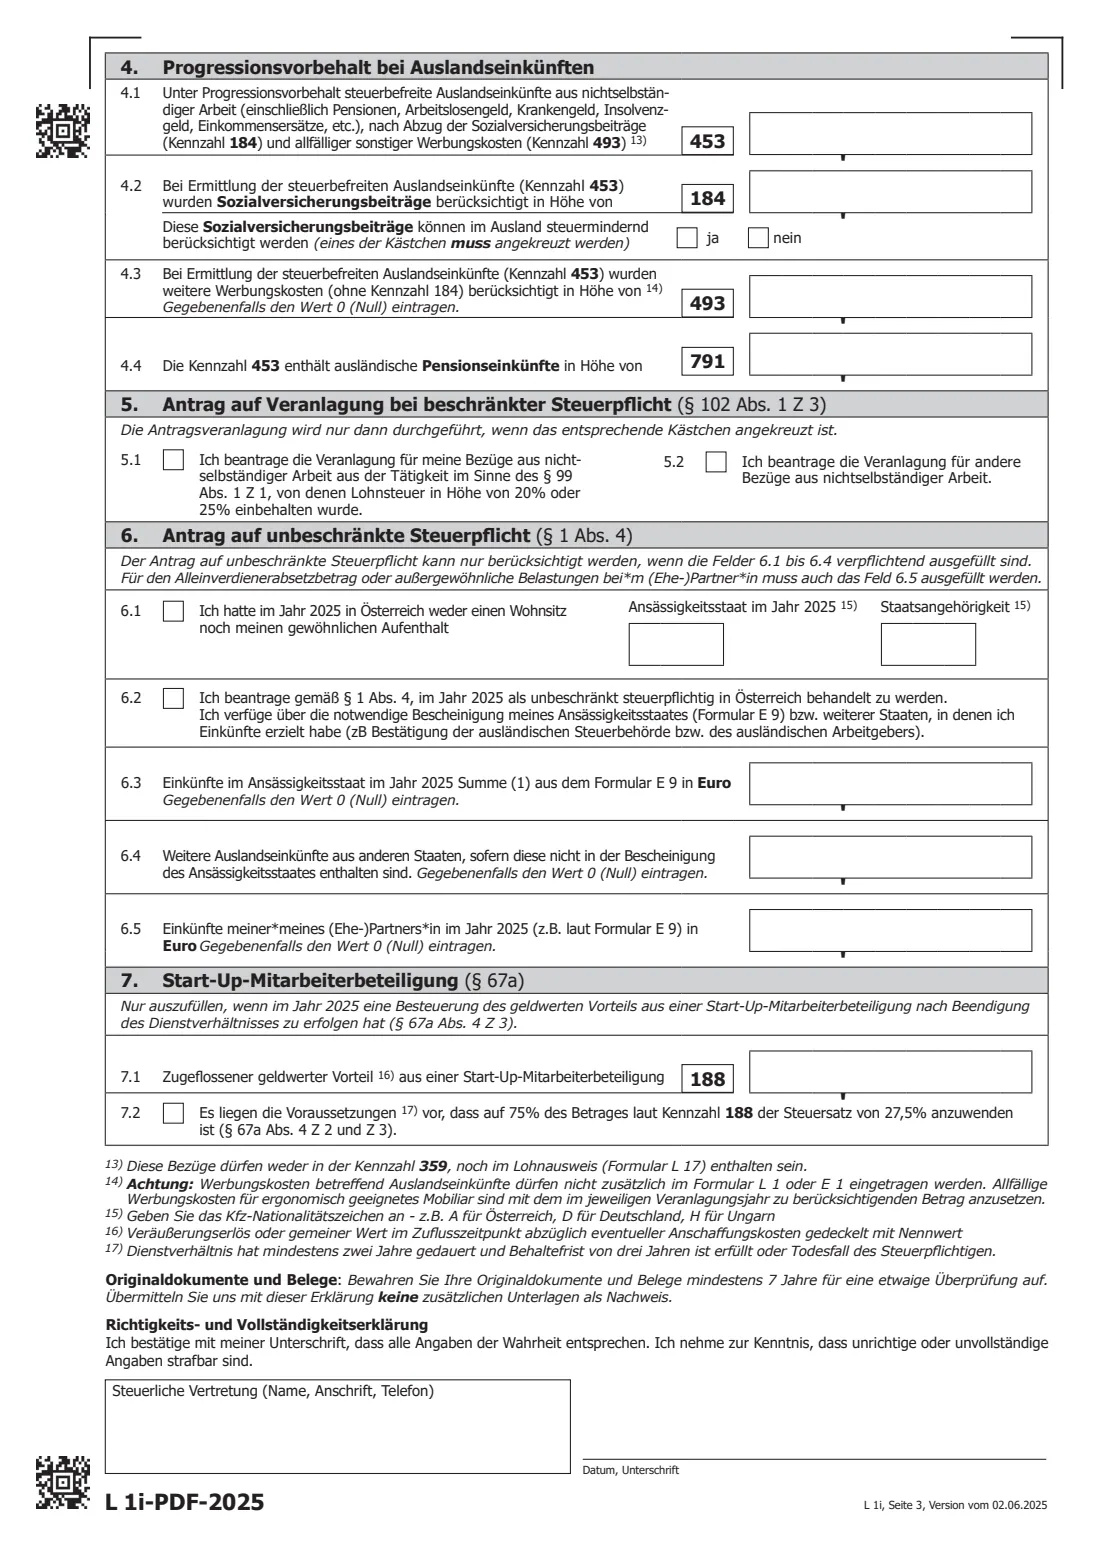
Enter the exempt foreign income in Kennzahl 453, after the social security contributions (184) and other work expenses (493). Enter 493 as 0 if there were none. If you entered 184, you must tick whether those contributions can reduce tax abroad. Kennzahl 791 shows how much of 453 is a foreign pension.
6 5. and 6. Limited or full tax liability
Part 5 asks for an assessment of your employment income under limited tax liability, and is only carried out if you tick a box. Part 6 asks to be treated as fully liable. It only counts if 6.1 to 6.4 are all filled in, with your country of residence, nationality and the income figures from form E 9. Add 6.5, your partner's income, if you claim the sole earner's credit or extraordinary burdens for them.
7 7. Start-up employee share and signature
Enter the benefit from a start-up employee share in Kennzahl 188, and tick 7.2 if the reduced rate conditions are met. Add your tax representative if you have one, date the form and sign it by hand.
Common mistakes to avoid
- Filing the L 1i on its own. It is always a supplement to an L 1 or E 1.
- Filling in the tax number when the L 1i goes with an L 1. Footnote 1 says not to.
- Counting the same income twice, in Kennzahl 359 or on a pay statement and again in Kennzahl 453.
- Entering ergonomic telework furniture or the commuter allowance here. They belong on the L 1 or E 1.
- Leaving the 4.2 yes/no unticked after entering Kennzahl 184, or leaving 4.3 empty instead of 0.
- Asking to be treated as fully liable without filling in 6.1 to 6.4, or without form E 9.
- Using the L 1i with limited tax liability when you had other income too. The form says to use the E 7 then.
After you fill it out
Print the three pages, sign by hand beside the date on page 3, and put the L 1i with your L 1 or E 1.
Post them to Finanzamt Österreich, Postfach 260, 1000 Wien. FileIt doesn't send anything for you.
Attach pay statements (L 17) only if the payer doesn't send them electronically. Keep your other receipts for at least 7 years, as the form asks.
FileIt keeps the finished PDF in your vault with the return it belongs to.
Fill out L 1i (2025) — foreign and untaxed employment income online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 74 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real Bundesministerium für Finanzen (BMF) — Finanzamt Österreich form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault. Sign it, or send it for e-signature.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start L 1i (2025) — foreign and untaxed employment income now — it’s freeL 1i (2025) — foreign and untaxed employment income: frequently asked questions
Do I need the L 1i if my Austrian employer deducts wage tax?
Usually not. The L 1i is for income without Austrian wage tax or with a foreign element. An employee whose pay is fully taxed through Austrian payroll normally only needs the L 1.
What is the Progressionsvorbehalt?
Foreign income that a double tax treaty exempts in Austria is not taxed here, but it is used to work out the tax rate on your other income. You declare it in Kennzahl 453 in part 4.
Can I use the L 1i with an E 1?
Yes. It goes with either an L 1 or an E 1. With an E 1 you give your tax number. Part 1.5 is only for an L 1i that goes with an L 1.
What is form E 9?
A certificate from your country of residence about your income there. Part 6 refers to it for the request to be treated as fully liable to tax in Austria.
Can I enter a loss?
FileIt accepts a negative figure in Kennzahl 359 and Kennzahl 453 and prints it with a minus sign. The other boxes take positive amounts.
Is the form in English?
No, the L 1i is in German. FileIt explains each part in English and prints your answers into the official BMF PDF.
Does FileIt file the L 1i for me?
No. FileIt fills the PDF and saves it in your vault. You sign it and send it with your return, or enter the same figures in FinanzOnline yourself.
Official sources
- Blank form (PDF), published by Bundesministerium für Finanzen (BMF) — Finanzamt Österreich: https://formulare.bmf.gv.at/service/formulare/inter-Steuern/pdfs/2025/L1i.pdf?open=download
- Official instructions and guidance: https://formulare.bmf.gv.at/service/formulare/inter-Steuern/
- Edition shown on this page: L 1i-PDF-2025, Version vom 02.06.2025 (checked 2026-10-19).
FileIt is not affiliated with or endorsed by Bundesministerium für Finanzen (BMF) — Finanzamt Österreich or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-10-19.