What is ZS-QU1 — DTC relief at source (individuals)?
Some Austrian income paid to people who live abroad, such as royalties or lecture fees, is subject to Austrian withholding tax at source. Where Austria's double tax treaty with the recipient's country of residence reduces or removes that tax, the relief can be applied straight away when the payer withholds, instead of being reclaimed later. The ZS-QU1 is the Austrian Federal Ministry of Finance's declaration for individuals that makes this possible. It is made under § 2 of the DBA-Entlastungsverordnung. The current edition is dated 16 September 2026.
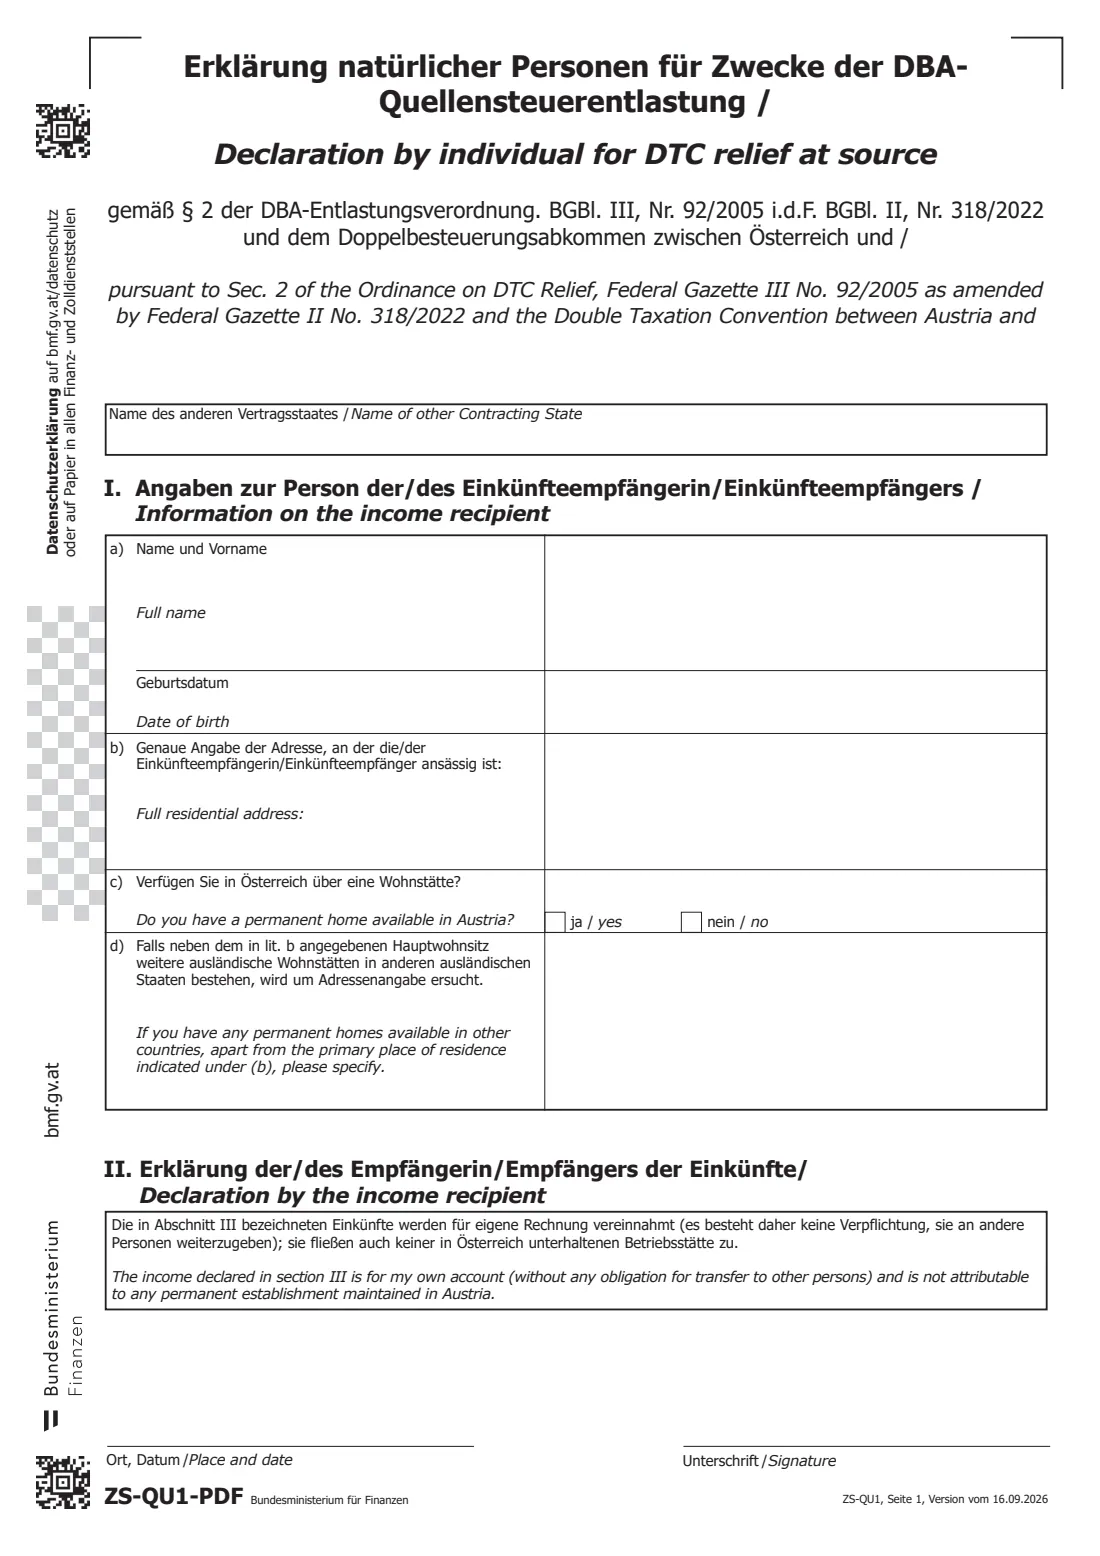
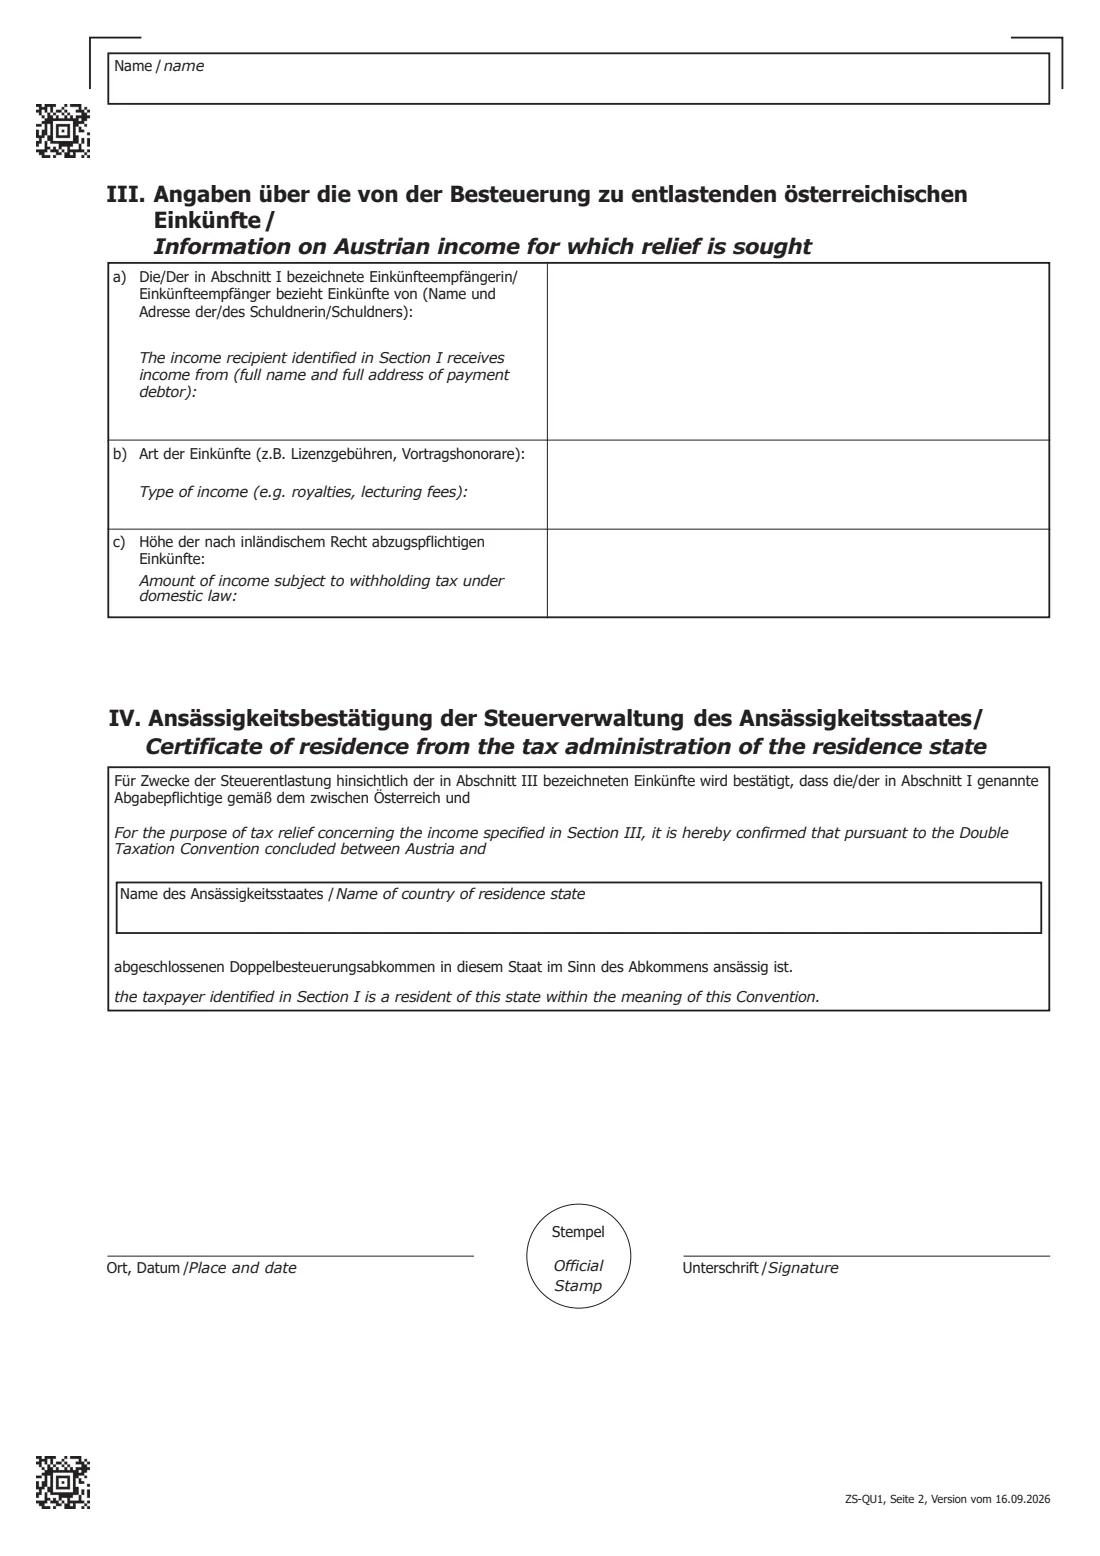
The form is in German and English. You name your country of residence and give your details, including whether you have a permanent home in Austria. You describe the Austrian income: who pays it, what kind it is and how much. Section II is a printed declaration that the income is yours, with no obligation to pass it on, and is not attributable to a permanent establishment in Austria. Section IV is a certificate of residence that the tax administration of your country of residence completes and stamps.
FileIt fills sections I to III of the official PDF with you, prints your name and country where the form repeats them, and files the PDF in your vault. You sign it by hand, have your tax office certify section IV, and give it to the Austrian payer. FileIt never submits anything.
- Issued by
- Bundesministerium für Finanzen (Austrian Federal Ministry of Finance)
- Who fills it
- An individual resident outside Austria who receives Austrian income with tax withheld at source
- Given to
- The Austrian payer of the income, who applies the relief
- Certified by
- The tax administration of your country of residence (section IV, with official stamp)
- Edition
- ZS-QU1, Version vom 16.09.2026, 2 pages, German and English
Who needs to fill out ZS-QU1 — DTC relief at source (individuals)?
- Authors, artists and inventors abroad receiving royalties (Lizenzgebühren) from an Austrian company.
- Speakers and lecturers abroad paid lecture fees (Vortragshonorare) by an Austrian organiser.
- Other individuals resident in a treaty country whose Austrian income has tax withheld at source and who want treaty relief applied immediately.
- Austrian payers who ask their foreign payees for the declaration before paying.
When to use ZS-QU1 — DTC relief at source (individuals)
- Before the Austrian payer pays you, so the reduced treaty rate or exemption can be applied at source.
- When the payer asks for a ZS-QU1 to support treaty relief.
- Not if you are resident in Austria. The relief is for residents of the other treaty state.
What you need before you start
- Your full name, date of birth and full residential address abroad.
- Whether you have a permanent home available in Austria, and any homes in other countries.
- The Austrian payer's full name and address.
- The type of income and the amount subject to Austrian withholding tax.
- Access to your own tax administration to certify your residence in section IV.
What’s on ZS-QU1 — DTC relief at source (individuals)
The 2026 edition has 2 pages. FileIt asks for it in 3 parts:
- Treaty country and recipient (I. Angaben zur Person)Income recipient (einkünfteempfänger)
- III. Austrian income for which relief is soughtIncome recipient (einkünfteempfänger)
- II. Declaration - place, date and signatureIncome recipient (einkünfteempfänger)
How to fill out ZS-QU1 — DTC relief at source (individuals), step by step
1 Name des anderen Vertragsstaates
The country you are resident in, whose treaty with Austria you rely on. FileIt prints it again in section IV.
2 I. Angaben zur Person
Your full name, date of birth and full residential address, whether you have a permanent home in Austria, and any permanent homes in other countries.
3 II. Erklärung
The printed declaration that the income is for your own account and not attributable to a permanent establishment in Austria. Add the place and date, and sign.
4 III. Angaben über die Einkünfte
The name and address of the Austrian payer, the type of income (for example royalties or lecture fees), and the amount subject to withholding tax under Austrian law.
5 IV. Ansässigkeitsbestätigung
Completed by the tax administration of your country of residence. It confirms you are resident there under the treaty and adds a place, date, signature and official stamp.
Common mistakes to avoid
- Signing without having section IV certified. The form expects your own tax administration's confirmation and stamp.
- Leaving out the payer's full address, or describing the income vaguely.
- Forgetting to mention a permanent home in Austria or in another country.
- Using it while resident in Austria. The relief is for residents of the other treaty state.
After you fill it out
Print the PDF and sign section II by hand. FileIt does not send it for you.
Have the tax administration of your country of residence complete and stamp section IV.
Give the certified form to the Austrian payer before the income is paid, and keep a copy in your FileIt vault.
Fill out ZS-QU1 — DTC relief at source (individuals) online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 11 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real Bundesministerium für Finanzen (Austria) form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start ZS-QU1 — DTC relief at source (individuals) now — it’s freeZS-QU1 — DTC relief at source (individuals): frequently asked questions
What is the ZS-QU1?
It is the Austrian declaration by individuals for tax treaty relief at source, under § 2 of the DBA-Entlastungsverordnung. A non-resident gives it to the Austrian payer so treaty relief can be applied when tax is withheld.
Is the form in English?
Yes. Every heading and question is in German and English.
Who certifies section IV?
The tax administration of your country of residence. It confirms you are resident there within the meaning of the treaty, and signs and stamps the form.
Where do I send the form?
To the Austrian payer of the income named in section III, not to the Austrian tax office. FileIt never submits forms.
Can I e-sign the ZS-QU1?
FileIt doesn't offer e-signing for this form, because the signed and stamped paper original is what the payer relies on. Sign it by hand.
Can I fill in the ZS-QU1 online with FileIt?
Yes. FileIt fills sections I to III of the official PDF and saves it in your vault. You then sign it, have section IV certified, and hand it over yourself.
Official sources
- Blank form (PDF), published by Bundesministerium für Finanzen (Austria): https://formulare.bmf.gv.at/service/formulare/inter-Steuern/pdfs/9999/ZS-QU1.pdf?open=download
- Official instructions and guidance: https://formulare.bmf.gv.at/service/formulare/inter-Steuern/pdfs/9999/ZS-QU1.pdf
- Edition shown on this page: ZS-QU1-PDF, Version vom 16.09.2026 (checked 2026-10-01).
FileIt is not affiliated with or endorsed by Bundesministerium für Finanzen (Austria) or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-10-01.