What is a loan modification agreement?
Loans rarely run exactly to plan. A borrower hits a slow season and needs lower payments for a while, a lender agrees to extend the term rather than chase arrears, or both sides want to reset the rate after the market moves. Rewriting the whole loan is unnecessary and risky. A loan modification agreement changes only what needs to change and confirms everything else carries on as before, including any security and guarantee.
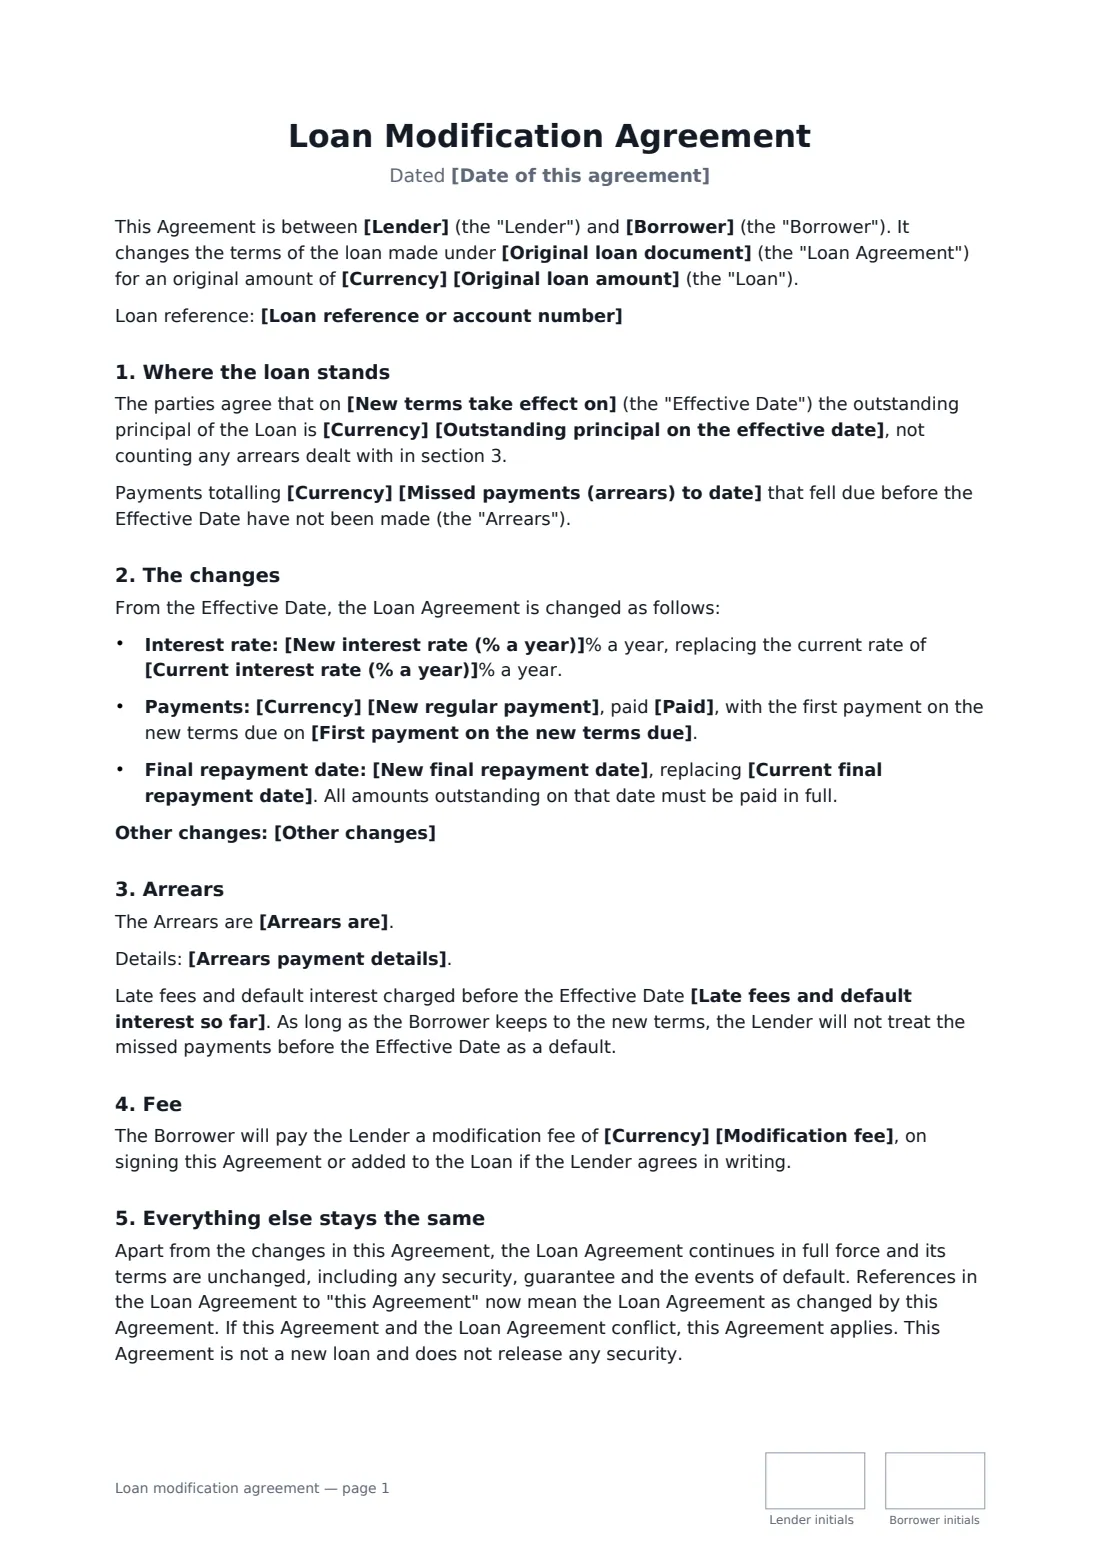
This template identifies the original loan document and reference, agrees the outstanding balance on the effective date and any missed payments, and sets out the new interest rate, payment amount and frequency, first payment date and final repayment date, printing only the terms you change. You choose whether arrears are added to the balance, repaid in extra instalments or paid in one sum, and whether past late fees are waived. It covers an optional modification fee, confirms that the rest of the original agreement is unchanged, and asks for guarantors to confirm their cover.
- Best for
- Business, private and family loans where both sides agree new terms
- Signed by
- The lender and the borrower
- Can change
- Interest rate, payment amount and frequency, final date, arrears treatment
- Length
- About 2 pages, initialled on every page
When to use a loan modification agreement
- A borrower struggling with cash flow needs smaller monthly payments
- A lender extends the final repayment date instead of calling in the loan
- Both sides agree to a lower interest rate after the borrower's credit improves
- Missed payments are folded into the balance and repaid over the remaining term
- Switching a loan from monthly to quarterly payments
What you fill in
23 blanks, then the name and email of each person who signs: lender, borrower.
1 The parties
- Date of this agreement*
- Lender*
- Borrower*
2 The existing loan
- Original loan document*
- Loan reference or account number
- Currency*
- Original loan amount*
- Outstanding principal on the effective date*
3 The new terms
- New terms take effect on*
- Current interest rate (% a year)
- New interest rate (% a year)
- New regular payment
- Paid* monthly · every two weeks · quarterly
- First payment on the new terms due*
- Current final repayment date
- New final repayment date
4 Arrears
- Missed payments (arrears) to date
- Arrears are* added to the outstanding principal and repaid over the remaining term · repaid in extra instalments as set out below · paid in one sum by the date set out below
- Arrears payment details
- Late fees and default interest so far* are waived · are added to the arrears · are not affected and remain payable
5 Other terms
- Modification fee
- Other changes
- Governing law*
6 Who signs
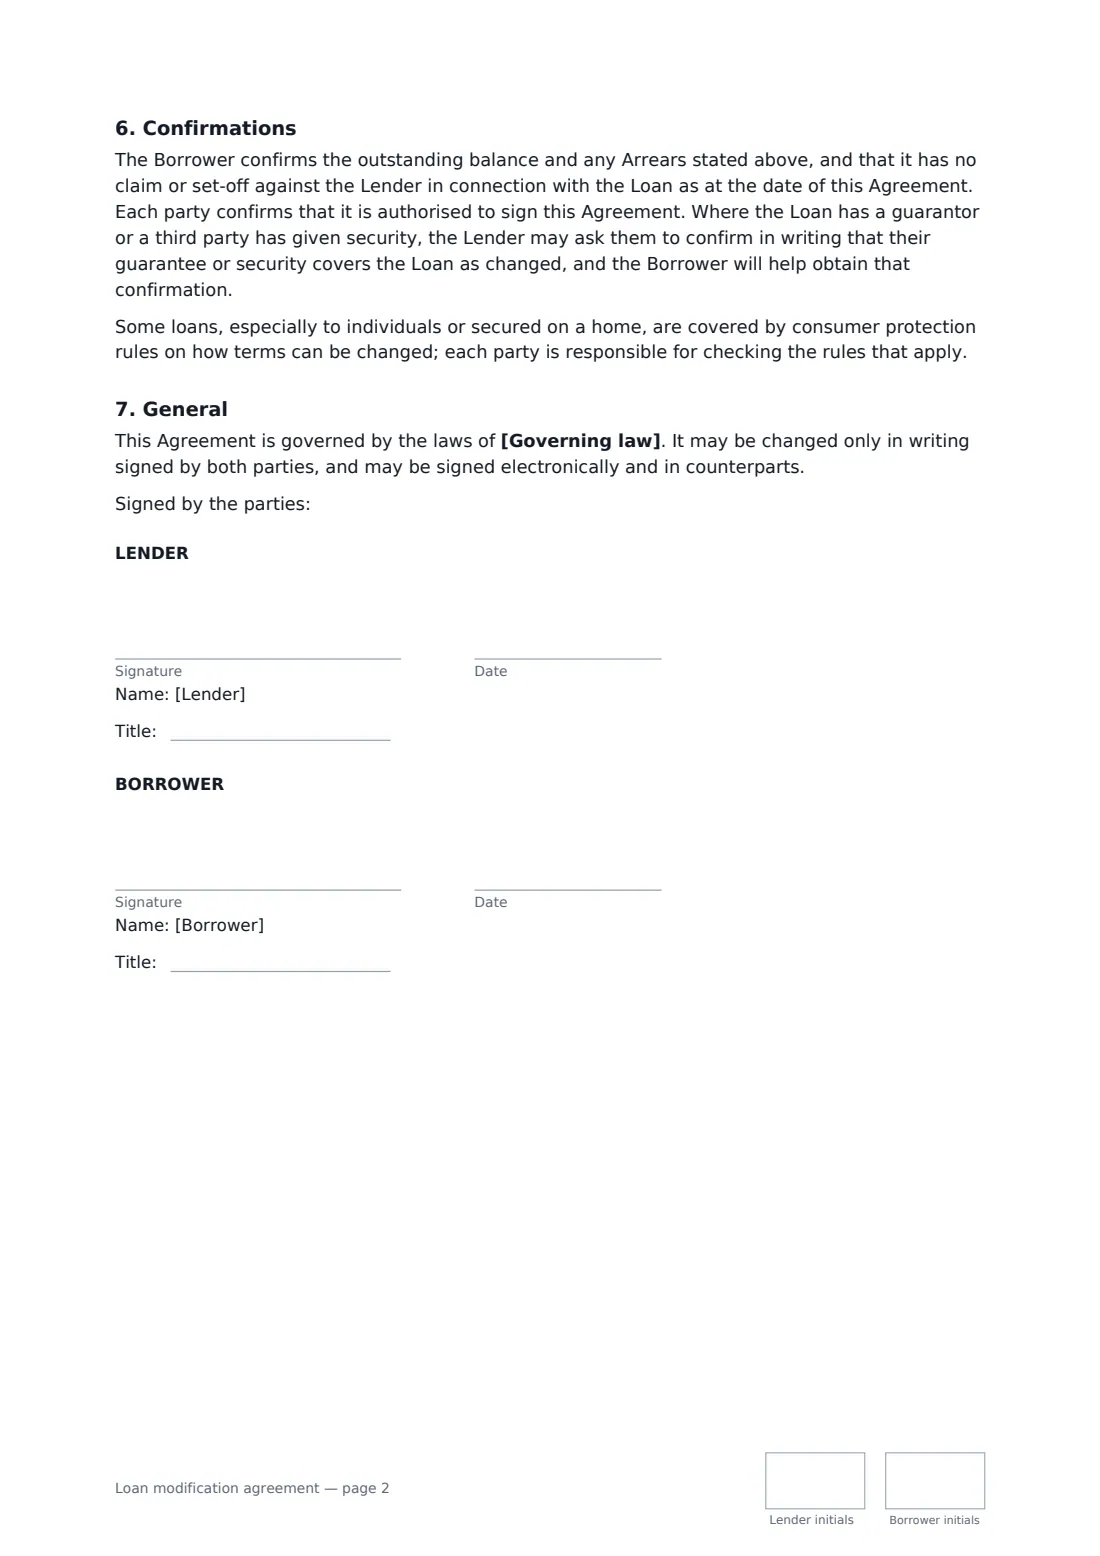
- Lender signature and date, job title, initials on every page · A business lender's signatory adds their title.
- Borrower signature and date, job title, initials on every page · If the borrower is a business, a person authorised to sign for it.
What the loan modification agreement covers
- Where the loan stands
- The changes
- Arrears
- Fee
- Everything else stays the same
- Confirmations
- General
Using the loan modification agreement, step by step
1 Identify the loan
Name the original loan document with its date, add the reference, and enter the original amount.
2 Agree where it stands
Enter the outstanding principal on the effective date and any arrears. Both sides confirm these figures by signing.
3 Set the new terms
Fill in only what changes: the new rate, the new payment and how often, the first payment date and the new final date. Anything left empty stays as it was.
4 Deal with arrears and fees
Choose how missed payments are repaid and whether past late fees are waived. Add a modification fee if there is one.
5 Sign it
Send it to the other party for signature. File the signed copy in your vault next to the original loan agreement.
Tips before you send it
- Agree the balance figure before you send. It is the number everything else is built on.
- If someone guaranteed the loan, get their written agreement to the change. Some guarantees can be weakened by a change made without the guarantor's consent.
- Recalculate the payment so the loan is still repaid by the final date.
- Loans to individuals or secured on a home may be covered by consumer rules on changes. Check before using this template for them.
Sign it online in minutes
- Fill in the blanks. Names, dates and amounts go straight into the agreement — the preview shows exactly where.
- Name who signs. Tick “This is me” for your own part. FileIt builds the PDF with every signature, date and initials box on the right line, and you can check or move anything before sending.
- Send it. Each signer gets a secure link and signs from any device — no account needed. The signed PDF, with an audit trail and a Certificate of Completion, is filed in your vault and emailed to everyone.
Loan modification agreement: frequently asked questions
Does a loan modification create a new loan?
No. The agreement says it changes the original loan agreement, which continues with its security, guarantee and default terms, and it is not a new loan.
What happens to missed payments?
You choose: add them to the balance and repay them over the remaining term, repay them in extra instalments, or pay them in one sum by a set date. While the borrower keeps to the new terms, the lender won't treat them as a default.
Do I need to change every term?
No. Only the terms you fill in print as changes. If the rate or final date is not changing, leave it empty.
Is this the same as a payment plan?
A payment plan usually sets out how an overdue bill or debt will be paid off. A loan modification changes the terms of an existing written loan agreement.
Can we sign it electronically?
Yes. Both parties sign online in FileIt, and the signed PDF includes an audit trail and Certificate of Completion.