What is Form 8233?
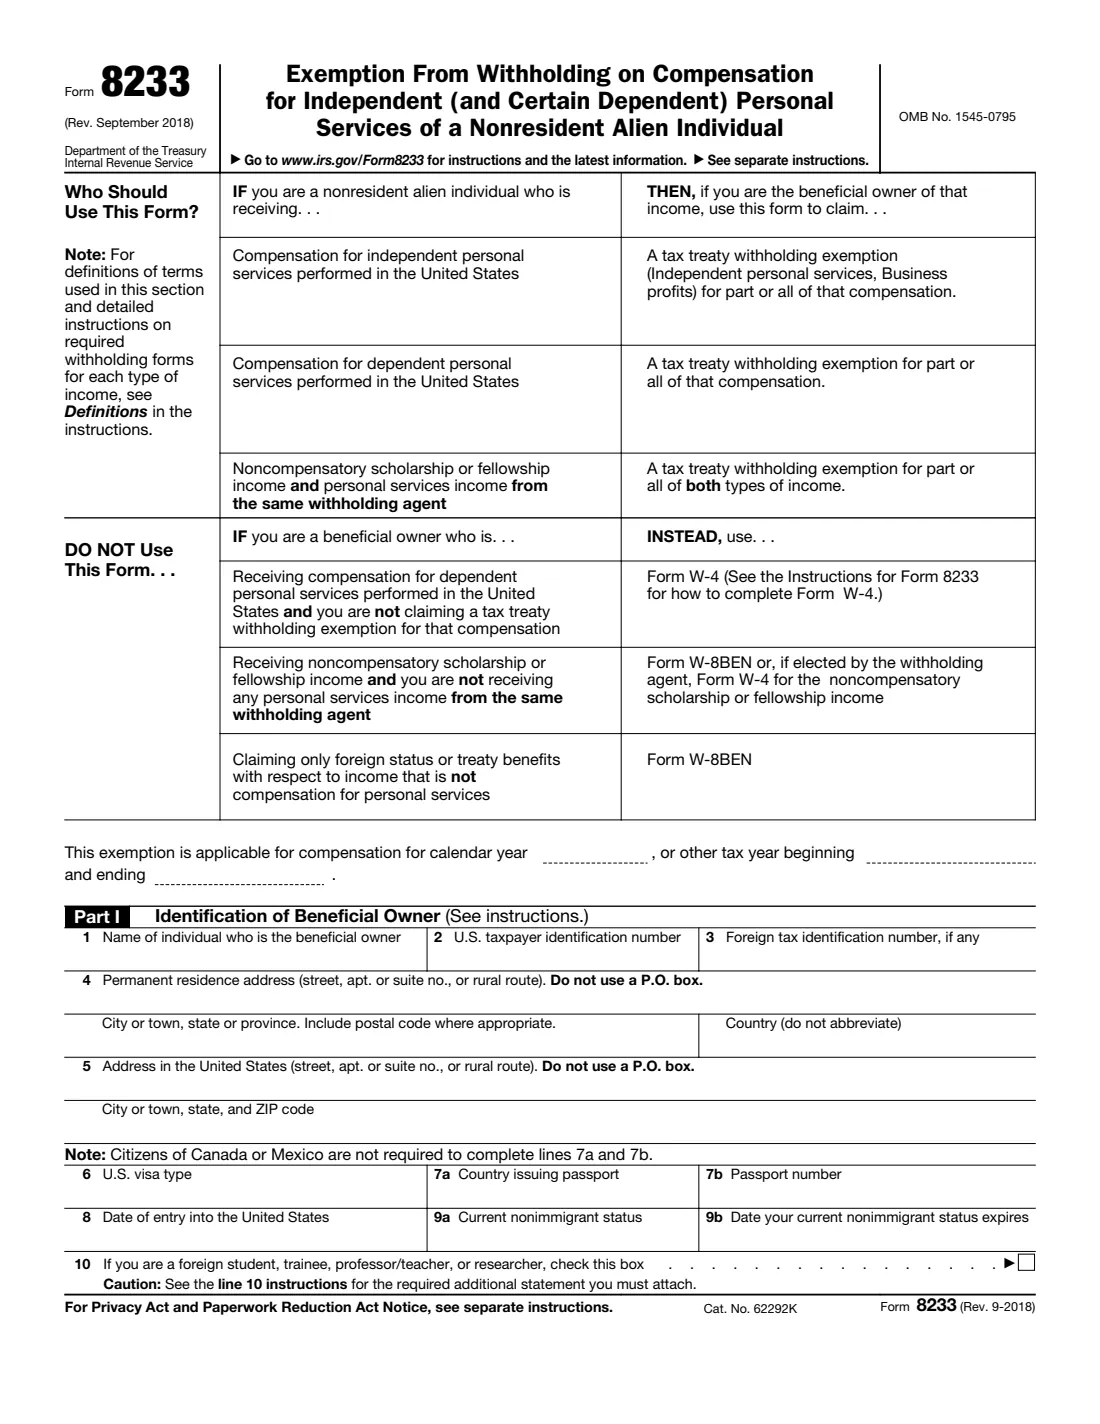
Form 8233 lets a nonresident alien individual claim a tax treaty exemption from US withholding on compensation for personal services performed in the United States. It covers independent work, such as a foreign consultant's contract fees or a visiting lecturer's honoraria, and dependent work, such as a visiting researcher's salary or a student's campus job, when a treaty between the US and your country of residence exempts that pay.
You don't send it to the IRS yourself. You give it to the withholding agent — usually your employer, university or client — who reviews it, signs the acceptance in Part IV and forwards a copy to the IRS within five days. The agent then waits at least ten days for any IRS objection before relying on it. You need a new Form 8233 for each tax year, each withholding agent and each type of income.
FileIt guides you through every line, checks that the exempt amounts and dates hang together, prints the answers into the IRS's own PDF and keeps it in your vault. It can also route the form to the withholding agent for their Part IV signature. FileIt never files anything with the IRS.
- Who fills it
- A nonresident alien individual claiming a treaty exemption on pay for personal services.
- Given to
- The withholding agent (employer, university or client), who forwards a copy to the IRS in Philadelphia.
- How often
- Every tax year, for each withholding agent and each type of income.
- Signatures
- You sign Part III; the withholding agent signs Part IV.
- Edition
- Rev. September 2018 (instructions Rev. December 2025)
- Agency
- Internal Revenue Service (IRS), Department of the Treasury
Who needs to fill out Form 8233?
- Visiting professors, teachers and researchers on a J-1 visa whose salary a treaty's teacher or researcher article exempts.
- F-1 and J-1 students with a campus job, assistantship or internship covered by a treaty's student article.
- Business and vocational trainees whose pay is treaty-exempt.
- Foreign consultants, lecturers and other independent contractors paid for work done in the US who qualify under a treaty's independent services or business profits article.
- Students who get both a noncompensatory scholarship and pay for services from the same school, and claim treaty benefits on both.
When to use Form 8233
- Before the first payment, or as soon as you start work, so the payer can stop withholding once the IRS's ten-day window has passed.
- At the start of each new tax year, because a Form 8233 covers one year only.
- Not for dependent pay when you aren't claiming a treaty exemption: give your employer Form W-4 instead.
- Not to claim foreign status or treaty benefits on income that isn't pay for services, such as interest or royalties: that's Form W-8BEN.
What you need before you start
- Your US taxpayer identification number: an SSN, or an ITIN if you can't get one (apply with Form W-7).
- Your foreign tax ID, permanent home address abroad and US address.
- Your visa type, passport country and number (not needed for Canadian or Mexican citizens), date of entry, and nonimmigrant status with its expiry date.
- The treaty and the specific article you rely on, and the amounts: total expected pay and the part that's exempt.
- The facts that support the claim, such as where you lived before arriving, why you're in the US and how long you'll stay.
- If you're a student, trainee, teacher or researcher: the statement from Appendix A or B of Publication 519 to attach.
What’s on Form 8233
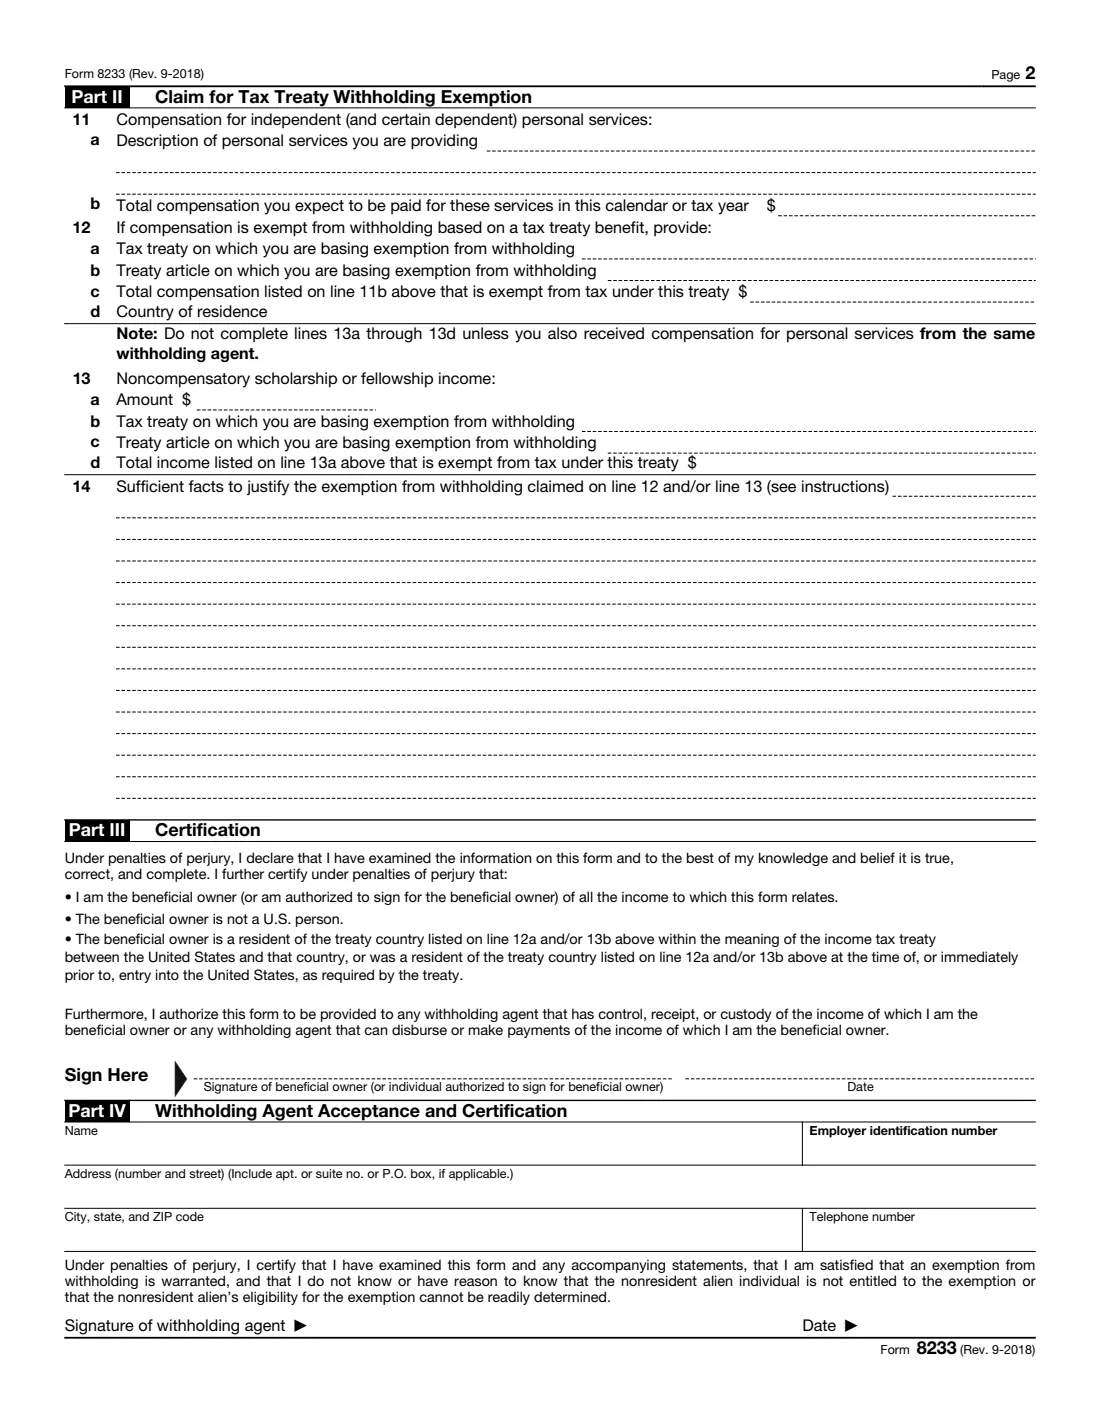
The 2018 edition has 2 pages. FileIt asks for it in 4 parts, and it is signed by Beneficial owner (nonresident alien) and Withholding agent:
- Tax yearBeneficial owner (nonresident alien)
- Part I: Identification of beneficial ownerBeneficial owner (nonresident alien)
- Part II: Claim for tax treaty withholding exemptionBeneficial owner (nonresident alien)
- Part IV: Withholding agent acceptanceWithholding agent
How to fill out Form 8233, step by step
1 Above Part I: The tax year
Enter the calendar year the exemption is for, or the start and end dates of a different tax year.
2 Part I, lines 1–5: Who you are
Your name, US TIN (required), any foreign tax ID, your permanent residence abroad (no P.O. box) and your US address.
3 Part I, lines 6–10: Visa and status
Your visa type (F-1, J-1, M-1 or "None"), passport details unless you're a Canadian or Mexican citizen, date of entry, and current status with its expiry date. Tick line 10 if you're a student, trainee, professor, teacher or researcher, and attach the Publication 519 statement.
4 Part II, lines 11–12: The services and the treaty
Describe the services — for example "teaching one chemistry course per semester" — and the total pay you expect from this payer this year. Then name the treaty, the article, the exempt amount and your country of residence. FileIt checks the exempt amount isn't more than the total.
5 Part II, line 13: Scholarship from the same payer
Only if the same withholding agent also pays you a noncompensatory scholarship or fellowship: its amount, treaty, article and exempt part.
6 Part II, line 14: The facts
Explain why you qualify in enough detail for the IRS to see the benefit you're claiming. FileIt warns you if the text won't fit the 15 lines on the form.
7 Parts III and IV: Signatures
You sign the certification in Part III. The withholding agent fills in its name, EIN, address and phone in Part IV and signs once it's satisfied the exemption is warranted. FileIt can send the form to the agent for that signature.
Common mistakes to avoid
- Leaving line 2 blank — a US TIN is required, so apply for an ITIN if you can't get an SSN.
- Naming the treaty but not the specific article, or giving an exempt amount above the treaty's dollar limit.
- Reusing last year's form instead of giving a new one for each tax year.
- Giving one form to two different payers: each withholding agent needs its own.
- Ticking line 10 without attaching the required Publication 519 statement.
- Using a P.O. box as the permanent residence or US address.
- Claiming a treaty article after its time limit has run out, such as a two-year teacher or researcher limit.
After you fill it out
Sign and date Part III and give the form, with any attachments, to your withholding agent. Keep a copy.
The agent reviews it, signs Part IV and, within five days of accepting it, sends a copy to the IRS (Philadelphia, PA 19255-0725, or by fax to 267-941-1365). The agent must wait at least ten days after mailing for any IRS objection; the exemption then applies back to the first payment it covers.
FileIt keeps the completed form in your vault. Set a reminder for next year's form, and for the end of your treaty time limit or your status expiry date.
Fill out Form 8233 online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 42 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real Internal Revenue Service (IRS) form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault. Sign it, or send it for e-signature.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start Form 8233 now — it’s freeForm 8233: frequently asked questions
Who do I give Form 8233 to?
To the withholding agent who pays you — usually your employer, university or the client paying for your services. You don't mail it to the IRS yourself; the agent forwards a copy after accepting it.
Do I need a new Form 8233 every year?
Yes. The instructions say to give a separate form for each tax year, each withholding agent and each type of income.
What if I don't have a social security number?
A US taxpayer identification number is required on line 2. If you aren't eligible for an SSN, apply for an ITIN with Form W-7.
Should I use Form 8233 or Form W-8BEN?
Form 8233 is for treaty exemptions on pay for personal services. Form W-8BEN is for claiming foreign status, or treaty benefits on other income such as a scholarship that isn't pay for services.
Why does the payer still withhold after I hand it in?
The withholding agent must wait at least ten days after mailing the form to the IRS in case the IRS objects. Once that passes, the exemption covers payments back to the first one the form applies to.
Can I fill out Form 8233 online?
With FileIt you answer guided questions and the answers are printed into the official IRS PDF, which you sign and give to your withholding agent. FileIt can also send it to the agent to sign Part IV.
Official sources
- Blank form (PDF), published by Internal Revenue Service (IRS): https://www.irs.gov/pub/irs-pdf/f8233.pdf
- Official instructions and guidance: https://www.irs.gov/forms-pubs/about-form-8233
- Edition shown on this page: Rev. September 2018 (checked 2026-10-19).
FileIt is not affiliated with or endorsed by Internal Revenue Service (IRS) or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-10-19.