What is OPS-1 change, revocation or termination of a special tax power of attorney?
OPS-1 (Zawiadomienie o zmianie / odwołaniu / wypowiedzeniu pełnomocnictwa szczególnego) is the official notice that ends or changes a special power of attorney in a Polish tax matter, under art. 138e of the Tax Ordinance. A special power of attorney is given on PPS-1 for one particular tax matter; OPS-1 is how the tax authority handling that matter learns that the principal has revoked it, that the attorney has terminated (given notice of) it, or that its scope or the permission to appoint a further attorney has changed.
The form says that a change, revocation or termination takes effect from the day the tax authority is notified (footnote 9). Until the authority has the notice, it can keep dealing with the attorney named on the PPS-1. The same OPS-1 can also report a change, revocation or termination of a further special power of attorney — one the attorney gave in turn.
FileIt walks you through each part in plain English, pre-fills your name from your People records, checks NIP and PESEL check digits, strikes out 'NIP' or 'PESEL' as the form asks, shows only the part that matches your purpose, checks that the matter and any new scope fit their printed lines, and prints everything in capitals onto the Ministry's own PDF, saved in your vault. You print, sign and deliver it yourself — FileIt never sends anything to any tax authority.
- Who fills it
- The principal (to revoke or change) or the attorney (to terminate)
- Given to
- The tax authority handling the matter (organ podatkowy właściwy w sprawie)
- Takes effect
- From the day the tax authority is notified (footnote 9)
- Signatures
- Signed by hand by the principal or the attorney; up to three representatives of a company per copy
- Edition
- OPS-1(3)
- Pages
- 3
Who needs to fill out OPS-1 change, revocation or termination of a special tax power of attorney?
- Individuals who gave a relative or adviser a special power of attorney (PPS-1) for a tax case and now want to withdraw it.
- Companies and other organisations ending or narrowing the mandate of a tax adviser, advocate or legal adviser in specific tax proceedings.
- Attorneys — including advocates, legal advisers and tax advisers — who no longer want to act and give notice of termination.
- Principals who want to widen or narrow what their attorney may do in the matter, or change whether the attorney may appoint a further attorney.
- Anyone ending or changing a further special power of attorney (substitution) that was reported on PPS-1.
When to use OPS-1 change, revocation or termination of a special tax power of attorney
- When you no longer want the person named on your PPS-1 to act for you in the tax matter.
- When you have been dismissed as a special attorney and want the authority to know, or when you as the attorney give the power of attorney up.
- When the case has moved on and the attorney needs a different scope, for example to also act in an appeal.
- When you want to allow, or stop allowing, the attorney to appoint a further attorney.
- As soon as the decision is made: the change only takes effect once the tax authority has been notified.
What you need before you start
- The name of the tax authority handling the matter, as on the PPS-1, e.g. NACZELNIK URZĘDU SKARBOWEGO W GDAŃSKU.
- A short description of the matter the power of attorney was given for, or the case reference number.
- The principal's NIP or PESEL (or, for a non-resident without one, a passport or other identity document) and address.
- The attorney's name and NIP or PESEL, address for service in Poland or electronic address — and, for a professional attorney, their list entry number.
- The date from which the revocation, termination or change applies, and for a change of scope, a clear description of the new scope.
- The names (and for a company, positions) of the people who will sign.
What’s on OPS-1 change, revocation or termination of a special tax power of attorney
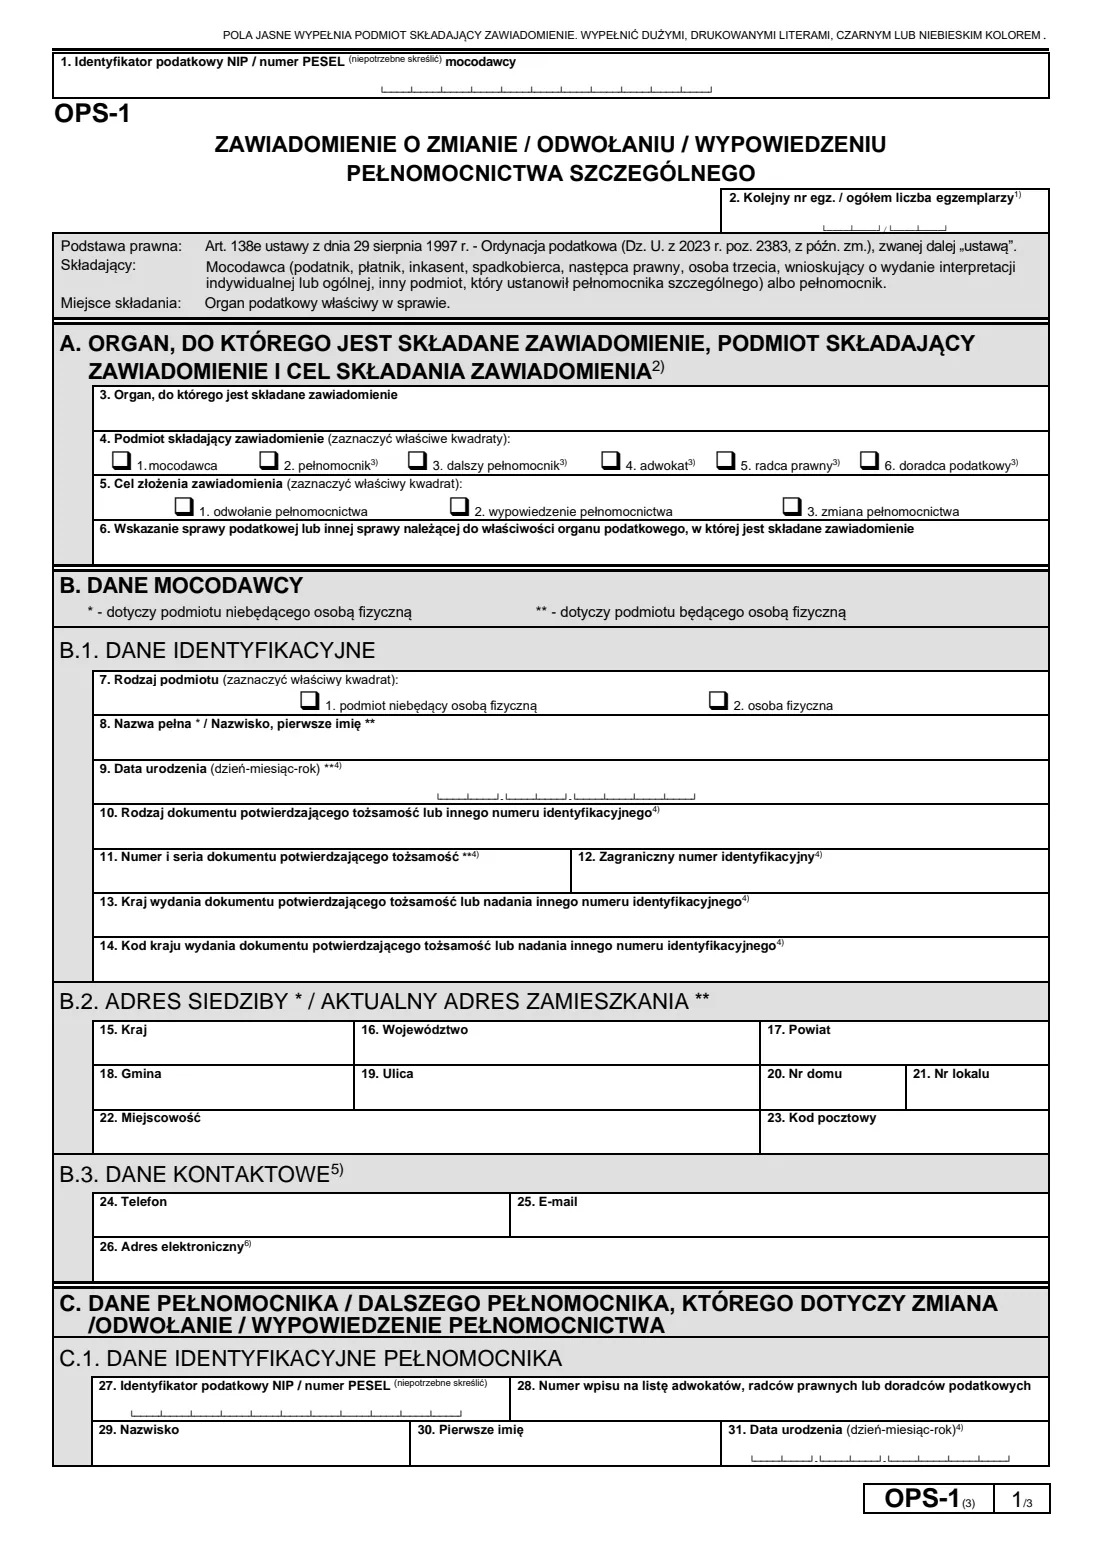
The 2026 edition has 3 pages. FileIt asks for it in 13 parts:
- A. Where it goes, who files it and why (Organ, podmiot składający zawiadomienie i cel składania zawiadomienia)Principal (mocodawca)
- B.1 The principal — who granted the power of attorney (Dane mocodawcy)Principal (mocodawca)
- B.2 Principal's registered office or current home address (Adres siedziby / aktualny adres zamieszkania)Principal (mocodawca)
- B.3 Principal's contact details (Dane kontaktowe)Principal (mocodawca)
- C.1 The attorney whose power of attorney is changed, revoked or terminated (Dane identyfikacyjne pełnomocnika)Principal (mocodawca)
- C.2 Attorney's address for service in Poland (Adres pełnomocnika do doręczeń w kraju)Principal (mocodawca)
- C.3 Attorney's contact details (Dane kontaktowe pełnomocnika)Principal (mocodawca)
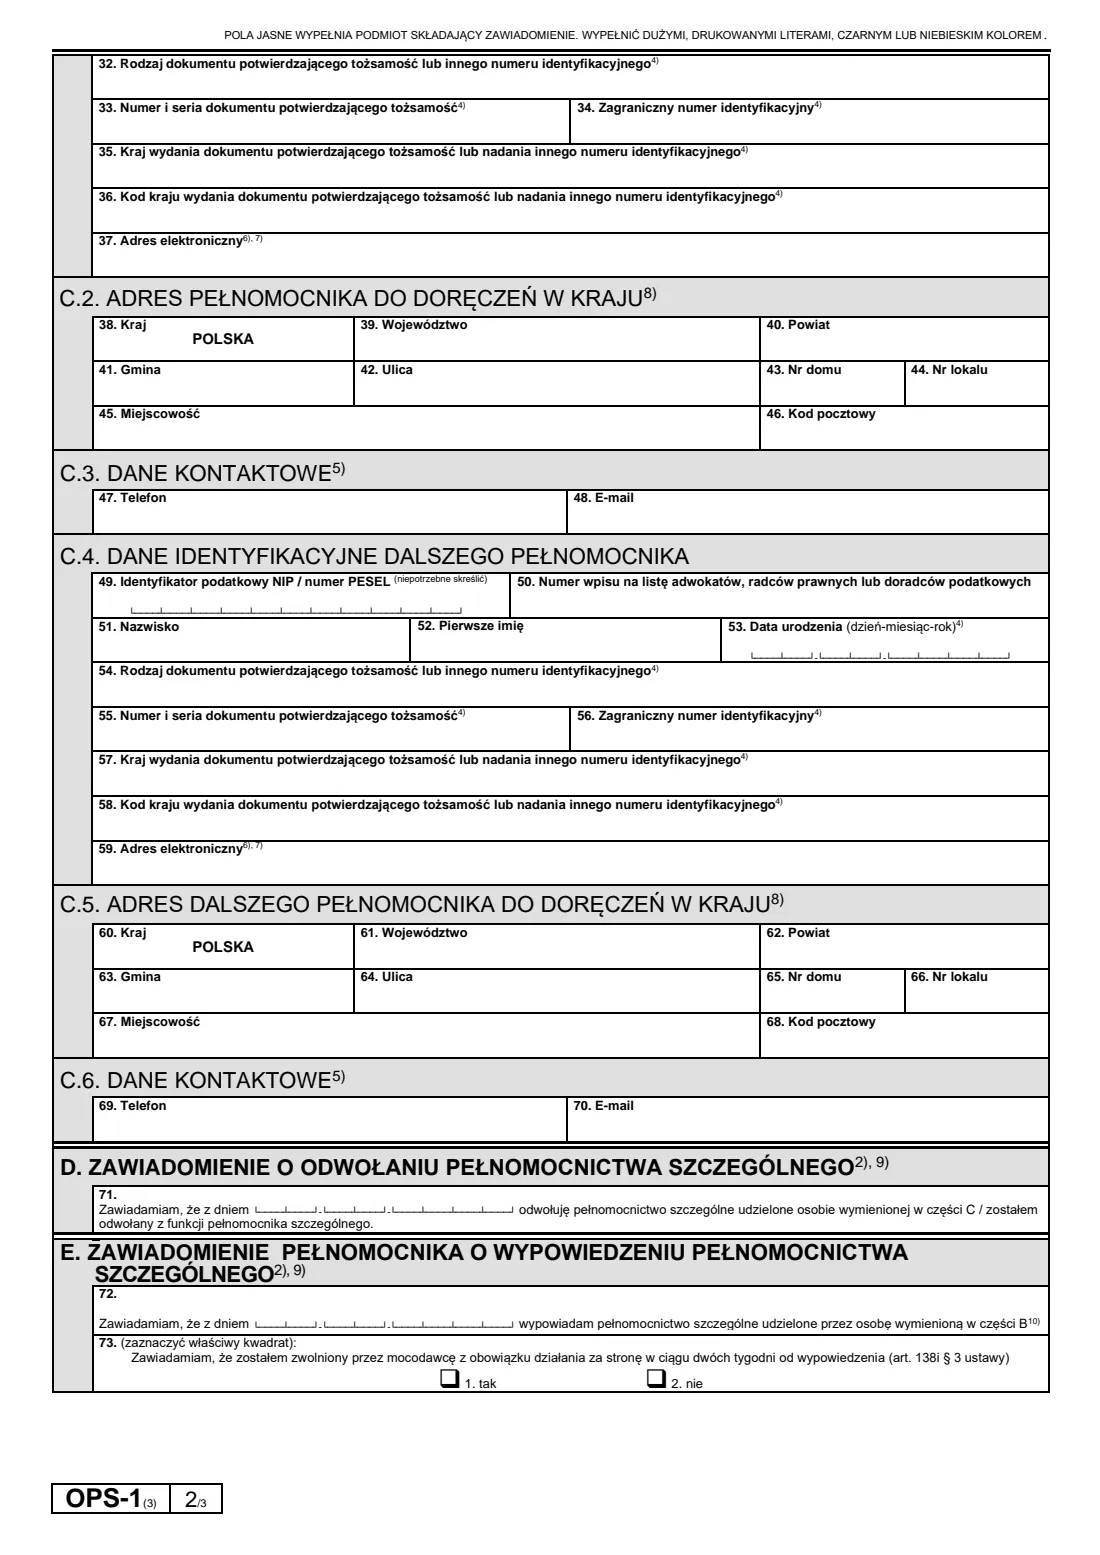
- C.4–C.6 The further attorney (Dalszy pełnomocnik)Principal (mocodawca)
- D. Revocation (Zawiadomienie o odwołaniu pełnomocnictwa szczególnego)Principal (mocodawca)
- E. Termination by the attorney (Zawiadomienie pełnomocnika o wypowiedzeniu pełnomocnictwa szczególnego)Principal (mocodawca)
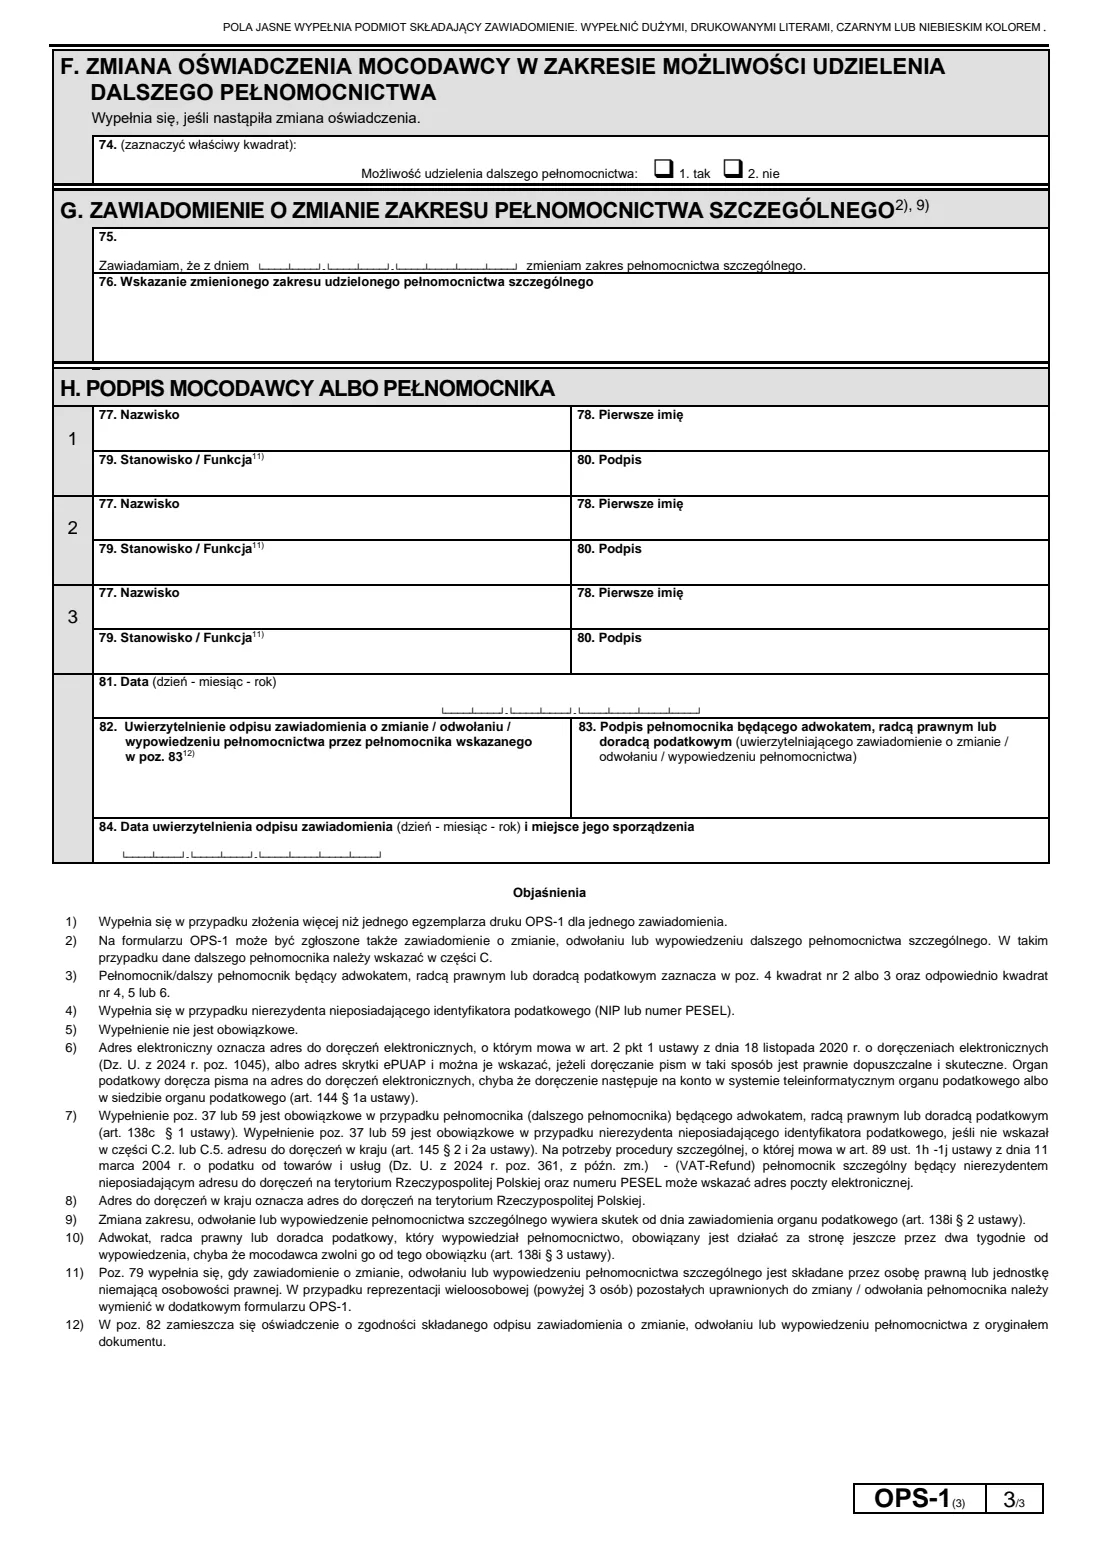
- F–G. Change of the power of attorney (Zmiana oświadczenia i zakresu pełnomocnictwa szczególnego)Principal (mocodawca)
- H. Who signs (Podpis mocodawcy albo pełnomocnika)Principal (mocodawca)
- Certified copy by a professional attorney (items 82–84)Professional attorney
How to fill out OPS-1 change, revocation or termination of a special tax power of attorney, step by step
1 Items 1–2: Principal's NIP / PESEL and copy number
Item 1 at the top of the form carries the principal's tax identifier. A company gives its NIP; a person gives the PESEL, or the NIP if they run a business or are registered for VAT. The form asks you to strike out whichever of 'NIP' and 'PESEL' you are not using, and FileIt does this for you from the length of the number.
Item 2 is only filled in when one notice needs more than one OPS-1 — for example when more than three people must sign for a company (footnotes 1 and 11).
2 A. Authority, who files it and why
Item 3 names the tax authority handling the matter. Item 4 says who files the notice: the principal, the attorney or a further attorney; a professional attorney also ticks advocate, legal adviser or tax adviser (footnote 3). Item 5 is the purpose — revocation, termination or change — and item 6 names the tax matter the power of attorney concerns.
3 B. The principal
Item 7 says whether the principal is a natural person or an organisation, and item 8 gives the organisation's full name or the person's surname and first name. Items 9–14 are only for a non-resident with no Polish NIP or PESEL (footnote 4). B.2 is the registered office or current home address, and B.3 (phone, email, electronic address) is optional (footnote 5).
4 C. The attorney and any further attorney
C.1–C.3 identify the attorney whose power of attorney is affected: NIP or PESEL, list entry number for a professional, name, and an address for service in Poland or an electronic address. Item 37 is compulsory for an advocate, legal adviser or tax adviser, and for a non-resident without a tax identifier who gives no Polish address (footnote 7). C.4–C.6 are used only when the notice concerns a further special power of attorney (footnote 2).
5 D. Revocation
Item 71: the principal notifies that, from the date given, they revoke the special power of attorney given to the person in part C — or the attorney notifies that they have been dismissed.
6 E. Termination by the attorney
Item 72: the attorney notifies that, from the date given, they terminate the special power of attorney given by the person in part B. An advocate, legal adviser or tax adviser must still act for the party for two weeks after terminating unless the principal released them from that duty (footnote 10); item 73 says whether they were released.
7 F–G. Change
Part F (item 74) is filled in only if the principal's statement on whether the attorney may appoint a further attorney has changed. Part G gives the date from which the scope changes (item 75) and the changed scope itself (item 76).
8 H. Signatures and certified copy
Items 77–80 are the surname, first name, position (for an organisation, footnote 11) and handwritten signature of up to three people; item 81 is the date. Items 82–84 are only for an advocate, legal adviser or tax adviser who certifies a copy of the notice as matching the original.
Common mistakes to avoid
- Using OPS-1 for a general power of attorney (PPO-1) or a power to sign tax returns (UPL-1) — those have their own revocation routes; OPS-1 is only for special powers of attorney given on PPS-1.
- Ticking 'termination' as the principal. The principal revokes; the attorney terminates.
- Sending it to the wrong office. It goes to the authority handling the matter the PPS-1 was filed in.
- Assuming the attorney's authority ended on the date you decided. The form says it ends from the day the tax authority is notified.
- Describing a new scope too vaguely or too long — item 76 has three printed lines, and a special power of attorney covers only what is written.
- Forgetting the positions of the people signing for a company, or leaving out a required co-signatory.
After you fill it out
Print the form, have each person sign by hand in item 80, and date it.
Deliver it to the tax authority handling the matter yourself. FileIt doesn't send it.
Keep the PDF in your FileIt vault, and tell the attorney (or the principal) that the notice has been filed.
To appoint someone new for the same matter, fill in a new PPS-1.
Fill out OPS-1 change, revocation or termination of a special tax power of attorney online with FileIt
- Pick the person. Choose someone from People and FileIt fills in their name, date of birth, address and other details it already knows.
- Answer plain-language questions. One part of the form at a time, with the official help text beside each question — 100 fields in all. Your answers save as you go.
- Check the live preview. Watch your answers land on the real Ministerstwo Finansów — Ministry of Finance of Poland (MF) form, and let FileIt do any worksheet arithmetic.
- Generate the official PDF. FileIt prints your answers into the agency’s own PDF and files it in that person’s folder in your vault.
FileIt fills the form — it never files or submits anything for you. Deliver the finished form to whoever asked for it, the way the form’s instructions say.
Start OPS-1 change, revocation or termination of a special tax power of attorney now — it’s freeOPS-1 change, revocation or termination of a special tax power of attorney: frequently asked questions
What is OPS-1?
It is the Polish Ministry of Finance form that notifies the tax authority that a special power of attorney (PPS-1) has been revoked by the principal, terminated by the attorney, or changed in scope or in the permission to appoint a further attorney.
When does the revocation or change take effect?
As the form's footnote 9 says, from the day the tax authority is notified (art. 138i § 2 of the Tax Ordinance).
Who signs OPS-1?
The person filing it: the principal for a revocation or change, the attorney for a termination. For a company, up to three representatives sign on one copy, with their positions; more go on another OPS-1.
Can I fill in OPS-1 online?
Yes. FileIt lets you fill it in online for free and prints your answers into the official PDF, saved in your vault. You then print it, sign it by hand and deliver it to the tax authority yourself.
Does an advocate or tax adviser who terminates stop acting immediately?
Not necessarily. Footnote 10 says a professional attorney who terminates must still act for the party for two weeks unless the principal releases them from that duty; item 73 records whether they were released.
Can OPS-1 cover a further attorney?
Yes. Footnote 2 says the same form can report a change, revocation or termination of a further special power of attorney; the further attorney's details go in C.4–C.6.
Is there a fee for OPS-1?
The form itself has no stamp-duty part, unlike PPS-1. FileIt doesn't state any fee for it.
Official sources
- Blank form (PDF), published by Ministerstwo Finansów — Ministry of Finance of Poland (MF): https://www.podatki.gov.pl/media/kzjbvpyz/ops-1-03-15.pdf
- Official instructions and guidance: https://www.podatki.gov.pl/pelnomocnictwa/formularze/
- Edition shown on this page: OPS-1(3) (checked 2026-10-01).
FileIt is not affiliated with or endorsed by Ministerstwo Finansów — Ministry of Finance of Poland (MF) or any government. This page explains the form in general terms and is not legal, tax or immigration advice. Always read the official instructions, and check that you are using the edition the recipient accepts. Page last reviewed 2026-10-01.